Adobe Has a Problem. It Also Has a Massive Opportunity
Adobe's stock has collapsed while its revenue keeps hitting records, and Wall Street is stuck in a holding pattern. A specific combination of catalysts could change that calculus dramatically before 2027 is over.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Adobe’s problem is perception. Investors worry that AI-native tools will chip away at Photoshop, Premiere and Acrobat. The business keeps growing anyway.
In fiscal Q3, Adobe (NASDAQ:ADBE | ADBE Price Prediction) posted record revenue of $6.76 billion, up 12.89% year over year. AI-first ARR passed $650 million and grew more than 150%.
“We’re just beginning to capitalize on the massive AI opportunity across creativity, productivity, and customer experiences,” said outgoing CEO Shantanu Narayen.
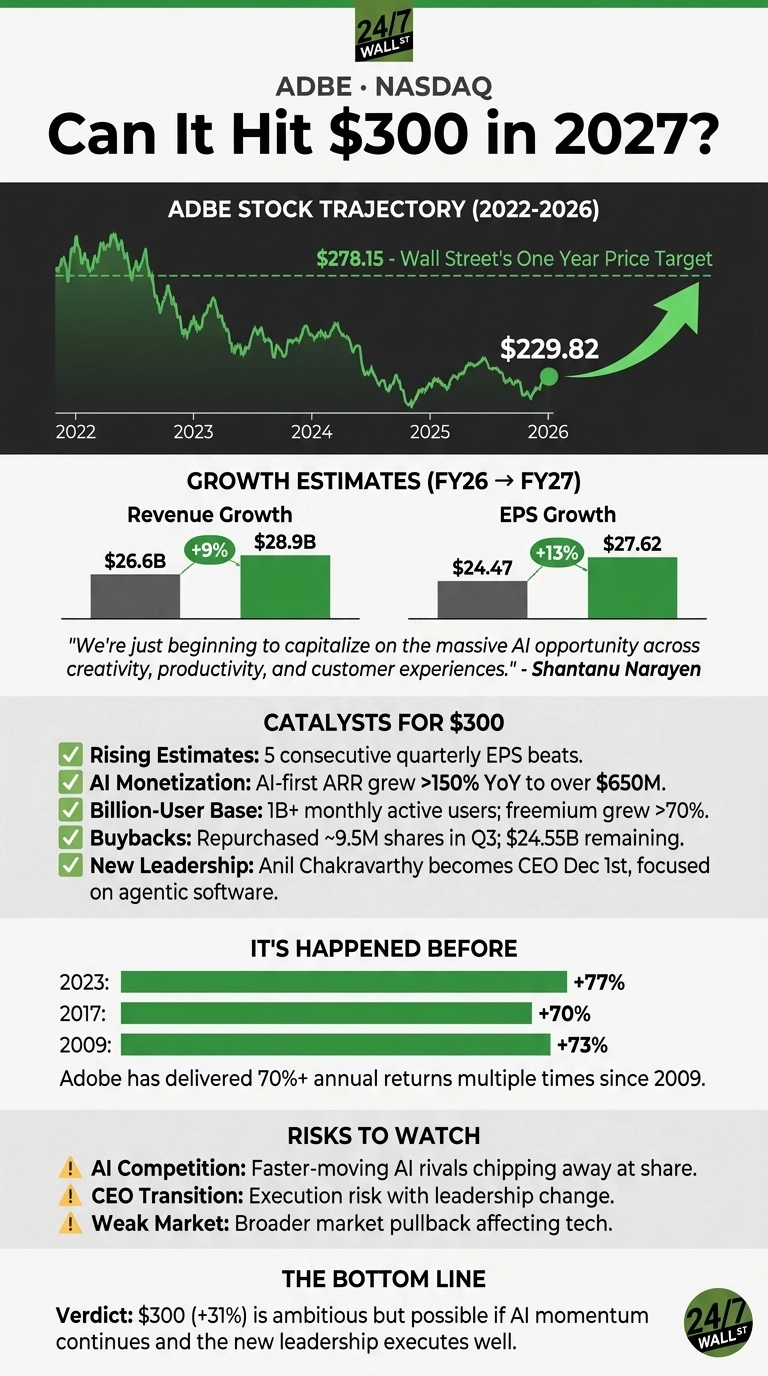
The stock has gone the other way. Shares are down 34.34% year-to-date at $229.82 and 63.09% over five years. So what would it take for Adobe to hit $300 in 2027?
Wall Street Sees 21% Upside as Estimates Creep Higher
Analysts’ average price target of $278.15 implies about 21% upside. Sentiment is lukewarm, with 23 Hold ratings. The numbers are stronger than the mood. Consensus calls for EPS of $24.4735 in FY2026, rising to $27.6226 in FY2027. That works out to roughly 13% EPS growth on about 9% revenue growth. The FY2027 estimate has also edged up from $27.5501 90 days ago.

Adobe also keeps beating expectations. Q3 non-GAAP EPS came in at $6.13, against a consensus of $6.0866. That was the fifth consecutive beat, so actual results could top today’s forecasts.

Here’s What It Takes for Adobe to Reach $300
At $229.82, Adobe trades at about 8x FY2027 earnings estimates. At $300, that multiple would be about 11x. That’s still well below the S&P 500’s forward multiple of roughly 21x to 23x, and Adobe guides for a Q4 non-GAAP operating margin of about 44%.

What Could Push Adobe to $300?
- AI monetization: Firefly ending ARR grew 40% quarter over quarter. Management also put pricing increases on hold to keep adding users, so that option is still available for 2027.
- A huge user base: Monthly active users passed one billion. Creative freemium users crossed 100 million, growing greater than 70%.
- Buybacks: Adobe bought back about 9.5 million shares in Q3, and $24.55 billion remains under its current authorization.
- New leadership: Anil Chakravarthy becomes CEO on December 1st. “I see immense opportunity for Adobe to be the leader in agentic software for creativity, productivity, and customer experience,” he said.
- Near-term events: Adobe MAX and the Topaz Labs deal, set to close in Q4, both come ahead of a seasonally strong enterprise quarter.
The risks: a weak market, a rough CEO transition or faster-moving AI rivals would make $300 harder to reach.

Adobe’s History Says $300 Is Possible
Getting to $300 requires a gain of about 31%. Adobe has done better than that in 10 calendar years since 2000. Shares rose 77% in 2023 and 70% in 2017.
The most useful comparison may be 2009, when the stock rallied 73% from a low starting point. With a market cap of $91.35 billion, Adobe is small enough that a move that size is realistic.
$300 Is a Stretch, but Adobe Has the Tools to Get There
Reaching $300 would take a 31% gain, more than the 21% Wall Street already guides for.
Several things support it: growing AI revenue, a billion users, a string of earnings beats and one of the lowest valuations among large software companies. If the new CEO settles in smoothly and the market cooperates, shares could return to 11x earnings. Returns this large shouldn’t be expected every year, but this is how Adobe could deliver outsized gains in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.