Costco Has One of Retail’s Strongest Businesses. Here’s What That Could Mean for the Stock
Costco just posted its fifth consecutive earnings beat and carries a renewal rate that almost no retailer can match, yet the stock sits well off its highs. Our model reveals whether that gap is an opportunity or a warning.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

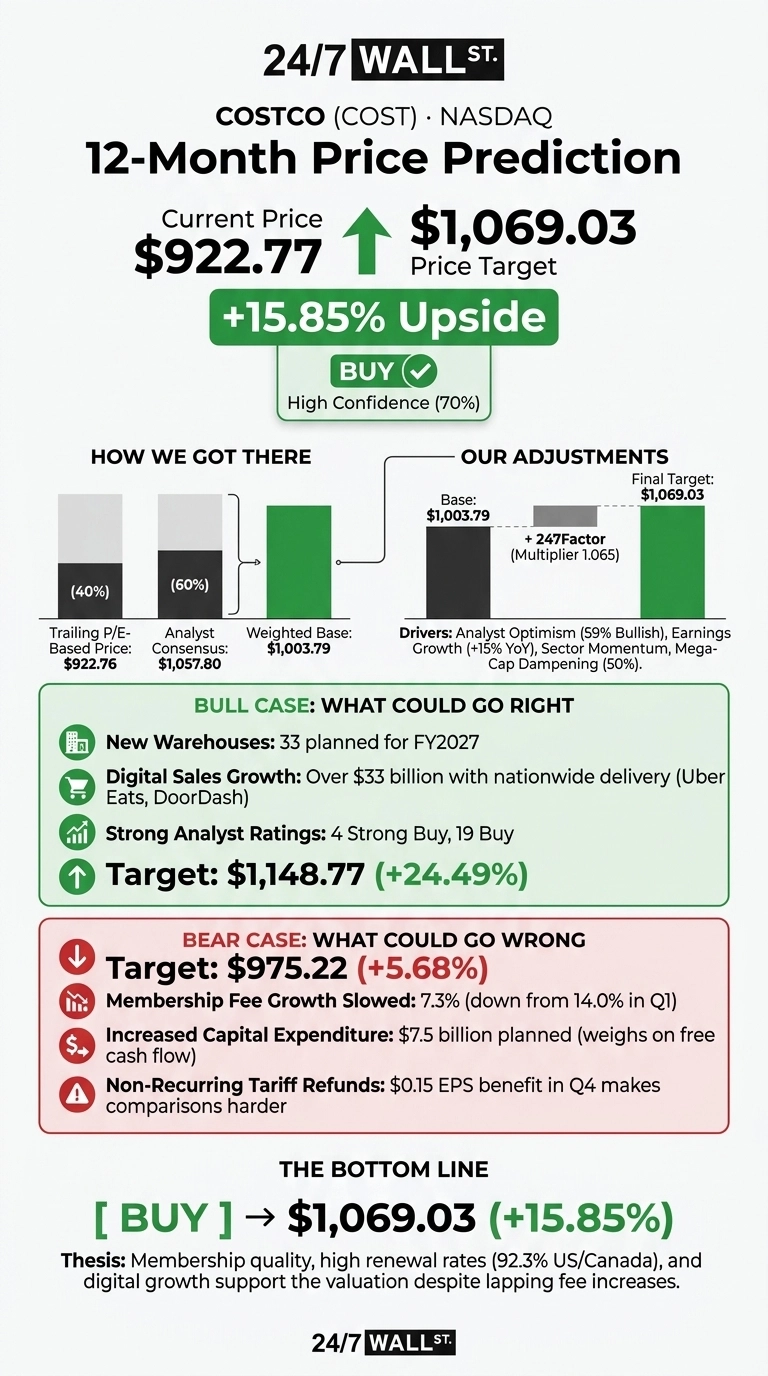
The price target from 24/7 Wall St. for Costco (NASDAQ:COST | COST Price Prediction) is $1,069.03 over the next 12 months. That means 15.85% upside from the model’s reference price of $922.77. The rating is buy, and our confidence is fairly high.
| Metric | Value |
|---|---|
| Current Price | $922.77 |
| Price Target from 24/7 Wall St. | $1,069.03 |
| Upside/Downside | 15.85% |
| Recommendation | BUY |
| Confidence Level | 70% |
Costco pairs a 92.3% U.S. and Canada renewal rate with 150.4 million cardholders. Few retailers can count on revenue that reliable. The stock trades near 44 times trailing earnings, so investors pay up for that strength. Even so, our model finds room for further gains.

Costco Beat Estimates Again, but the Stock Is Still Well Below Its High
Shares traded at $930.40 midday. That is up 3.92% over the past week and 8.37% year to date, but down 2.69% over the past month. The 52-week range runs from $840.35 to $1,094.76.
Fiscal fourth-quarter EPS came in at $6.75, beating the $6.53 consensus. Revenue reached $95.72 billion, ahead of the $94.85 billion estimate. That made five consecutive quarters of beats. Barron’s noted the beat wasn’t enough for the stock, while CNBC reported Goldman Sachs sees a sharp move higher.

Why Bulls See a Path to $1,148.77
In our bull case, the stock reaches $1,148.77. Costco plans to open 33 warehouses in fiscal 2027. Digitally enabled sales exceeded $33 billion after the Uber Eats and DoorDash rollouts went nationwide.
Pharmacy sales grew nearly 20%, and traffic from AI search grew triple digits. Analysts are mostly bullish, with 4 Strong Buy and 19 Buy ratings.

What Could Hold Costco Near $975.22
Our bear case lands at $975.22. Membership fee growth slowed to 7.3%, down from 14% in the first quarter. That slowdown mostly reflects Costco lapping its September 2024 fee increase. The reported gross margin rate slipped to 11.02%, although it rose 20 basis points excluding gas inflation.
Planned capex of $7.5 billion will weigh on free cash flow. That spending also funds future warehouses. Q4 EPS also includes a one-time $0.15 benefit from tariff refunds, which will make fiscal 2027 comparisons harder.

Is Costco Pricier Than Walmart and BJ’s?
Walmart (NASDAQ:WMT) competes directly with Costco through Sam’s Club. It trades at 38 times forward earnings, but its quarterly revenue grew only 5.9%. Costco’s faster growth helps justify its 40 forward multiple.
BJ’s Wholesale Club (NYSE:BJ) is the most direct warehouse-club comparison. It trades at just 19 times forward earnings, even with 15.7% revenue growth. That discount shows how much investors pay for Costco’s scale and loyalty. Measured against Walmart, our target looks reasonable. Measured against BJ’s, it looks rich.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Costco | 40 | 11.1% |
| Walmart | 38 | 5.9% |
| BJ’s | 19 | 15.7% |
Membership Quality Supports Our BUY Rating
Our 24/7 Wall St. price target of $1,069.03 comes with a buy rating and 70% confidence. The key factor is membership quality. Executive members now drive 75.6% of sales.
I’d stay positive as long as renewal rates hold and digital growth continues. I’d turn more cautious if comparable sales slow while the valuation stays above 40 times earnings.
Looking further out, here is where our model projects Costco could trade if current growth trends and market conditions continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $943.79 |
| 2027 | $1,061.82 |
| 2028 | $1,209.95 |
| 2029 | $1,307.26 |
| 2030 | $1,394.73 |
The estimates rely on Costco continuing to execute on its warehouse and digital strategy. A faster rate of openings could push results higher. Valuation compression or tariff shocks could push them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.