Amazon Target Lifted as Rosenblatt Says AI Agents Won’t Disrupt Business Model
Wall Street has grown increasingly nervous that AI shopping agents could hollow out Amazon's retail media empire, and the stock has the bruises to prove it. Rosenblatt just raised its price target and laid out a pointed case for why…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
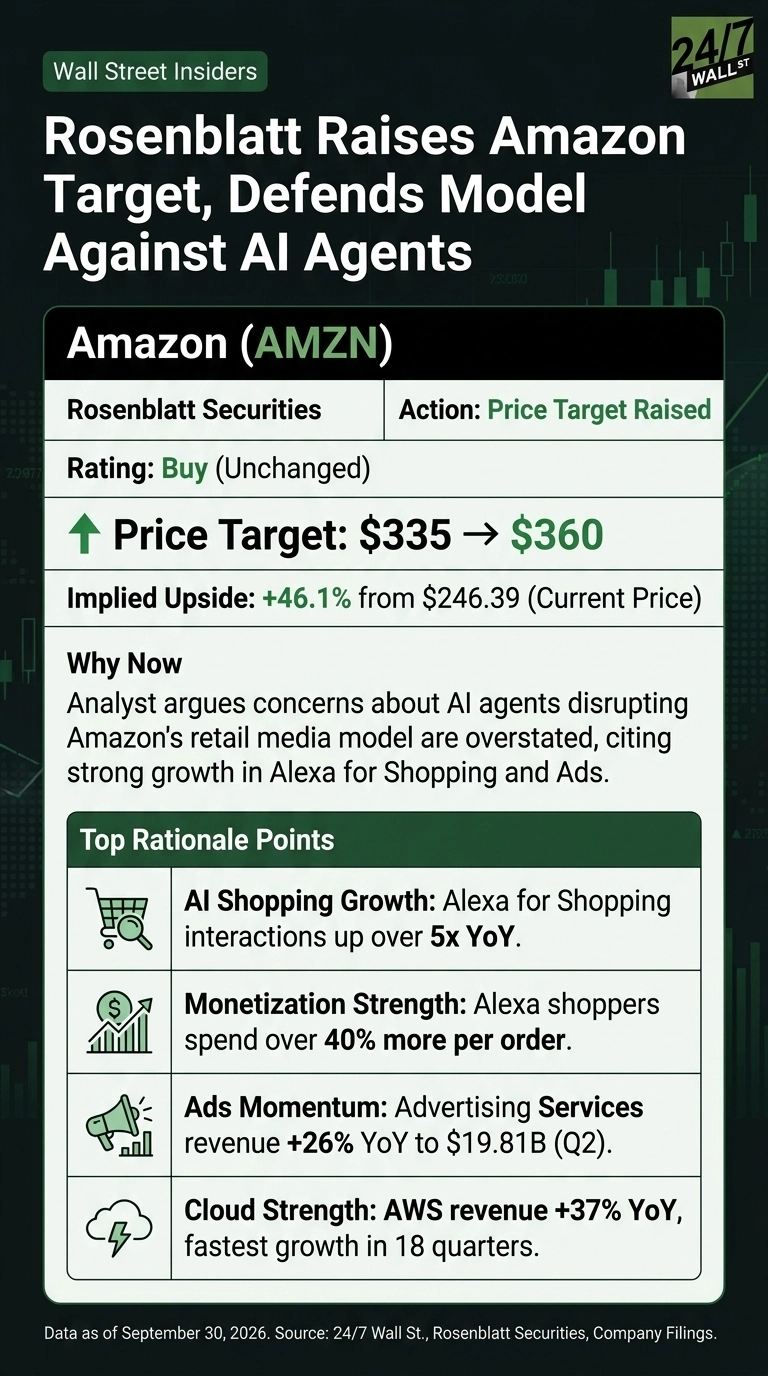
Rosenblatt raised its price target on Amazon (NASDAQ:AMZN | AMZN Price Prediction) to $360 from $335 and kept its Buy rating. The firm says that concerns about AI shopping agents replacing Amazon’s retail media model are overstated.
The higher target comes with the stock at $246.39, after a 7.52% drop over the past month. For those with a longer time horizon, the call is a reminder that Amazon has adapted to big changes in how people shop before.

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| AMZN | Amazon | Rosenblatt | Price Target Raised | Buy | Buy | $335 | $360 |
Rosenblatt’s Case That AI Agents Leave Amazon Standing
Personal agents and AI shopping assistants “compress the discovery and purchase funnel,” the analyst told investors. That has raised concerns that Amazon’s retail media model could be pushed out entirely.
Rosenblatt thinks that risk is overstated. The “narrative is false, and this is not the first time Amazon has faced pressure against secular changes in consumer behavior,” the firm wrote.
Rosenblatt also raised its long-term estimates. It said it is confident that even if the advertising model changes, Amazon “can navigate this period of transition largely unaffected.”
Amazon’s own numbers back up that view. More than 350 million customers used Alexa for Shopping, the company’s agentic shopping assistant, over the last 12 months. Interactions rose over 5x year over year.
Customers who use it spend over 40% more per order. Shoppers who click a sponsored prompt convert to a sale 48% more often and spend 21% more on average.
Company Snapshot: AWS and Ads Keep Growing
Second-quarter revenue reached $200.61 billion, up 19.6% and beating the $196.43 billion estimate. GAAP diluted EPS came in at $5.75. That figure includes a $53.4 billion one-time gain linked largely to Anthropic. On a comparable basis, EPS was about $1.88, exceeding expectations of $1.83.
AWS revenue rose 37% to $42.23 billion, with a 39.4% operating margin. Advertising grew 26% to $19.81 billion. For the third quarter, Amazon guided net sales of $197 billion to $202 billion and operating income of $22.5 billion to $26.5 billion.

Why This Call Lands During a Pullback
The stock is trading below its 52-week high of $287.2 and its 50-day moving average of $256.15. Concern about rival AI agents has hung over the shares. This week, the Wall Street Journal said the stock has the “Muse Blues.”
Amazon trades at about 24 times forward earnings. Analysts are generally positive, with 15 Strong Buy, 44 Buy and 2 Hold ratings. The average target is $329.54, so Rosenblatt’s new target sits above the consensus.

What It Means for Your Portfolio
Rosenblatt’s analyst note addresses directly to the biggest story weighing on Amazon stock right now. There are real risks. Capital spending reached $54.2 billion in one quarter, and trailing free cash flow turned negative at -$7.6 billion.
Investors focused on retirement should keep an eye on Amazon’s ad growth and Alexa for Shopping engagement in the next earnings report. The results should show whether AI agents are growing Amazon’s business or eating into it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.