AstraZeneca’s $2 Billion Vote of Confidence Leaves Summit Therapeutics Trading Well Below Street Targets
AstraZeneca just locked in a price to own 12% of Summit Therapeutics that the open market refuses to match, and two clinical deadlines in 2026 will determine whether Wall Street or the pharma giant read ivonescimab correctly.

AstraZeneca (NASDAQ:AZN | AZN Price Prediction) just agreed to invest $2 billion in Summit Therapeutics (NASDAQ:SMMT) through preferred stock that converts at $18.36 per share. Summit currently trades at $16.39, below the price one of the world’s largest drugmakers locked in.
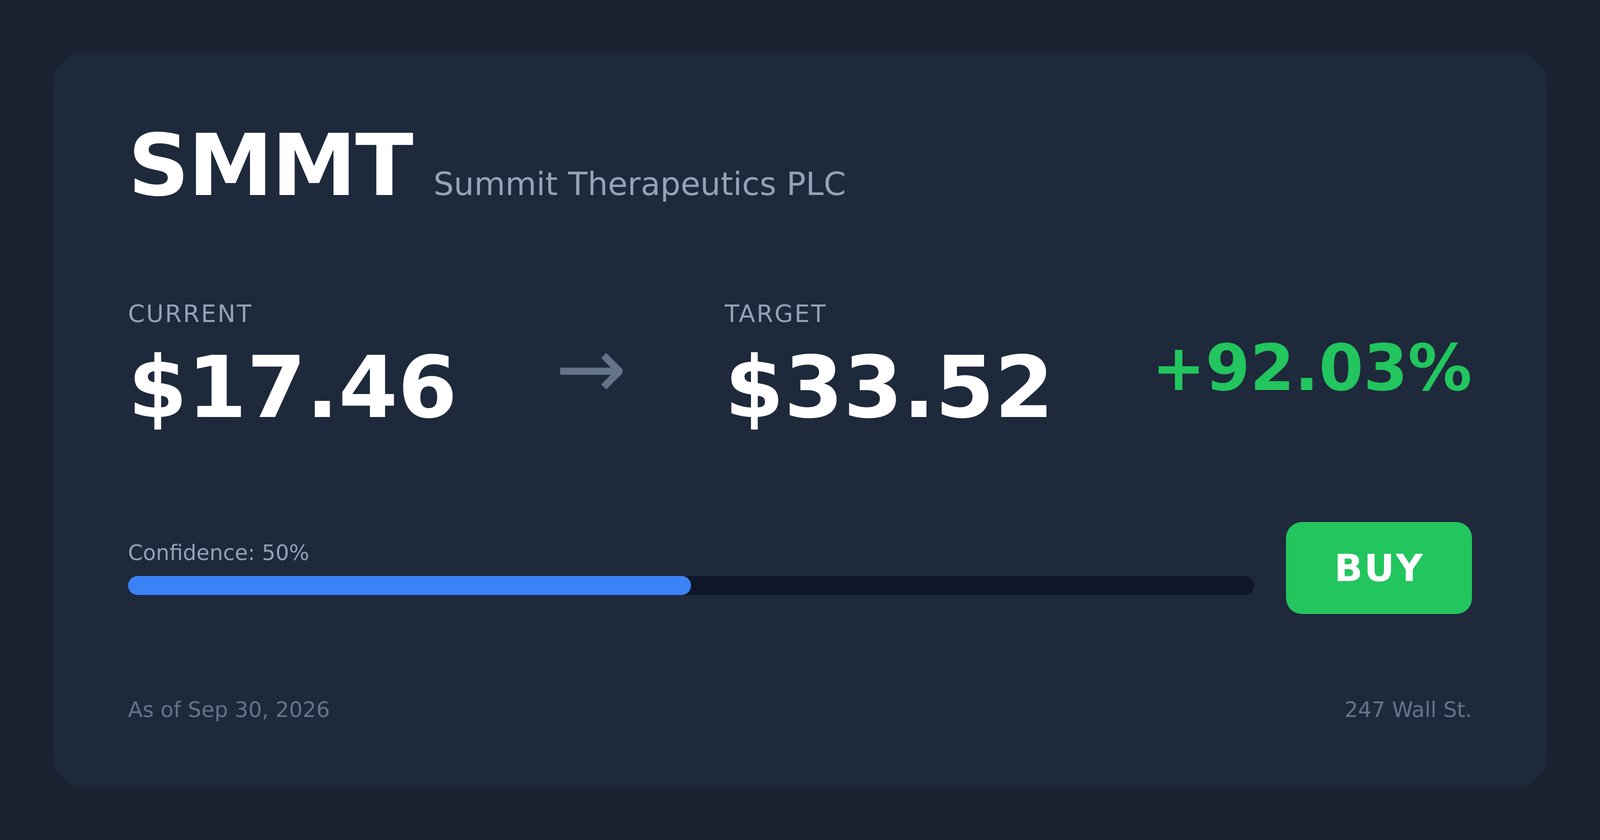
Shares rose 20% before the open, then fell back to close up 5.88%.
Summit has gained 19.37% over the past month. Yet it is down 6.29% year to date and 22.54% over the past year, while the S&P 500 gained 12.07% and 15.15% over those periods.
Summit has no product revenue. Its value depends on ivonescimab, a single drug. The AstraZeneca money adds cash and credibility, though clinical questions that set the stock’s real value remain open ahead of a regulatory decision.
What AstraZeneca’s $2 Billion Actually Buys
The preferred shares convert into Summit common stock equal to about 12% of the company. The conversion price was an 18.6% premium to the $15.48 close before the announcement.
AstraZeneca gets no licensing rights to ivonescimab. The committed collaboration is a trial testing ivonescimab alongside AstraZeneca’s experimental drug sonesitatug vedotin in gastrointestinal cancers.
Everything else sits in a non-binding agreement to explore other combinations, which obligates neither company to run another study.
Executive chairman Robert Duggan commented. He said, “This investment and collaboration validate ivonescimab’s potential.” A validation investment creates no obligation for AstraZeneca to buy the rest of Summit.
Why Wall Street Won’t Pay AstraZeneca’s Price
Preferred stock carries rights common shareholders do not get, so the conversion price reflects a different security, and the deal was negotiated privately, with no buyer posting an open-market bid at that level.
AstraZeneca had not seen the HARMONi-3 data before investing. The partner accepted the same clinical uncertainty you would, so its price offers no protection if the trial disappoints.
A partner holding roughly a tenth of the company may gain influence over strategy, which could help or hurt minority holders depending on alignment.
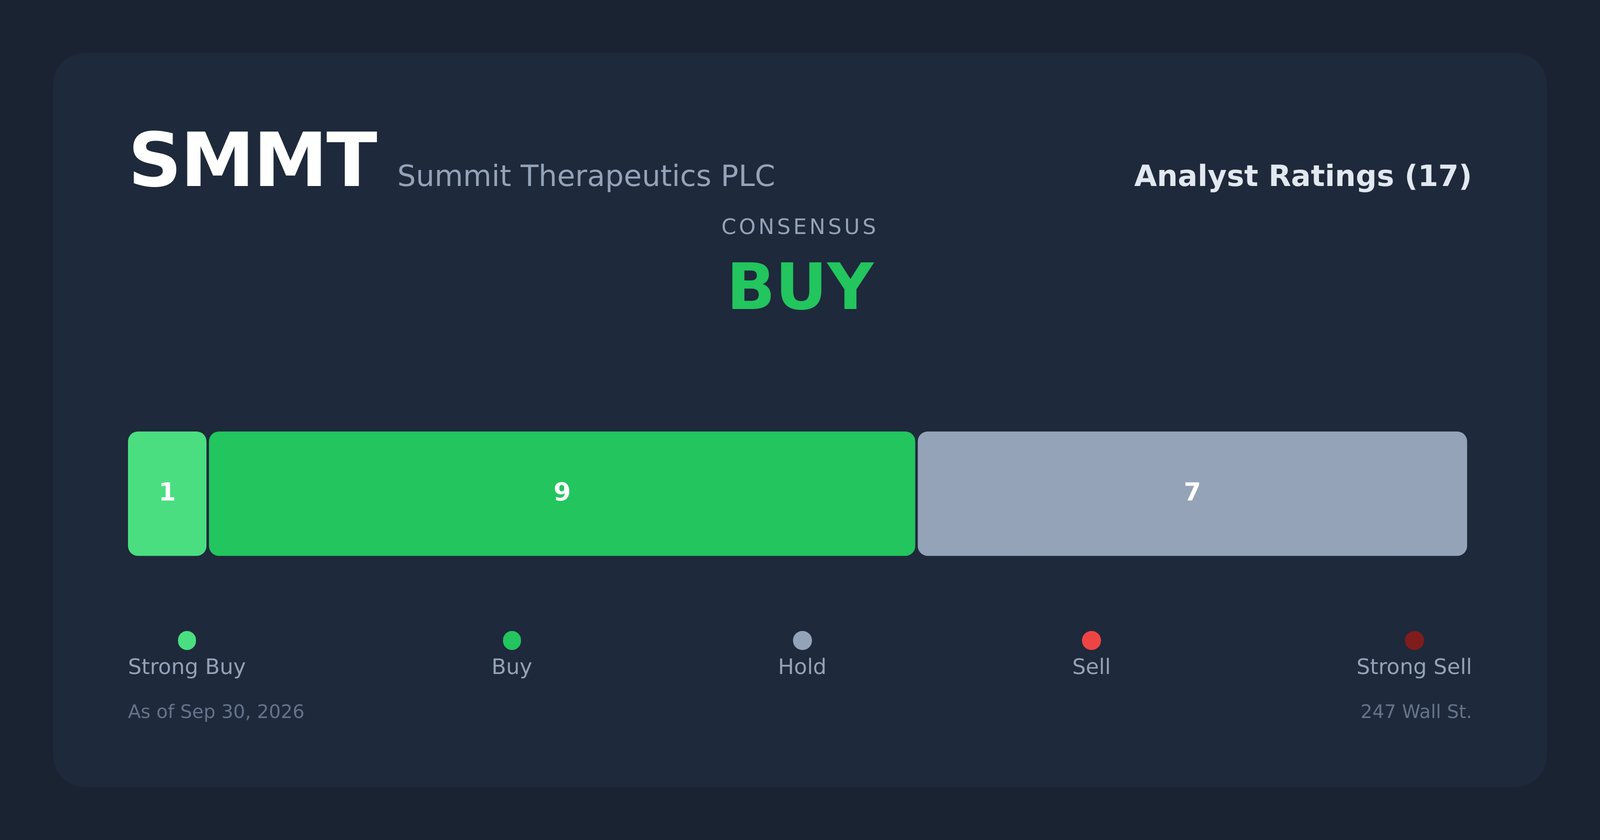
Citi raised its target to $43 from $40, calling the deal “a strong external validation of ivonescimab.” The market clearly disagrees for now.
Two Deadlines Will Decide Whether the Gap Closes
Ivonescimab is a bispecific antibody. That means it blocks two targets at once: the PD-1 immune checkpoint and the VEGF pathway tumors use to build blood vessels. Summit licensed it from China’s Akeso.
The FDA is due to decide on its first approval, in EGFR-mutant non-small cell lung cancer, by November 14, 2026. Data from the larger HARMONi-3 trial is due by the end of 2026.
An approval would make Summit a commercial company and give the conversion price real support. A rejection or weak results could send the stock back toward its 52-week low of $12.07, regardless of what AstraZeneca paid.
Western investors have repeatedly mispriced China-licensed drugs in both directions. Summit’s updated HARMONi analysis showed an overall survival hazard ratio of 0.76 in both the total and Western populations, which speaks directly to that skepticism.
$2.5 Billion Removes the Dilution Overhang
Clinical-stage biotechs spend cash long before earning revenue, so they sell new shares repeatedly, and when investors expect that selling, the financing burden keeps the stock held down.
Summit fits the pattern. It raised $231 million through at-the-market share sales last quarter and filed for a new facility of up to $380 million.
The investment lifts cash to about $2.5 billion from $690.7 million, with no debt. Summit can now fund a launch without selling stock at low prices before the data arrives.
The risk-reward tilts positive, though only for small positions given the potential for total loss. Binary biotech outcomes make position sizing the only real risk control.
The case rests on a partner paying a premium, a funded balance sheet, and a drug that has produced positive data in four Phase 3 studies. The danger is that AstraZeneca invested without seeing HARMONi-3, and one disappointing result could erase the premium.
For lower-risk exposure, AstraZeneca participates in the collaboration while spreading risk across a large commercial portfolio.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.