Cloudflare at $350: AI Cybersecurity Threats Aren’t Enough to Move the Needle Now
Cloudflare has surged nearly 80% this year on the back of an AI security boom, but the stock now trades at a multiple that punishes any stumble. The next two earnings reports will determine whether this rally was justified or…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Cloudflare (NYSE:NET | NET Price Prediction) is a Hold at $352.22. The stock has gained 78.66% this year, so the key question is whether demand for AI-era security can support a valuation that already assumes years of strong execution.
Cloudflare runs a global network that offers security, performance, and developer tools. It now presents itself as core infrastructure for AI agents. The rally picked up after second-quarter revenue of $696.06M rose 35.9% year over year. That result came with a fourth straight EPS beat and raised guidance. Shares were $292.47 when the results came out.
Faster Growth and an Agent-First Security Pitch Power the Bull Case
Revenue growth has sped up for three straight quarters, from 30.7% to 33.5% to 35.9%. Management raised full-year non-GAAP EPS guidance to $1.25 to $1.26, up from $1.19 to $1.20. Signed revenue not yet recognized reached $2,732,000,000, up 38%. Dollar-based net retention, which tracks how much more existing customers spend, rose to 120%.
Security demand tied to AI is showing up in sales. CEO Matthew Prince said “the number one thing that’s causing our phone to ring from big companies is them saying, listen, we know we have to do AI, but we need to do it more securely.” Analysts revised full-year EPS estimates up 30 times in the past month. CrowdStrike (NASDAQ:CRWD) trades at 208x forward earnings while growing revenue 25.8%.
A 179x Forward Multiple Leaves Little Room for a Slowdown
Cloudflare trades at 179x forward earnings and 50.17 times trailing sales. Zscaler (NASDAQ:ZS) trades at 44x forward earnings. Third-quarter guidance points to 31% growth, a slowdown from the second quarter.
Profitability is getting worse on a GAAP basis. The net loss grew to $170.0M from $50.4M, driven by a $150.7M restructuring charge. Stock-based compensation reached $140.6 million. Non-GAAP gross margin fell to 73.1% from 76.3%, and the company has about $3.3B in convertible debt.
Why Third-Quarter Results Should Settle This Debate
Four straight quarters of beats and rising guidance make a Sell hard to defend. A multiple this high makes a Buy hard to defend too. The next test is whether third-quarter revenue beats the $736-737M guidance by the usual margin. CFO Thomas Seifert warned that consumption-based contracts make “how we move from quarter to quarter” harder to forecast. Restructuring charges of up to $165 million will weigh on GAAP results.
Shares Have Outrun Both the S&P 500 and Wall Street’s Target
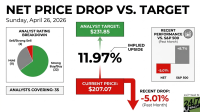
The average analyst target of $336.81 implies about 4.4% downside. Of 34 analysts, 24 rate the stock a Buy.
- Strong Buy: 7
- Buy: 17
- Hold: 8
- Offers: 1
- Strong Sell: 1
Year to date, Cloudflare is up 78.66%, while the S&P 500 is up 12.08%. Over the past month, the stock rose 17.47%, though the index slipped 0.66%. Shares now sit just below their 52-week high of $367.43.
Cloudflare Is a Hold Until Growth Justifies the Premium
At $352.22, Cloudflare is a Hold.
The AI security story is real, and the stock price reflects it. A Buy case would need third-quarter growth holding in the mid-30s despite guidance calling for 31%, or a decline toward the 50-day moving average of $301.26. A Sell case would build if growth slows to the forecast pace and gross margins keep falling.
With a beta of 1.664, any disappointment would likely hit this stock harder than the broader market. Over the next two quarterly reports, watch revenue growth, gross margin, and whether the restructuring pays off in operating leverage.
Cloudflare has earned its premium, and the next two earnings reports need to show that growth can keep pace with a valuation that already prices in the AI boost.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.