Microsoft Stock Has Multiple Engines Driving Its Next Leg Higher
Azure is accelerating past 40% growth, Copilot seats are doubling quarter over quarter, and a commercial backlog approaching $700 billion sits waiting to convert. Whether those engines can actually lift Microsoft back above its all-time high depends on a few…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
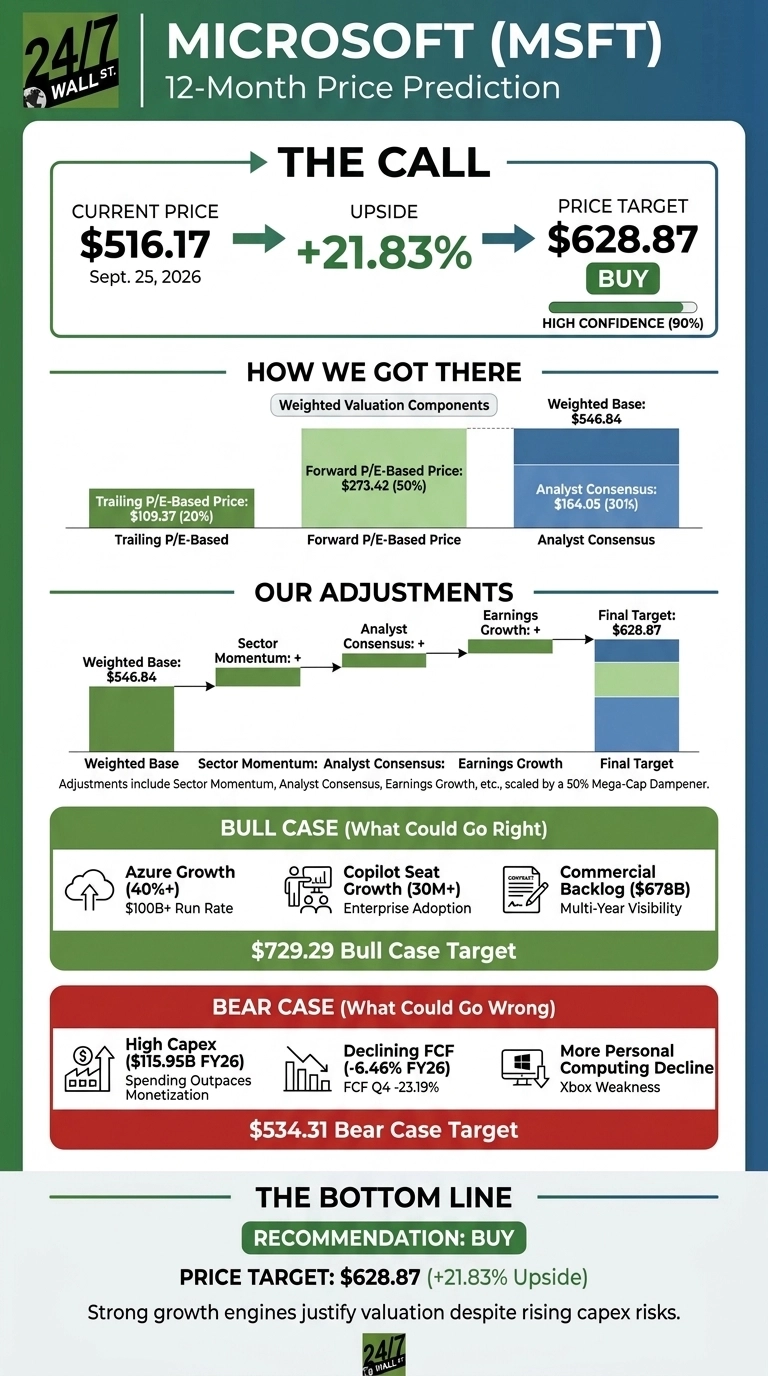
Microsoft (NASDAQ:MSFT | MSFT Price Prediction) closed at $516.17 on September 25. The 24/7 price target is at $628.87 over 12 months, meaning 21.83% upside with a buy rating and high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $516.17 |
| Price Target from 24/7 Wall St. | $628.87 |
| Upside/Downside | 21.83% |
| Recommendation | BUY |
| Confidence Level | 90% |

Microsoft has several growth drivers running together. Azure is growing at a rate above 40%, Copilot seat growth is speeding up, and the company is carrying a $678 billion commercial backlog. Each one adds to the base case.
Microsoft Is Back Within 6% of Its 52-Week High After a Record Year
Shares gained 4.53% over the past week and 7.41% year to date. The stock trades about 6% below its $549.20 52-week high. Microsoft also announced a quarterly dividend increase on September 15.
Fiscal Q4 revenue came in at $90.01 billion, up 17.75%. That was ahead of the $87.63 billion estimate. EPS of $4.74 beat expectations of $4.2394, though a $3.2 billion Anthropic gain helped the number.
Why Bulls See $729 Within Reach
Azure grew 43% and passed $100 billion in annual revenue. Management’s fiscal Q1 guidance calls for about 45% growth in constant currency. Microsoft 365 Copilot now has more than 30 million paid seats, and net seat additions more than doubled quarter over quarter. GitHub Copilot has 50 million users. Management said “demand continues to exceed available supply.”

Wall Street is overwhelmingly positive, as 14 Strong Buy, 38 Buy and 3 Hold ratings show. If Azure keeps accelerating, our bull case hits $729.29.

What Could Stall Microsoft’s Rally
Fiscal 2026 capex rose 79.62% to $115.948 billion, and free cash flow fell 6.46%. More Personal Computing revenue slipped 4%, and Xbox dropped 10%.
Operating cash flow rose 34.35%. CFO Amy Hood noted Microsoft can “slow down” GPU and CPU spending if demand cools. In our bear case, shares hits $534.31, still above today’s price.
How Microsoft Compares to Alphabet and Amazon
Alphabet (NASDAQ:GOOGL) competes via Google Cloud at 23x forward earnings with 24.2% revenue growth.
Amazon (NASDAQ:AMZN) runs AWS at 24x with 19.6% revenue growth. Microsoft trades at a premium but commands much higher margins, justifying the valuation.
| Company | Forward P/E | Operating Margin |
|---|---|---|
| Microsoft | 25 | 45.1% |
| Alphabet | 23 | 34% |
| Amazon | 24 | 13.7% |
Our 24/7 Wall St. price target looks reasonable and not extended against these peers.
Microsoft Earns a BUY Rating at These Levels
Microsoft earns a buy rating with high confidence at our 24/7 price target of $628.87. The backlog is critical: about 30% of RPO converts to revenue within 12 months.
Stay positive as long as Azure grows above 40%. Grow cautious if capex keeps rising while free cash flow falls. For now, growth outlook justifies the valuation.
Here is where our model sees Microsoft trading in the coming years, assuming its current growth trend holds.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $532.20 |
| 2027 | $660.31 |
| 2028 | $735.15 |
| 2029 | $829.12 |
| 2030 | $881.23 |
These projections assume Microsoft keeps performing as it has been. Actual results could come in well above or below them depending on how quickly Copilot is monetized and what AI infrastructure ends up returning. All that hyperscaler capex has to flow to power, cooling, and networking suppliers too, and we highlighted seven of them in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.