The AI Revolution Could Be Microsoft’s Next Trillion-Dollar Opportunity
Azure's explosive backlog and Copilot's paid seat growth have bulls eyeing targets near $700, but a capex surge that outpaced free cash flow by a wide margin could threaten the entire AI thesis before it pays off.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
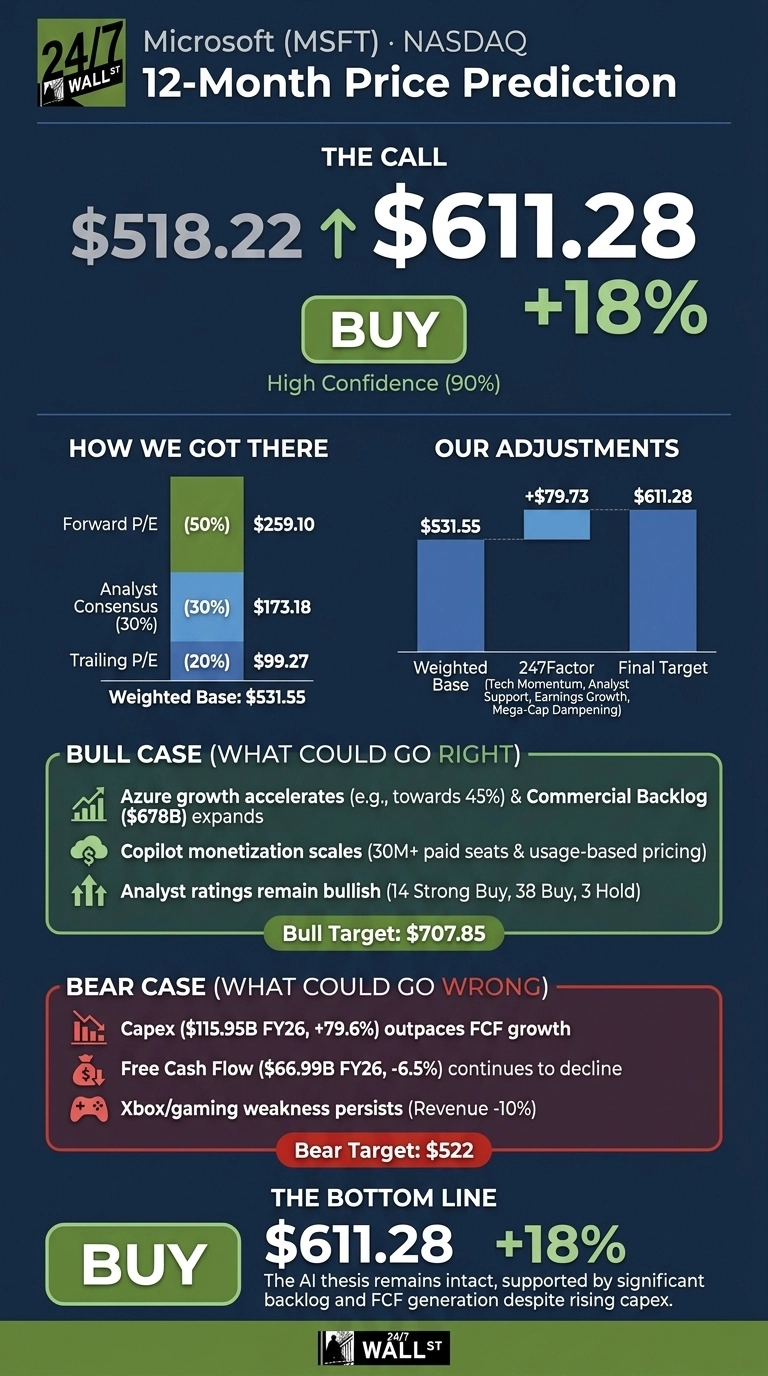
Our 24/7 Wall St. price target for Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is $611.28 over the next 12 months. With shares trading at $518.22, that works out to about 17.96% upside. Our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $518.22 |
| Price Target from 24/7 Wall St. | $611.28 |
| Upside/Downside | 17.96% |
| Recommendation | BUY |
| Confidence Level | 90% |
We set the target off the $496.37 close on September 24. Friday’s 4.07% jump narrowed that gap. The AI thesis remains intact.

Microsoft Is Winning Back Its Capex Selloff Losses
Microsoft is up 4.11% this week, 5.39% over the past month and 7.84% year to date, sitting about 5.6% below its 52-week high of $549.20. It has gained 31% since trading at $395.50 when fiscal Q4 earnings came out.
Revenue of $90.01 billion beat the $87.63 billion estimate, and EPS of $4.74 beat the $4.24 consensus, marking the fifth consecutive EPS beat. This week, Stifel upgraded the stock, and Microsoft bundled its business AI tools into a single app to compete with Anthropic.

Why Bulls See $707 or Higher
Last quarter Azure grew 43%, with management guiding to about 45% growth in constant currency for fiscal Q1. Commercial backlog rose 84% to $678 billion. Microsoft 365 Copilot passed 30 million paid seats with net increases more than doubling sequentially.
Usage-based pricing on top of per-seat fees creates new revenue. Analysts are nearly all bullish, with 14 Strong Buy ratings, 38 Buys and just 3 Holds. In our bull case, the stock reaches $707.85.

Capex Risks Could Stall Microsoft Near $522
Microsoft’s capex rose 79.62% to $115.948 billion in fiscal 2026 while free cash flow fell 6.46%. Xbox revenue declined 10%, and Q4 EPS benefited from a $3.2 billion Anthropic gain.
Operating cash flow rose 34.35%, and adjusted EPS grew 23% excluding OpenAI effects. CFO Amy Hood noted capex is shifting toward “short-lived assets” that can be cut if demand slows. In our bear case, the stock reaches $522.

Is Microsoft Cheaper Than Alphabet and Amazon?
| Company | P/E | P/FCF | Cloud Growth |
|---|---|---|---|
| Microsoft | 28 | 55 | 43% |
| Alphabet | 15 | 56 | 82% |
| Amazon | 35 | 350 | 37% |
Microsoft and Alphabet (NASDAQ:GOOGL) vie for enterprise AI customers. Google Cloud grew 82%, faster than Azure, but Alphabet’s low P/E is inflated by $99 billion in unrealized equity gains and free cash flow turned negative at -$5.855 billion.
AWS, operated by Amazon (NASDAQ:AMZN), grew 37% with trailing 12-month free cash flow of -$7.6 billion. Only Microsoft creates significant free cash flow while spending heavily on AI, supporting our price target.
Our Model Stays Bullish on Microsoft
The 24/7 Wall St. price target of $611.28 comes with a buy rating and 90% confidence. Microsoft’s $678 billion signed backlog provides visibility its peers lack.
The case strengthens if Azure speeds up toward 45% and free cash flow remains positive. Rising capex alongside flattening Copilot adoption would weaken it. On current numbers, the stock has room to rose.
These are our model’s base case projections assuming Microsoft’s current growth rates and market conditions continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $611.28 |
| 2027 | $613.99 |
| 2028 | $723.06 |
| 2029 | $777.79 |
| 2030 | $853.36 |
These figures assume Microsoft continues executing its AI strategy. Faster Copilot monetization could drive the stock higher than these targets. An AI capacity glut could pull it lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.