Analysts Are Bullish on Micron. The Numbers Argue for Patience
Wall Street consensus puts Micron near the top of every buy list, but one model sees something the bulls are missing. Before Q4 results land, here is what the numbers actually say about whether this memory supercycle has already run…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
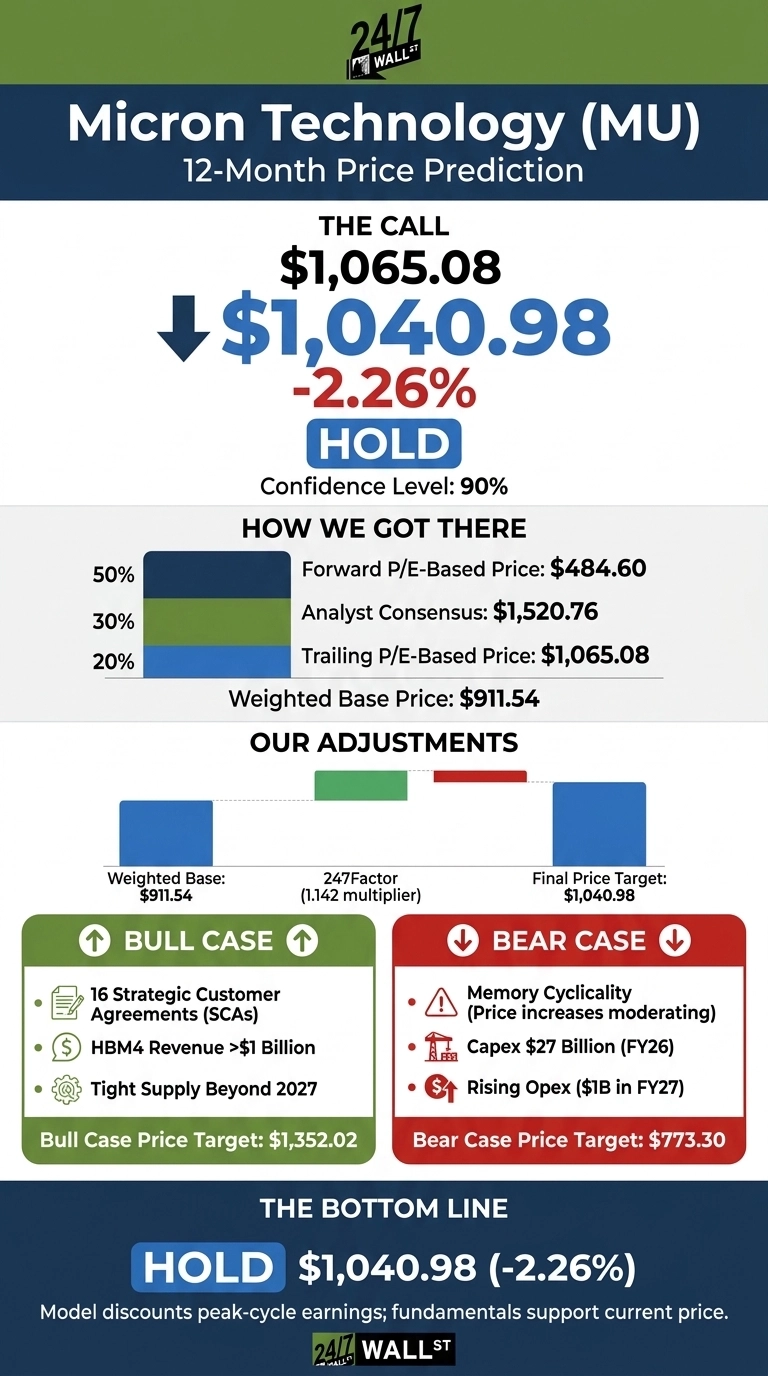
Our 24/7 Wall St. price target for Micron (NASDAQ:MU | MU Price Prediction) is $1,040.98. The model is working from a price of $1,065.08, so the target means -2.26% downside over 12 months. The model rates the stock a hold.
| Metric | Value |
|---|---|
| Current Price | $1,065.08 |
| Price Target from 24/7 Wall St. | $1,040.98 |
| Upside/Downside | -2.26% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Wall Street is far more optimistic. The consensus target is $1,520.76, with 9 Strong Buy, 35 Buy and 4 Hold ratings, zero Sells. The gap comes down to one question: how much of the memory upcycle is already in the price?

Why We Could Be Wrong
Our target stands slightly below where Micron trades. Micron has a strong bull case, having signed 16 Strategic Customer Agreements (SCAs), multi-year supply contracts.
Fourteen carry about $100 billion in revenue at minimum contract prices. Fiscal Q4 guidance calls for record revenue. Either could trigger a rerating.

Micron’s Record Run Meets Fresh AI Jitters Before Q4
The stock is up 276.96% year to date and 15.26% over the past month. A 1.91% pullback last week as AI jitters hit the group ahead of fiscal Q4 results left shares below their 52-week high of $1,254.81.
Fiscal Q3 revenue came in at $41.46 billion, well ahead of the $35.25 billion estimate. Non-GAAP EPS of $25.11 beat the $20.2843 consensus, the seventh consecutive beat. Q4 guidance: $50 billion ± $1 billion revenue and $31 ± $1 non-GAAP EPS.

Why Bulls See $1,352 and Beyond
Most SCAs are take-or-pay deals; customers pay for committed volumes whether or not they take delivery, running through the end of calendar 2030. Management says floor prices support margins “well above our peak quarterly margins in any past cycle.”
HBM4 has shipped more than $1 billion in revenue, with supply expected tight “beyond calendar 2027.” Fiscal 2027 EPS estimates have risen to $156.5298, up from $117.8618 90 days ago. Bull case target: $1,352.02.

What Could Derail Micron’s Memory Supercycle
Memory remains cyclical. Q4 guidance assumes “a meaningful moderation in the rate of price increases.” Fiscal 2027 EPS estimates range from $106.89 to $221.27, showing significant uncertainty. Fiscal 2026 capex expected around $27 billion, with operating expenses rising about $1 billion in fiscal 2027. Bear case target: $773.30.
Micron expects $22 billion in customer deposits and commitments, with $24.4 billion in net cash at Q3 end. It is funding expansion from strength. The $325 million loss on debt prepayments in Q3 was a one-time charge.
Is Micron Cheaper Than NVIDIA and SanDisk?
A fair comparison is NVIDIA (NASDAQ:NVDA), as its AI accelerators drive HBM demand. It trades at 25 times forward earnings versus Micron’s 7. The market pays up for computing and discounts memory.
SanDisk (NASDAQ:SNDK) competes directly in NAND flash. It trades at 8 times forward earnings and 23 times trailing, nearly in line with Micron. The market prices both memory manufacturers for a cyclical peak.
| Company | Forward P/E | Trailing P/E |
|---|---|---|
| Micron | 7 | 24 |
| NVIDIA | 25 | 29 |
| SanDisk | 8 | 23 |
Our target means a P/E of about 24, in line with SanDisk’s trailing multiple. The target looks reasonable compared with these peers.
Hold Steady While Micron Proves the Cycle Has Changed
The 24/7 Wall St. price target is $1,040.98, with a hold rating and 90% confidence. The model discounts peak-cycle earnings heavily.
A Q4 print at or above the $50 billion guide, with SCAs covering half of revenue, would make me constructive. I would stay patient if price increases slow faster than expected. For now, fundamentals support the current price, and Wall Street’s extra upside has to be earned.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.