Prediction: This Tech Giant Could Be Worth Twice as Much by 2030
Meta's ad machine keeps growing, but a massive capex bill just cratered free cash flow and snapped a six-quarter earnings streak. Here is whether the math actually works for doubling the stock price by 2030.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Meta (NASDAQ:META | META Price Prediction | META Price Prediction) runs the biggest ad business in the world, and it is still getting faster. Ad revenue reached $59.36 billion last quarter, up 27%, across 3.60 billion daily users.
The stock trades at $720.16. It is up only 9.37% this year and down 3.53% over 12 months. Can Meta reach $1,500 per share by 2030, about double today’s price? I think there’s a real path.

A $145 Billion Spending Bill Is Holding Meta Back
The problem is spending. Meta guided 2026 capex to $130 billion to $145 billion, and second-quarter free cash flow fell to $784 million from $8.55 billion. EPS of $6.18 missed expectations by 14.42%. That ended a six-quarter run of beats. A Forbes headline summed up the mood: AI overspending fears.
The recent rally is shaky. Shares gained 25.09% over the past month and 8.25% over the past week, then dropped 4.19% today. With a beta of 1.243, Meta tends to swing more than the market. Analysts keep cutting estimates too: 45 downward revisions to 2026 EPS in 30 days, against 4 up.
Wall Street Sees 9.7% Upside. Our Model Says 29.4%
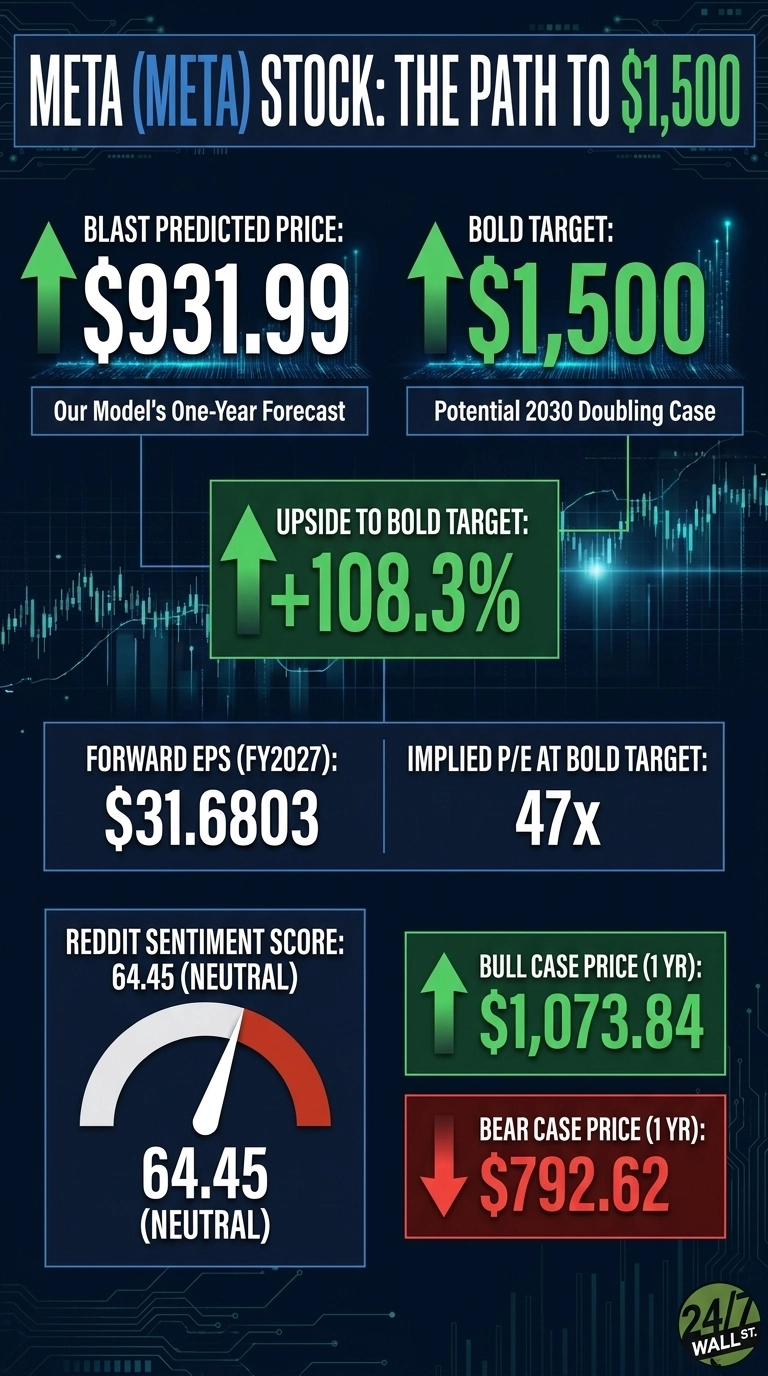
The consensus target is $790.27. That’s 9.7% upside, based on 8 Strong Buys, 47 Buys, 7 Holds and 0 Sells. Our one-year forecast projects $931.99, or 29.4% upside. Bear-case estimates go as low as $792.62 and bull-case estimates as high as $1,073.84, with model confidence high at 0.9.

I think the Street is too cautious. 89% of analysts are bullish, yet their targets just clear the 52-week high. The earnings growth factor (-0.013) shows one-time costs. Strip out legal charges and severance, and operating income would have grown 9%.
Here’s What It Takes for Meta to Reach $1,500
Getting from today’s $720.16 to $1,500 would take a gain of 108.3%. Forward EPS is $31.6803, so $1,500 works out to a forward P/E of 47x. The base case already means 23x. The bold target would need 24x more.
Earnings growth closes that gap. At the consensus growth rate of 19.16%, EPS would reach about $53.60 in three years. At that level, $1,500 is only 28x. Our 2030 bull path reaches $1,560.67 by September of that year.
These catalysts are real. Advantage Plus is running at over $75 billion in annual revenue. More than 1 million businesses use Meta’s business agents every week, and Meta has a BlackRock venture for a one gigawatt data center. Zuckerberg put it this way: “AI is accelerating our core business today, powering our next generation of products, and opening the door to entirely new enterprise opportunities.”
All of that data-center capacity has to be powered, cooled, and connected by somebody, which is why the suppliers behind the hyperscaler expansion keep showing up in our free report on seven AI infrastructure stocks that aren’t chipmakers.
If capex keeps growing faster than revenue, margins could stay pressured for years.
Where Meta Trades Today Versus Its Earnings Power
Meta trades at 23x forward earnings with a PEG ratio of 0.985. That looks cheap for a business growing revenue at over 20%. Shares sit between a 52-week low of $519.37 and a high of $779.82.
Over 10 years, the stock has returned 464.86%. Today’s multiple leaves room for earnings growth to do most of the work.
$1,500 Is a Stretch, But Here’s Why It’s Possible
Reaching $1,500 takes a 108.3% gain. I’d call it a stretch, but a reachable one. Three things need to happen. Ad growth has to stay above 20%.
Business agents and API services have to become real revenue. And capex has to start producing free cash flow again. A long ad slowdown or large legal losses from the youth-related trials could derail it.
We’ve outlined the plan for how Meta could reach $1,500 in 2030, though gains like this shouldn’t be expected every year.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.