Meta Stock Could Be Worth Much More If Its AI Strategy Pays Off
Meta is riding a 25% monthly rally while simultaneously pouring over $130 billion into AI and watching free cash flow crater. Whether that gamble transforms the ad giant into something far more valuable depends on a few critical variables analysts…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
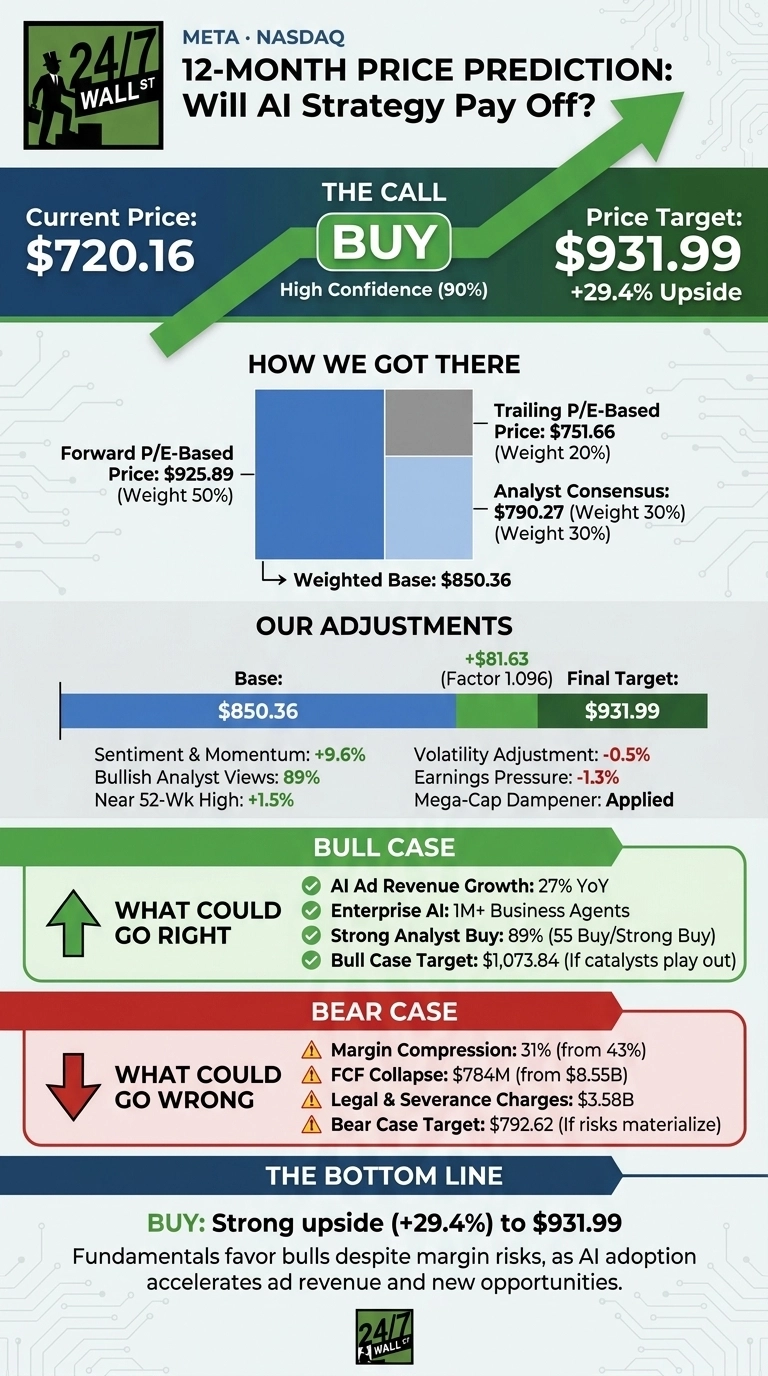
The 24/7 Wall St. price target for Meta (NASDAQ:META | META Price Prediction) is $931.99 over the next 12 months. Measured against today’s intraday price of $720.16, that implies 29.4% upside. The stock gets a buy rating from our model, with high confidence.

| Metric | Value |
|---|---|
| Current Price | $720.16 |
| Price Target from 24/7 Wall St. | $931.99 |
| Upside/Downside | 29.4% |
| Recommendation | BUY |
| Confidence Level | 90% |
The model set this target from Friday’s close of $751.66. The key question is whether a $130-$145B 2026 capex plan will generate returns large enough to justify margin pressure.
A 25% Monthly Rally Meets Fresh Overspending Fears
Meta is up 25.09% over the past month and 9.37% year to date. Today it fell 4.19% following AI overspending concerns. The 52-week range runs from $519.37 to $779.82.
Q2 revenue of $60.80B rose 28% and beat the $60.29B consensus. EPS came in at $6.18, missing the $7.22 estimate.

Why Bulls See $1,000+ Ahead
AI gains already show in the ad business. Advantage Plus runs at over $75 billion per year. AI raised ad clicks 8.3% and Facebook conversions 15.7%. More than 1 million businesses use Meta’s business agents weekly. Daily Meta AI interaction is up 60%. Management says it received computing power offers at “a significant premium over what we paid for it.”
Analysts are heavily bullish: 55 Buy or Strong Buy ratings, 7 Holds, no Sells. Consensus target is $790.27. If the bull case plays out, our model points to $1,073.84.

Margin and Cash Flow Risks Investors Cannot Ignore
Operating margin fell to 31% from 43%. Free cash flow dropped to $784M from $8.55B. Reality Labs lost $4.03B in Q1. Q2 included $2.40B in legal charges and $1.18B in severance. Without those, operating income would have grown 9%. Our bear case is $792.62.
Is Meta Cheaper Than Alphabet and Pinterest?
| Company | P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Meta | 27 | 28% |
| Alphabet | 15 | 24% |
| N/A (GAAP loss) | 18% |
Competing for ad budgets and AI leadership, Alphabet (NASDAQ:GOOGL) remains a key rival. Its P/E of 15 looks low, but a $99.03 billion equity gain inflated earnings. Free cash flow turned negative at -$5.855 billion. Meta’s operating margin of 41.4% tops Alphabet’s 32%, supporting Meta’s premium multiple.
Pinterest (NYSE:PINS) is a pure social-ad comparison. Revenue grew 18.2%, while the company posted a GAAP operating loss of $55.2 million. Meta grows faster at far greater scale. Against both peers, our 24/7 Wall St. price target looks reasonable.
Meta Price Prediction 2026-2030
The 24/7 Wall St. price target of $931.99 has a buy rating and 90% confidence. The scale tips toward bulls on 27% ad revenue growth funding the expansion.
Shares look compelling if ad conversion gains continue and enterprise AI generates revenue. Caution advised if free cash flow remains near zero into 2027. Fundamentals favor the bulls.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $789.91 |
| 2027 | $922.85 |
| 2028 | $1,108.43 |
| 2029 | $1,225.44 |
| 2030 | $1,325.18 |
The projections rest on Meta continuing to execute its current strategy. Actual results could land well above or below these levels depending on how enterprise AI revenue develops, how the youth-related trials turn out and how capex returns hold up.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.