Broadcom, Marvell, and SanDisk Are Quietly Building Toward a Massive Bull Run
Broadcom's AI revenue exploded 221% last quarter yet the stock sits nearly flat for the year, while Marvell and SanDisk have already handed investors life-changing gains. Here is whether all three can push even further into record territory by 2027.

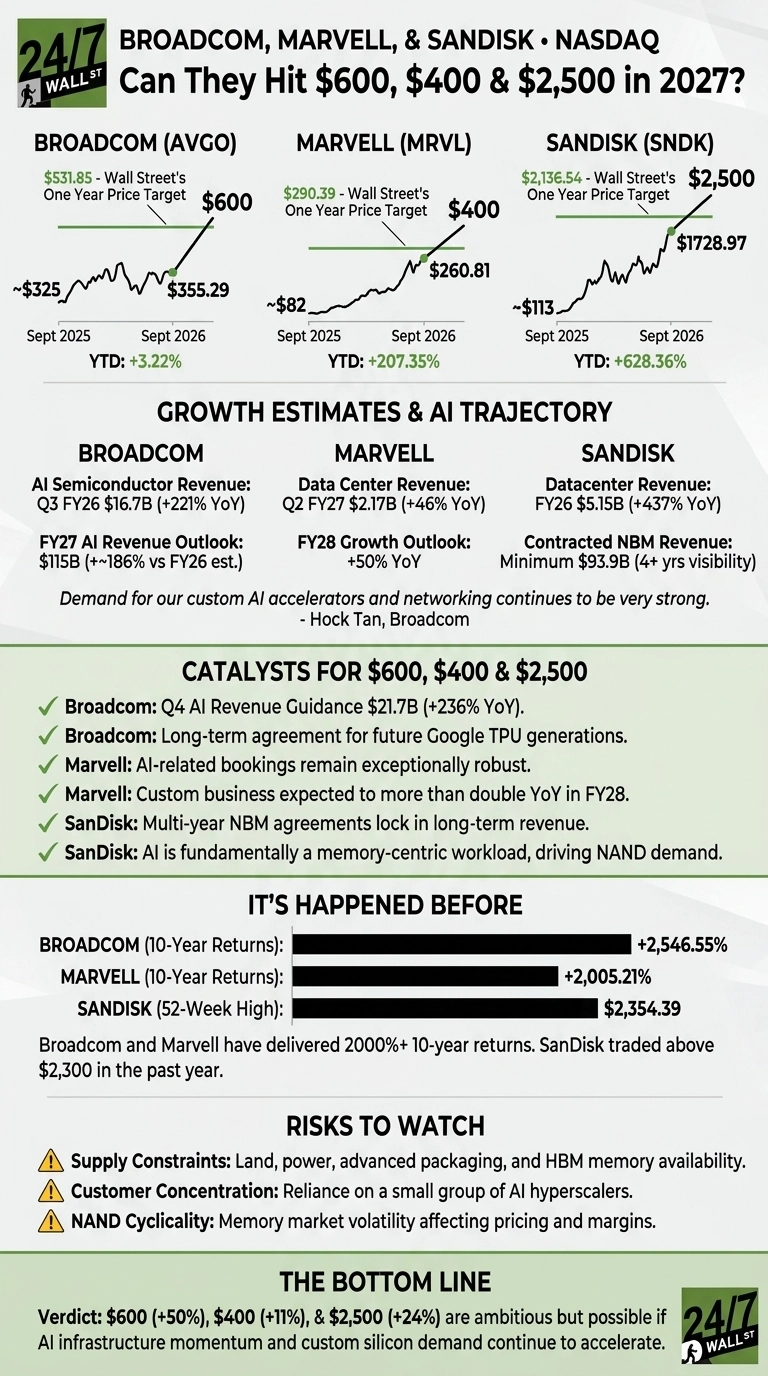
Three suppliers of AI infrastructure head into 2027 with very different charts. Broadcom (NASDAQ:AVGO | AVGO Price Prediction) is up only 3.22% year-to-date, even though its AI semiconductor revenue rose 221% to $16.7 billion last quarter.
Marvell (NASDAQ:MRVL) has gained 207.35% this year, and SanDisk (NASDAQ:SNDK) has jumped 628.36%. AI chip stocks pulled back in late September, including SanDisk and Marvell (Barron’s), which gives investors a fresh starting point.
Here is how these stocks could reach $600, $400 and $2,500 in 2027.
Wall Street Already Sees Room to Run
Consensus targets are $531.85 for Broadcom, $290.39 for Marvell and $2,136.54 for SanDisk. From today’s prices, that points to upside of 50%, 11% and 24%. None of the three has a single Sell rating in the Broadcom or Marvell coverage (45 Buy-or-better ratings on Broadcom).
Broadcom’s $600 Case Is Built on Custom Chips
Hock Tan was blunt on the call: “Q3 demand was simply hot and we’re just getting started.” Management expects AI revenue of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028. Tan also said Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.”

At $355.29, shares trade at about 12x that fiscal 2028 figure. At $600, the multiple would be 20x, a reasonable price for a company with nine straight earnings beats. Catalysts include:
- Guidance for Q4 AI revenue of $21.7 billion, up 236%
- A long-term agreement with Google to supply future TPU generations
- Production shipments of OpenAI’s first custom accelerator

Marvell Has a Realistic Route to $400
Marvell’s CEO said “AI-related bookings remain exceptionally robust.” Management raised its fiscal 2028 growth outlook to about 50%. The fiscal 2028 EPS consensus has risen to $6.7609, up from $6.1726 90 days ago. Shares trade at 39x that estimate.
A $400 price would mean 59x, which is a premium multiple that only works if the custom business more than doubles as forecast. The next catalyst is the October 6 Investor Day, where management promised detail on custom revenue through the end of the decade.

SanDisk’s Contracts Support a $2,500 Price
David Goeckeler called the latest quarter “a fundamental inflection point.” SanDisk’s multi-year customer agreements lock in at least $93.9 billion of revenue at floor pricing. EPS came in at $39.25, beating estimates for the fifth consecutive quarter, and Q1 guidance calls for $44 to $46.
If you annualize the low end of that range, shares trade near 10x earnings. At $2,500, they would trade at about 14x. SanDisk also has a $15.5 billion buyback authorization.

These Stocks Have Delivered Big Gains Before
The targets require increases of 69% for Broadcom, 53% for Marvell and 45% for SanDisk.
Broadcom has returned 2,546.55% over ten years, and Marvell has returned 2,005.21%. SanDisk traded as high as $2,354.39 within the past year.
Bottom Line on $600, $400 and $2,500
Each stock needs a strong 2027 to reach that level. The main risks are supply constraints, customer concentration and NAND cyclicality. Still, rising estimates, contracted demand and a history of earnings beats give all three real momentum.
The signs that showed up early in the last generation of monster semiconductor winners are the ones we cataloged in a free playbook here. Such returns shouldn’t be expected every year, but this is the pattern for how Broadcom, Marvell and SanDisk could post outsized increases in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.