Buy Nvidia Today Because It’s Likely To Be Worth A Lot More In 2 Year’s Time
NVIDIA's revenue more than doubled last quarter, analysts see 42% upside ahead, and the bear case still sits above today's price. What stands between shareholders and those gains is a supply bottleneck that management admits will not clear for at…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
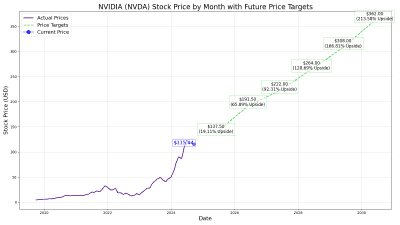
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) trades at $230.86, and the two-year outlook is built on management’s own growth forecast, which is limited by supply. Shares sit just below their 52-week high of $236.0 after a quarter in which revenue more than doubled.
NVIDIA designs the GPUs, CPUs, networking gear and software that run most AI data centers. Last quarter, Data Center revenue hit $89.023 billion, up 117% year over year, out of total revenue of $96.221 billion. That beat consensus for the fifth consecutive quarter.
Supply Caps Growth at 70%, and Shares Trade at 15x Next Year’s Earnings
Management expects revenue to grow “approximately 70% in fiscal 2028”. It also said “customers’ forecasts point to our growth doubling next year.” Fiscal 2028 consensus EPS of $15.6826 puts the stock at roughly 15x forward earnings. That estimate has climbed from $12.6737 over 90 days, with 42 upward revisions and none down in the last month.
Vera Rubin raises NVIDIA’s revenue opportunity to $40 billion per gigawatt, versus $25 billion with Blackwell. On top of that, AWS is adding an additional 2 million GPUs, and CPU revenue is expected to “more than double in fiscal 28.”
Circular Financing and Memory Inflation Could Cap Returns
NVIDIA has invested “nearly $50 billion in the Frontier AI Labs,” and demand it supports through its own balance sheet should make up “roughly a quarter of our business next year.” Supply commitments have reached $279.0B, and guarantee obligations are limited at $108.5B. Days sales outstanding stretched to 60 days from 45.
Memory costs are also climbing. Management expects gross margins to bottom at 71% to 72%. The outlook includes no China data center compute revenue, and a beta of 2.217 means any decline in AI spending would hit the stock hard.
Execution Decides Whether the Supply Gap Closes
Demand looks secure. The open question is supply, which management expects to stay a bottleneck “at least through the end of fiscal year 28.” The constraints include power, memory, foundry capacity and labor. Third-quarter guidance of $108.0B ±2% and Vera Rubin reaching about 20% of data center revenue are the next tests. Hitting both would support the growth outlook. Margins sliding below guidance would hurt it.
Analysts See 42% Upside as Shares Beat the S&P 500
The average analyst target of $327.7 implies 41.9% upside across 61 analysts. Price targets are opinions, though, and carry no guarantee. The stock trades at 29 times trailing earnings and 25 times forward earnings.
- Strong Buy: 10
- Buy: 48
- Hold: 2
- Sell: 1
NVIDIA is up 24.08% year to date, compared with 12.04% for the S&P 500. Over one year, it has gained 23.59%, compared with 14.3% for the index.
What Could Drive NVIDIA Over the Next Two Years
At $230.86, the two-year outlook rests on earnings growth and product drivers.
Consensus calls for fiscal 2028 EPS to rise about 68.5% from fiscal 2027 levels. If the multiple stays flat, the share price would track that earnings growth. One valuation model puts its two-year base case at $305.54 and its bear case at $234.62. Even that bear case sits above the current price.
The biggest drivers are the Vera Rubin ramp, which management calls “the fastest product ramp in NVIDIA’s history,” and recurring revenue-sharing deals with neoclouds. Buybacks help too: $99.0B of repurchase authorization remains.
Three things would break the thesis: AI labs struggling to finance their commitments, margins falling below the guided floor, or hyperscalers cutting capex. Investors should keep an eye on revenue revisions and inventory each quarter. The flip side of that capex, where it all gets spent after the GPUs, is the subject of a free report on seven suppliers driving the expansion, here.
A valuation of about 15x next year’s earnings for a company whose growth is limited by supply is the central factor in NVIDIA’s two-year outlook.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.