SpaceX Just Upped The Ante On Rocket Lab
Starship reaching orbit scrambles the economics for every rocket startup, and Rocket Lab and Redwire are betting on opposite strategies to survive the fallout. Only one of those bets looks smart right now.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

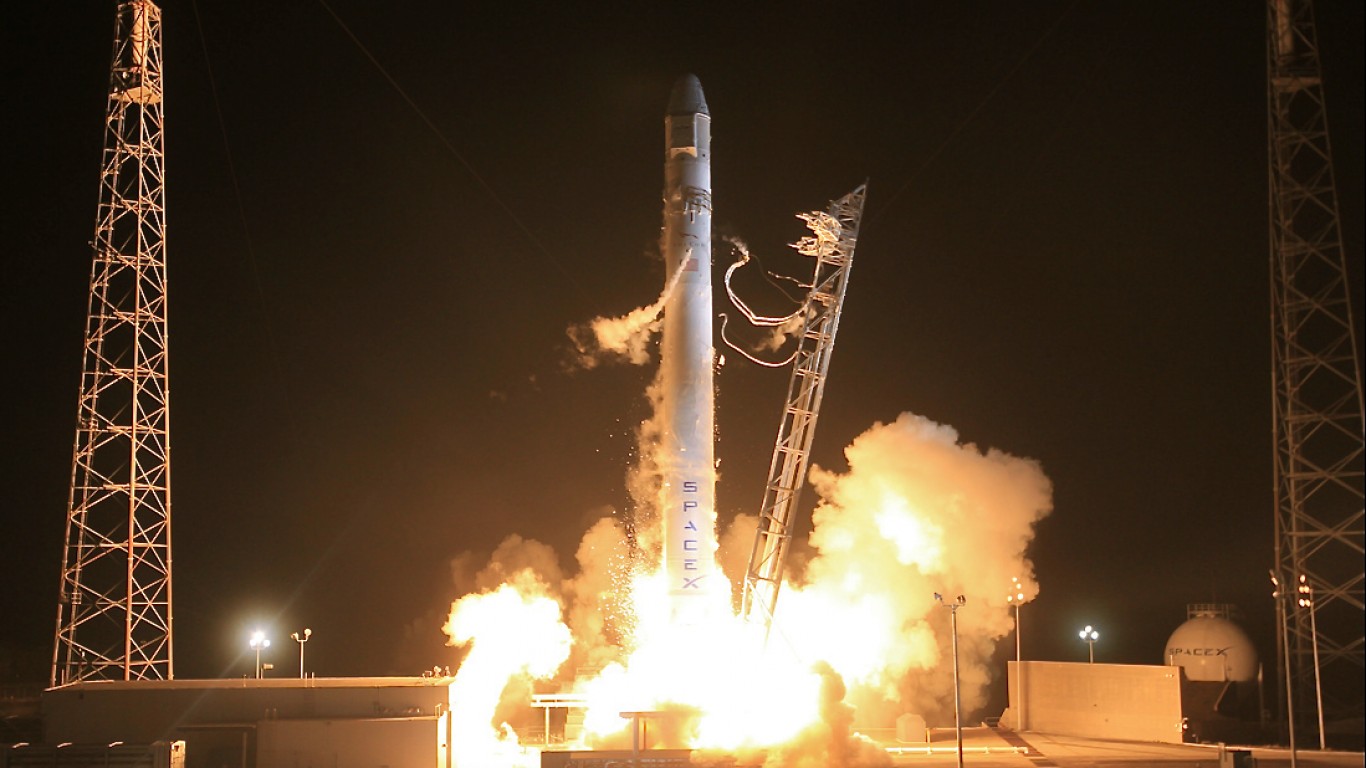
Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) and Redwire (NYSE:RDW) posted record second quarters in August on Pentagon demand. Now SpaceX’s Starship has reached orbit, changing the competitive landscape. Rocket Lab is building a rival rocket; Redwire is buying rides from SpaceX. That split matters.
Rocket Lab Builds the Rival. Redwire Buys the Ride.
Rocket Lab’s revenue rose 62% to $234.07 million, with backlog reaching $2.36 billion. Space Systems brought in $189.5 million versus $44.6 million from launch. CEO Sir Peter Beck: “The most successful space companies will be the ones that have the keys to space.”
Redwire grew faster. Revenue rose 89.6% to $117.07 million. Edge Autonomy’s Stalker and Penguin drones raised Defense Tech revenue to $61.88 million, which put it ahead of the Space division. A book-to-bill ratio of 1.42 means new orders are still coming in faster than Redwire delivers. Its venture SpaceMD also bought an entire SpaceX Starfall spacecraft for a 2028 microgravity mission. CEO Peter Cannito called it “a game changer.”
| Business Driver | Rocket Lab | Redwire |
|---|---|---|
| Main Growth Engine | Flatellite and GEO satellites | Stalker and Penguin drones |
| SpaceX Relationship | Competitor via Neutron | Customer via Starfall |
| Backlog | $2.36 billion | $542.1 million |
Starship Puts a Target on Neutron’s Price Tag
Starship is a real threat to Neutron’s pricing. Launching on Falcon 9 already costs about $2,700 a kilogram. As SpaceX gets better at reuse, repairing a rocket could cost roughly 1/100th of building a new one. Rocket Lab prices Neutron at an average of $50 to 55 million per launch, and CFO Adam Spice sees “more upside to ASPs.” I doubt that holds if Starship’s launch pace keeps climbing. Beck says that “launch has never been so constrained,” but Neutron still has to fly, and he admitted that “the window for an end-of-year launch is narrowing.”
Rocket Lab is valued at 57.93 times sales, compared with Redwire’s 6.12. That gap assumes Neutron comes through. Rocket Lab shares sit at $70.46, up just 1% this year and far below their 52-week high of $151. That’s despite a rise today on a record Electron launch deal and a Citi buy rating. Redwire, at $10.58, is up 39.21% this year as drone orders keep building.
Neutron’s Stage Test Could Reset Both Stocks
I’m watching Neutron’s stage testing, which Beck called the last major step before first flight. I’m also tracking Rocket Lab’s Q3 revenue guidance of $250 million to $265 million. For Redwire, keep an eye on gross margin. Management still guides to the “low to mid-20s”, even though Q2 came in at 27.8%.
Why I Lean Toward Redwire While Starship Scales
Redwire fits this moment better. Cheaper launch helps a company buying rides, and its drones sell into NATO demand independent of rocket costs. A quarterly loss of $40.97 million warrants caution.
Rocket Lab is the stronger business with $2.13 billion in cash and an Iridium deal closing in mid-2027. If Neutron flies successfully, I would rethink quickly. Until then, its valuation leaves little room for a Starship price war.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.