Synopsys Is the Nasdaq 100’s Top Stock Today. The Target Says It’s Not Done
Synopsys just surged to lead the Nasdaq 100 after a blockbuster Investor Day packed with OpenAI partnerships, Amazon deals, and a raised earnings outlook. Whether this rally has real staying power or faces serious headwinds comes down to one glaring…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
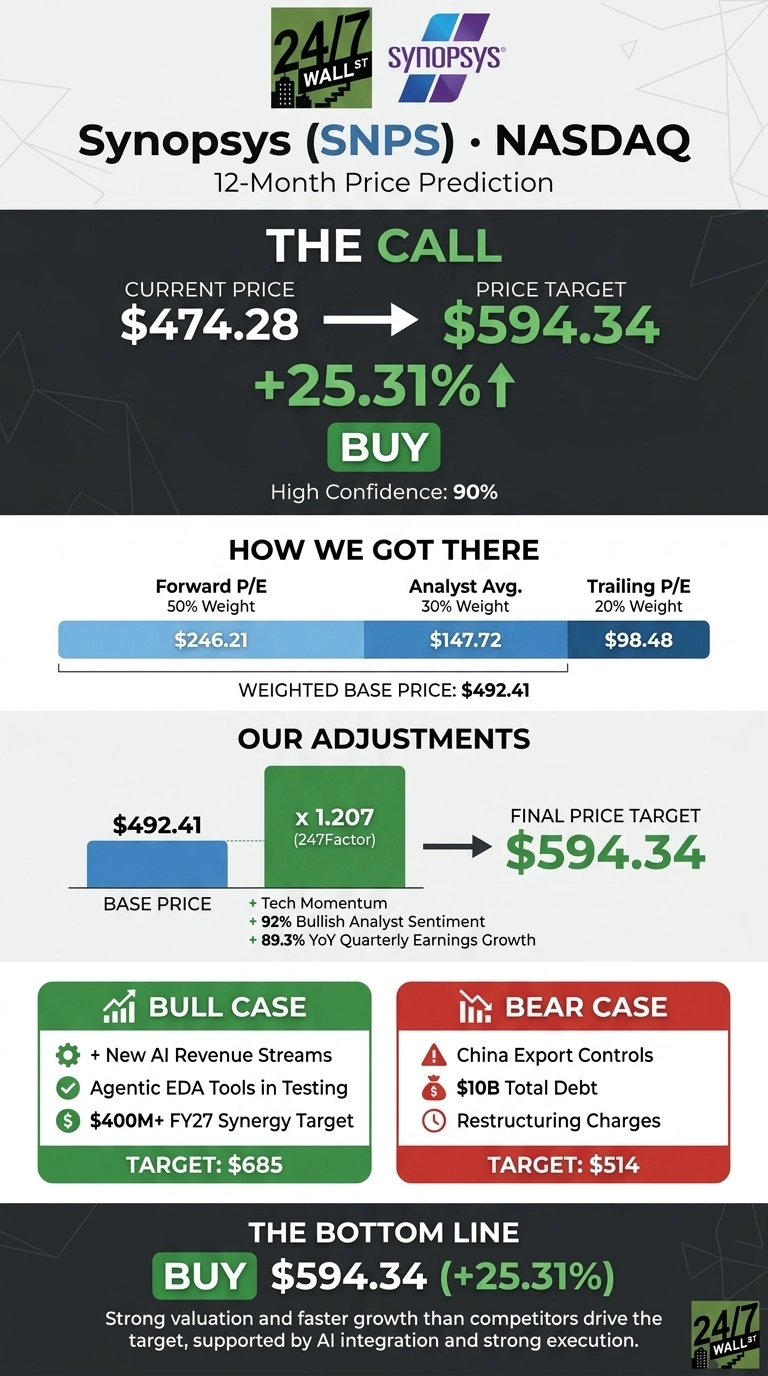
Synopsys (NASDAQ:SNPS | SNPS Price Prediction) is the top performer in the NASDAQ 100 today. The stock is up 8.8% to about $474.28 following a busy Investor Day. The 24/7 Wall St. price target of $594.34 means 25.31% upside over the next 12 months.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $474.28 |
| The Price Target from 24/7 Wall St. | $594.34 |
| Upside | 25.31% |
| Model Rating | BUY |
| Confidence Level | 90% |

A 90% confidence reading is high for our model. The chip-design software leader has spent a year integrating Ansys, and AI is driving chip complexity to new levels.
OpenAI and Amazon Deals Ignite a 14% Weekly Rally
Synopsys has gained 14.56% over the past week. On September 30, Synopsys announced GPT-Synopsys with OpenAI and a multi-year IP agreement for custom silicon with Amazon (NASDAQ:AMZN), alongside a long-term financial model at its Investor Day.
Fundamentals back up the rally: fiscal Q3 revenue came in at $2.48B, ahead of the $2.44B estimate and up 42.4% year over year. Non-GAAP EPS of $3.91 exceeded expectations of $3.67. Management also raised full-year EPS guidance to $15.04 to $15.10.
Why Bulls See $685 Within Reach
The bull case of $685.40 depends on new AI revenue streams. Management said 20 customers were testing agentic EDA tools with “subscription plus consumption” pricing. Revenue synergies from combined Synopsys and Ansys technology are expected in FY27, with a $400 million revenue synergy target.
Analysts expect FY2027 EPS of $17.6932, with the high estimate at $20.0054. Of the 23 analysts covering the stock, none rate it Sell, and their consensus target is $553.77.

What Could Pull Synopsys Toward $514
Our bear case is $513.93. Main risks include export controls tied to China, total debt of about $10 billion, and restructuring charges planned for Q4. At roughly 76x trailing earnings, GAAP results look expensive, though Ansys amortization and integration costs drag down GAAP profit.
On a forward basis, the stock trades at 23x. Synopsys paid off $3.45B of debt in Q1 and expects free cash flow of about $2.6B this year.
Synopsys Trades Cheaper Than Its Closest Rival Despite Faster Growth
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Synopsys | 23 | 42.4% |
| Cadence Design Systems (NASDAQ:CDNS) | 32 | 24.2% |
| Keysight Technologies (NYSE:KEYS) | 22 | 36.5% |
Cadence trades at roughly 32x forward earnings while growing revenue 24.2%. Synopsys is growing faster at a lower multiple, suggesting our target is reasonable and somewhat conservative.
Synopsys Still Has Room to Run
Our 24/7 Wall St. price target of $594.34 carries a buy rating at 90% confidence. The deciding factor is the valuation gap: faster growth than Cadence at a lower multiple.
The numbers point higher if Design IP rebounds and agentic pricing shows up in FY27 guidance.

| Year | The Price Target from 24/7 Wall St. |
|---|---|
| 2026 (12-month target, October 2027) | $594.34 |
| 2027 (January 2028) | $615.70 |
| 2028 (January 2029) | $701.22 |
| 2029 (January 2030) | $810.11 |
| 2030 (October 2031) | $921.01 |
Synopsys needs to execute on its silicon-to-systems strategy for these projections to hold. Faster agentic AI adoption could driving results higher; export restrictions could driving them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.