National Economic Advisor Says Trump ‘Won’t Inflate Our Way Out of Debt.’ Trump Says, Yes We Will.
Trump told Time that inflation will pay off the national debt very rapidly, while his own chief economic advisor flatly denied it. Bond markets are already placing their bet on which man is telling the truth, and homeowners and borrowers…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
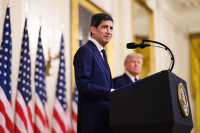
Kevin Hassett answered simply. Bloomberg’s Open Interest asked whether the White House planned to “inflate our way out of debt.” He replied, “No, absolutely not.”
President Trump gave a different answer. In a Time magazine interview published October 1, he said, “Certain levels of inflation will also pay off that debt very rapidly. Very rapidly.” He also argued that higher interest rates were hurting the country more than inflation.
When the president and his top economic aide disagree about what the dollar will be worth, bondholders decide which one to believe. Right now they are pricing as if the president means it.
What Lenders Are Charging Washington Right Now
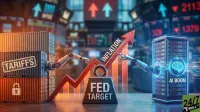
The 10-year Treasury yield stood at 5.24% on October 1, up from 4.13% a year earlier. That is a rise of 1.11 percentage points. The Federal Reserve raised its target range to an upper bound of 4.00% on September 17. Back in August, the 30-year yield hit a nearly 20-year high. The Treasury responded by doubling its buybacks of longer-term bonds from $2 billion to $4 billion. At that point, the national debt passed $40 trillion.
The 10-year TIPS yield was 2.88% on October 1. Subtract that from the regular 10-year yield and the market’s inflation forecast for the decade is about 2.36% a year. Investors expect inflation only slightly above the Fed’s 2% target, yet demand nearly 3% after inflation to lend to Washington. That premium reflects the risk of the president’s stated policy.
Why Inflating Away a $40 Trillion Debt Backfires
Inflation reduces debt only when the government owes long-term, fixed-rate bonds to lenders who didn’t expect the inflation. Most federal debt is short-term and rolls over repeatedly, locking in today’s higher rates. Inflation also raises government spending: Social Security cost-of-living adjustments, federal wages, and purchases all rise with the Consumer Price Index.
That index rose 0.4% in August alone. “People who lend us money in the Treasury bond market expect compensation for inflation,” KPMG chief economist Diane Swonk told Marketplace. “They don’t want their future purchasing power and the dollars they lend us to be diminished.”
How Washington’s Debt Raises Your Borrowing Costs
Households pay the cost. The 10-year yield sets mortgage rates. Swonk said, “The cost of our debt is pushing up interest rates on everything from auto loans to buying a new home.” Companies paying more to borrow have less ability to pay raises, leaving families paying more for loans while paychecks lag prices.
Treasury efforts to calm markets have had little effect. One strategist told Marketplace in September that the interventions in currency, commodity and bond markets had worked “not terribly” because yields kept climbing.
One Gap Shows Which Answer Markets Believe
The key measure is the gap between the regular 10-year yield and the TIPS yield. If that gap grows well above 2.36% while real yields stay near 3%, investors are pricing in the president’s inflation and pricing it in at the same time. That is the worst outcome for anyone with a variable-rate loan or a mortgage application. The September Consumer Price Index report and the Fed’s next decision will show whether Hassett’s “absolutely not” or Trump’s “very rapidly” is actually setting the price of money.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.