Pfizer’s Turnaround Could Be Bigger Than Investors Think, Set For 20% Upside
Ten consecutive earnings beats and a shrinking COVID hangover have Wall Street split on whether Pfizer deserves a breakout or a ceiling, and the answer hinges on a single pipeline deal that could reshape the obesity drug race.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
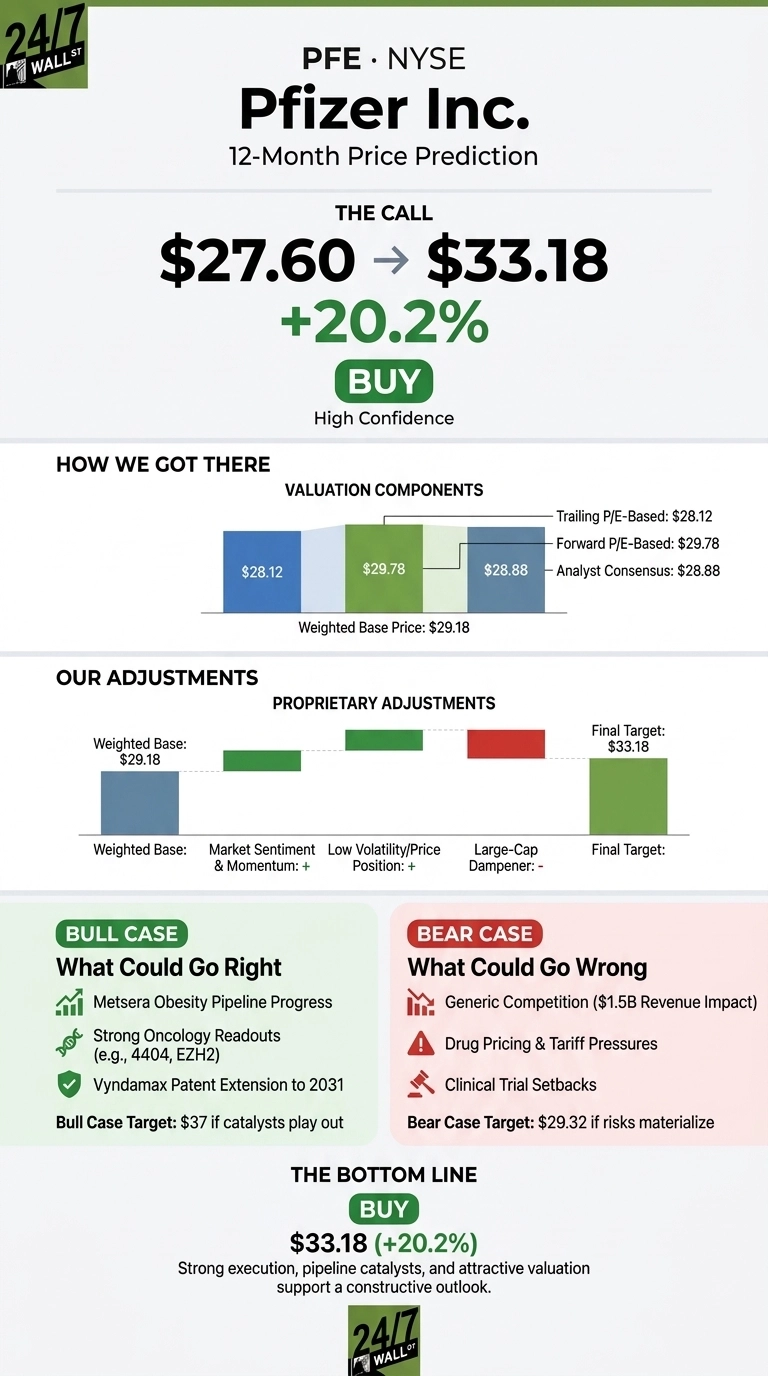
Our 24/7 Wall St. price target for Pfizer (NYSE:PFE | PFE Price Prediction) is $33.18 over the next 12 months. From today’s $27.60 share price, that implies about 20.2% upside. Our model rates the stock a buy, and its confidence is high.
| Metric | Value |
|---|---|
| Current Price | $27.60 |
| Price Target from 24/7 Wall St. | $33.18 |
| Upside/Downside | 20.2% |
| Recommendation | BUY |
| Confidence Level | 90% |
The COVID drag is getting smaller, and the rest of the portfolio keeps growing. In the second quarter, launched and acquired products grew 18% operationally. With the stock at 10 times forward earnings and a $1.72 annual dividend, shareholders collect income while the obesity and oncology pipeline grows.

Ten Straight EPS Beats Have Lifted Pfizer 16.6% in 2026
Pfizer is up 16.6% year to date and 8.58% over the past year. Over the last month it has slid 3.33%, including 2.85% this week. Shares sit about 5.5% below the $29.21 52-week high and around 22.3% above the $22.57 low.
Second-quarter revenue came in at $15 billion, and adjusted EPS of 77 cents beat expectations. That makes all ten of the past ten quarters ahead of consensus. Stripping out COVID products, revenue grew 5% operationally.
Management raised the 2026 revenue center by $500 million even after cutting COVID expectations to about $4 billion. The FDA also expanded Padcev into muscle-invasive bladder cancer, where Phase 3 data showed a 35% reduction in the risk of death.

Why Bulls See $37 Within Reach
Obesity is the biggest swing factor. The Metsera deal gives Pfizer a shot at the first monthly GLP-1 peptide in a market management sizes at $150 billion. Phase 2b data showed placebo-corrected weight loss of up to 12.3%, and Pfizer is aiming a first approval in 2028.
In oncology, the PD-1 x VEGF bispecific 4404 posted a confirmed response rate of about 68%, and the first EZH2 prostate readout is expected in the fourth quarter.
The Vyndamax settlement also extends U.S. exclusivity to June 2031, and cost programs aiming around $9.7 billion in savings through 2029. If these pieces come together, our bull scenario hits $37.

What Could Keep Pfizer Stuck Near $29
Analysts remain conservative, with 16 Holds versus 10 Buy ratings. Generic competition will strip about $1.5 billion from 2026 revenue. Most-Favored-Nation pricing discounts average 50%, and tariffs remain a risk. A lung cancer study missed overall survival. In the bear case, the stock hits only $29.32.

One-time items explain some of the weak GAAP numbers: the second-quarter reported loss of 4 cents per share included a $650 million in-process R&D charge from the InnoVent deal. Adjusted R&D rose 12% operationally, mostly to fund oncology and obesity programs.
Pfizer Trades Below Merck and Close to Bristol Myers Squibb
Merck (NYSE:MRK) partners Keytruda with Padcev in bladder cancer and trades at 15x forward earnings with a lower dividend yield.
Bristol Myers Squibb (NYSE:BMY) shares Eliquis with Pfizer and trades at 9x forward earnings.
| Company | Forward P/E | Dividend Yield |
|---|---|---|
| Pfizer | 10x | 6.03% |
| Merck | 15x | 2.28% |
| Bristol Myers Squibb | 9x | 4.02% |
At our target, Pfizer would trade at about 11x forward earnings. That is still well below Merck’s multiple, so the peer group makes our target look reasonable, if anything conservative.
Our Model Says Buy, and the Dividend Adds Income Along the Way
I’m staying with the 24/7 Wall St. price target of $33.18, a buy rating and 90% confidence. What tips the scale is a single-digit multiple on a business that keeps beating estimates.
I’d view Pfizer as attractive if Metsera’s Phase 3 program stays on schedule and the non-COVID business keeps growing. I’d turn more conservative if pricing reform or tariffs start cutting into the 2026 guidance. For now, the valuation and dividend support our model’s outlook.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $29.14 |
| 2027 | $33.22 |
| 2028 | $37.26 |
| 2029 | $40.98 |
| 2030 | $44.30 |
These projections assume Pfizer delivers on management’s goal of returning to growth from 2029 onward. Obesity trial results and drug pricing policy could drove the stock well above or below these figures.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.