5 Historically Cheap High-Yield Dividend Stocks Ripe for Income Seekers
Some dividend stocks yield more today than at any point in their recent history, yet the payouts remain fully covered. Five names have quietly slipped into that rare window where a historically cheap price and a protected income check arrive…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

A high yield only helps your income if you aren’t overpaying for it and the payout can survive a close look. Each of the five names below passes a fairly simple test against its own record: today’s yield, or today’s earnings multiple, is at or near the best level in the stock’s recent history, and payout coverage still protects the check. The clearest case is VICI Properties (NYSE:VICI), whose forward yield of 8.05% is higher than at any of its previous five September closes. Here is how each one measures up, with dividend safety checked first.
VICI Properties: An Ultra-High Yield Below Book Value
VICI is the only ultra-high-yield name in this group. Shares trade at $22.86, down 25.05% over the past year. The forward dividend of $1.84 now yields 8.05%. Run the same math at each September close from 2021 through 2025 and you get yields between 5.07% and 5.70%. The stock also trades at 0.895 times book value and a forward P/E of 8.
On safety, management guides 2026 AFFO to $2.45 to $2.47 per share, so the forward payout uses about 74.8% of the center. Occupancy is 100%, the weighted average lease term is 39.6 years, and VICI holds investment-grade ratings from S&P, Fitch and Moody’s. The quarterly dividend has climbed from $0.16 in 2018 to $0.46, and the record shows no cuts. Second-quarter GAAP EPS of $0.48 missed expectations because of a $271.1 million non-cash credit-loss charge, while AFFO per share rose 4.6%.
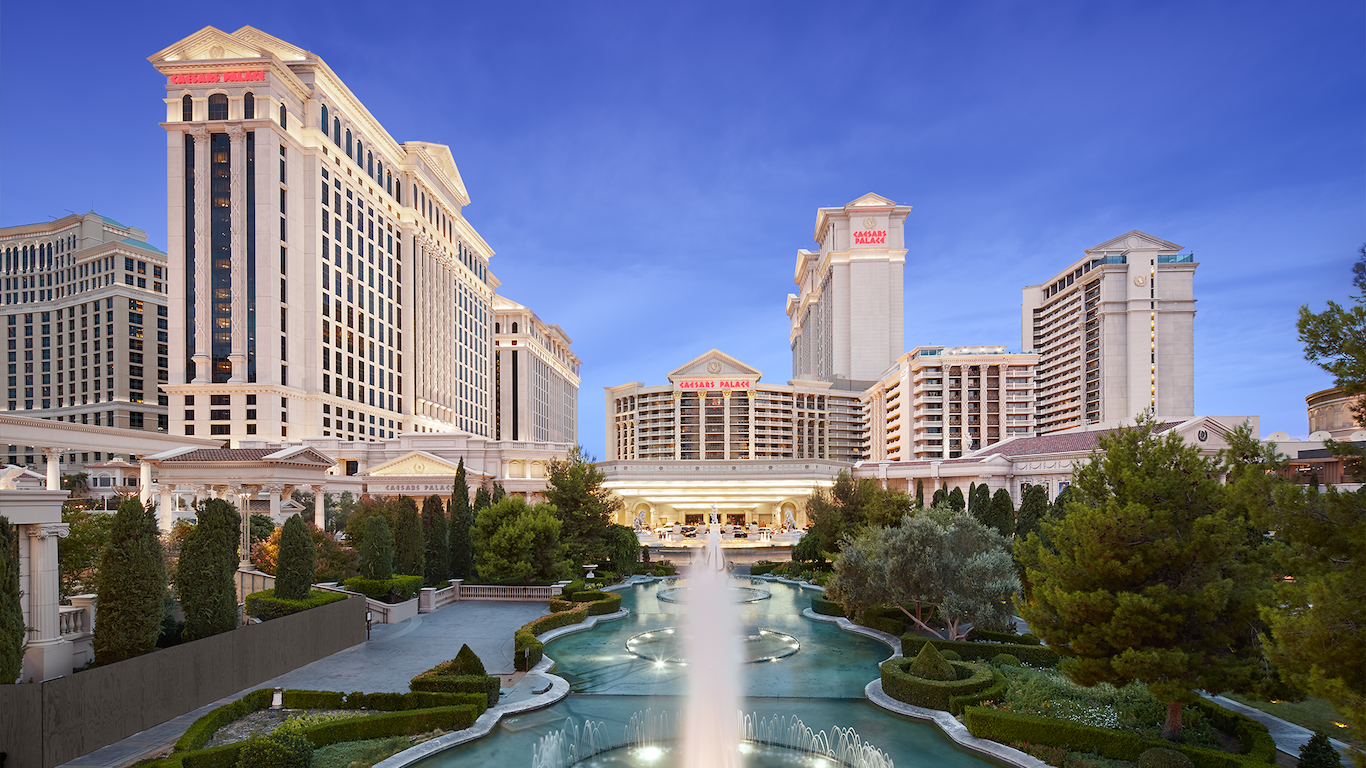
Built-in growth supports the thesis: most leases carry 2.0% annual increases with CPI-linked boosts, and the tenant roster grew to 16 after the company added Clairvest, Golden Entertainment and Club Med. One catch: Caesars supplies 38% of rent and MGM 32%, so most of the income depends on two casino operators.
Realty Income: A Monthly Payer Sitting Near Its 52-Week Low
Realty Income (NYSE:O) fell 11.03% over the past month to $54.22. That’s close to its 52-week low of $53.28 and well under its 200-day average of $61.82. The forward dividend of $3.258 yields 6.01%. At each October close from 2021 through 2025, the yield ran from 3.96% to 6.48%, and only the 2023 low paid more per dollar invested than today’s price. The stock trades at 13.17 times free cash flow, a 7.59% free cash flow yield.
Coverage is solid. With 2026 AFFO guidance raised to $4.44 to $4.45 per share, the dividend uses about 73.3% of AFFO. Fitch rates the company A with a stable outlook, net debt to EBITDAre is 5.4x, and occupancy is 98.8%. Realty Income has paid a dividend every month since at least January 1999, and the latest monthly payment rose to $0.2715 from $0.271.
For income investors, the appeal is scale: 2026 investment volume guidance rose to $10 billion at a 7.3% initial cash yield, and re-leased properties retained 102.7% of prior rent. One catch: only 34.3% of rent comes from investment-grade clients, and second-quarter results included $54.2 million of impairment charges.
NNN REIT: A Fresh Dividend Raise on a Marked-Down Stock
NNN REIT (NYSE:NNN) closed at $40.68, down from $45.20 at the end of August and below its 200-day average of $44.21. After a quarterly raise to $0.62 from $0.60, the forward payout of $2.48 yields 6.10%. At each September close from 2021 through 2025, the yield ran from 4.78% to 6.40%, and only 2023 offered more.
NNN has the most conservative payout of the four REITs here. Full-year AFFO guidance of $3.55 to $3.59 per share puts the dividend at about 69.5% of the center. Occupancy improved to 99.1% across 3,774 properties, with a 10.1-year average remaining lease term. The quarterly dividend has grown from $0.31 in 1999 to today’s level, and second-quarter AFFO per share rose 5.9%.
Management raised acquisition guidance to $700 million to $800 million and closed second-quarter deals at a 7.3% initial cash cap rate with a 17.9-year lease term. One catch: much of the rent comes from consumer-sensitive tenants, including automotive service at 18.6% of rent, restaurants at 14.0% and entertainment at 7.3%.
T. Rowe Price: A 5% Yield at a Lower Multiple Than Any Year-End Since 2018
T. Rowe Price (NASDAQ:TROW | TROW Price Prediction) trades at $103.74, 32.93% below its price five years ago, even with assets under management at a record $1.89 trillion. On trailing adjusted EPS of $10.34, the stock trades at 10 times earnings. At each year-end from 2018 through 2025, that multiple ran from 11 to 16. The forward dividend of $5.20 yields 5.01%.
This dividend has the largest margin in the group, using about 50.3% of trailing adjusted EPS. First-quarter operating cash flow rose 52.7% to $966.3 million, and buybacks have exceeded $497 million year to date on top of the dividend. Enterprise value to revenue of 2.617 sits below price to sales of 2.92, which means the company holds more cash than debt. The quarterly dividend rose to $1.30 from $1.27 this year, up from $0.57 in 2017, with special payouts such as $3 in 2021 along the way.
Momentum is improving: adjusted EPS of $2.57 beat the $2.52 estimate, flows turned positive in May and June, and ETFs pulled in $4.4 billion of net inflows. One catch remains. Management expects second-half flows to be “meaningfully more challenging than the first half,” and the effective fee rate fell to 38.1 basis points.
W. P. Carey: A Rebuilt Dividend That Rises Every Quarter
W. P. Carey (NYSE:WPC) slid 7.12% over the past month to $64.42, below its 50-day average of $70.07 and its 200-day average of $71.01. The forward dividend of $3.80 yields 5.90%. The fair comparison starts after the late-2023 dividend cut that followed the office spin-off. Since then, quarter-end yields have ran from 5.26% to 6.46%. Today’s yield beats all four quarter-ends of the past year, the highest of which was 5.72%.
On safety, 2026 AFFO guidance was raised to $5.19 to $5.27 per share, putting the payout at about 72.7%. Second-quarter AFFO of $1.34 per share beat the $1.24 estimate. Net debt to EBITDA is 5.5x, and 95% of debt is fixed-rate at a 3.2% weighted average. Since the cut, the quarterly dividend has risen with every payment, from $0.86 to $0.95.
Inflation protection is the draw. 47.8% of base rent is CPI-linked, and the company has invested $1.3 billion this year at cap rates in the mid-7s. One catch remains. Tenant Hellweg’s bankruptcy, $79.4 million of second-quarter impairments and a 2.6% drop in European same-store rent show where the portfolio is under pressure.
Five Discounts, One Common Thread
All five stocks are cheaper today than their own recent history, and all five still cover their dividends, with payout ratios between 50.3% and 74.8%. VICI has the largest discount, T. Rowe Price the biggest margin, Realty Income the longest monthly record, and NNN and W. P. Carey the most recent raises. Keep an eye on AFFO and earnings guidance in the next round of reports, because coverage is what keeps a cheap yield from turning into a value trap (we outlined the seven signals that a big yield is about to be cut in a free report you can grab here).
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.