A $1,000 Bet on Palo Alto Networks Beat the S&P 500 by More Than 5x Over Ten Years
Palo Alto Networks turned a humble firewall appliance into a sprawling AI security platform, and investors who held through three brutal drawdowns since 2020 found out just how much patience can pay off. But at today's valuation, the next decade…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
From Firewall Boxes to an AI Security Platform
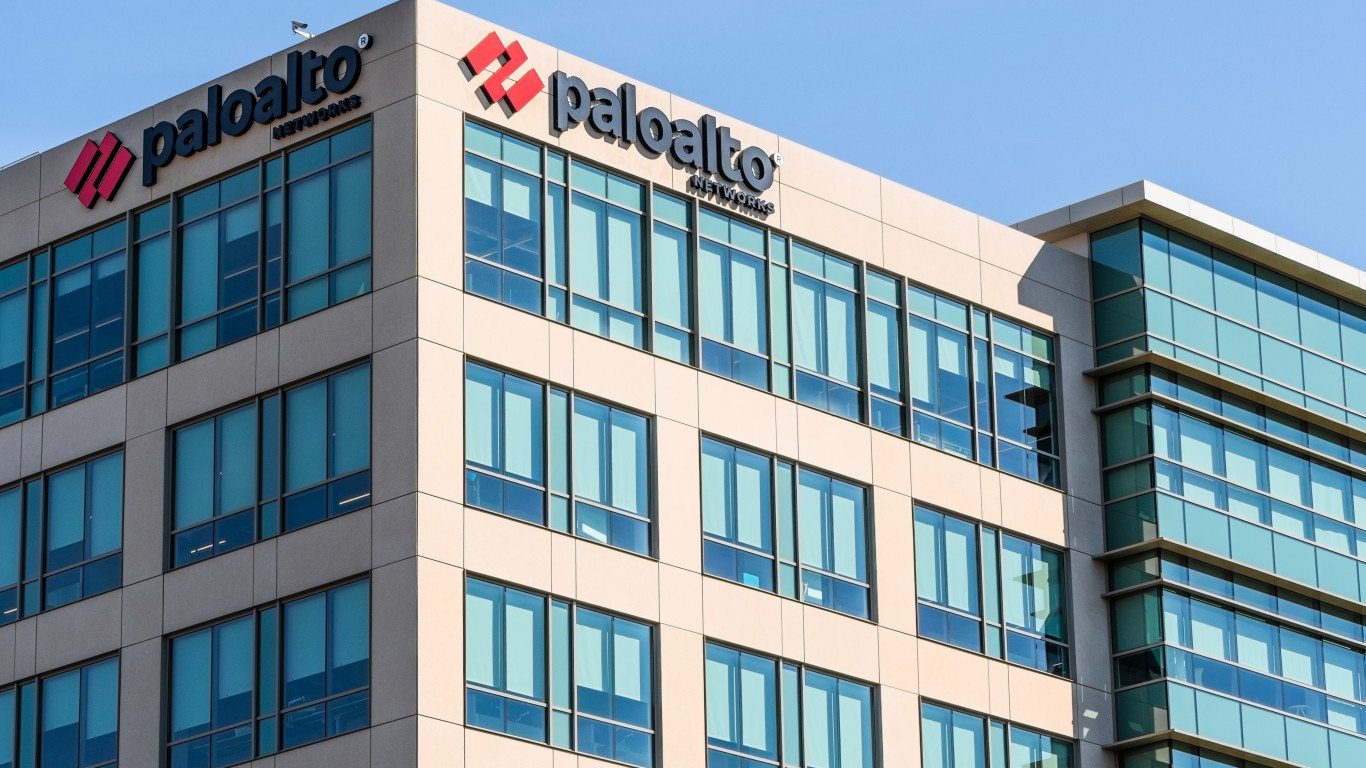
Ten years ago, Palo Alto Networks (NASDAQ:PANW | PANW Price Prediction) was mostly known for one product: the next-generation firewall, a hardware appliance that carried it to an IPO in July 2012.
The turn came after Nikesh Arora became CEO in June 2018. He pushed “platformization,” pulling network security, cloud security (Prisma) and security operations (Cortex) into integrated suites. Acquisitions fed the plan: CyberArk in identity security, Chronosphere in observability and Console in agentic AI. Subscription and support revenue now dominates, at $2.67B of $3.41B in fiscal Q4 2026.
Fiscal 2026 revenue reached $11.48B, up 24.5%, and next-generation security ARR (annual recurring revenue) hit $9.10B, up 63%. Arora said AI is “elevating cybersecurity to the top of the CIO priority list.”
Your $1,000 Became Roughly $15,700
Palo Alto pays no dividend, so these figures come entirely from share price gains. Also, they are adjusted for the 3-for-1 split in 2022 and 2-for-1 split in 2024.
1-Year Return
- Initial Investment: $1,000
- Current Value: $2,016.70
- Total Return: 101.67%
- S&P 500 (same period): $1,166.60 (16.66%)
5-Year Return
- Initial Investment: $1,000
- Current Value: $5,157.10
- Total Return: 415.71%
- Annualized Return: 38.83%
- S&P 500 (same period): $1,795.10 (79.51%)
10-Year Return
- Initial Investment: $1,000
- Current Value: $15,676.80
- Total Return: 1,467.68%
- Annualized Return: 31.68%
- S&P 500 (same period): $3,630.30 (263.03%)
Palo Alto beat the index over all three periods, but holding it was rough. Shares fell 30% from January to March 2020, 33% from March to December 2022, and 23% between November 2024 and February 2026, when they reached $139.57.
The stock opened 2026 at $184.20 and is up 126.84% year to date. The biggest jump followed the June report, in which the acquisitions contributed $388M. Investors who sold during February’s low missed that run (we studied a lot of these ignored winners and pulled out the pattern in a free report here).

What Has to Go Right From Here
The bull case rests on platformization turning into durable ARR growth and management reaching its $20B NGS ARR target by FY30 and 40% FCF margin by FY28. A $21.2B backlog and FY27 revenue guidance of $14.10B to $14.20B support that path.
The bear case plays out if the CyberArk, Chronosphere and Console integrations slip up, or if Microsoft (NASDAQ:MSFT), CrowdStrike (NASDAQ:CRWD) and Zscaler (NASDAQ:ZS) pressure pricing. Shares trade at 1,084x trailing GAAP earnings, 94x forward earnings and 81x free cash flow. The price also stands above the consensus analyst target of $396.92.

Today’s setup differs from 2016. Back then, a firewall company priced at $26.65 split-adjusted had room to surprise. Today, a $341.8B platform carries 10 Strong Buy and 32 Buy ratings. The business is stronger, but the price assumes things go right. This stock has delivered a 20%-plus decline three times since 2020.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.