The One Number That Could Decide Palantir’s Next Big Move
Palantir just posted its ninth straight earnings beat and the stock surged, but one metric buried in the quarterly report now controls whether the premium multiple holds or collapses under rising costs and slowing momentum.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
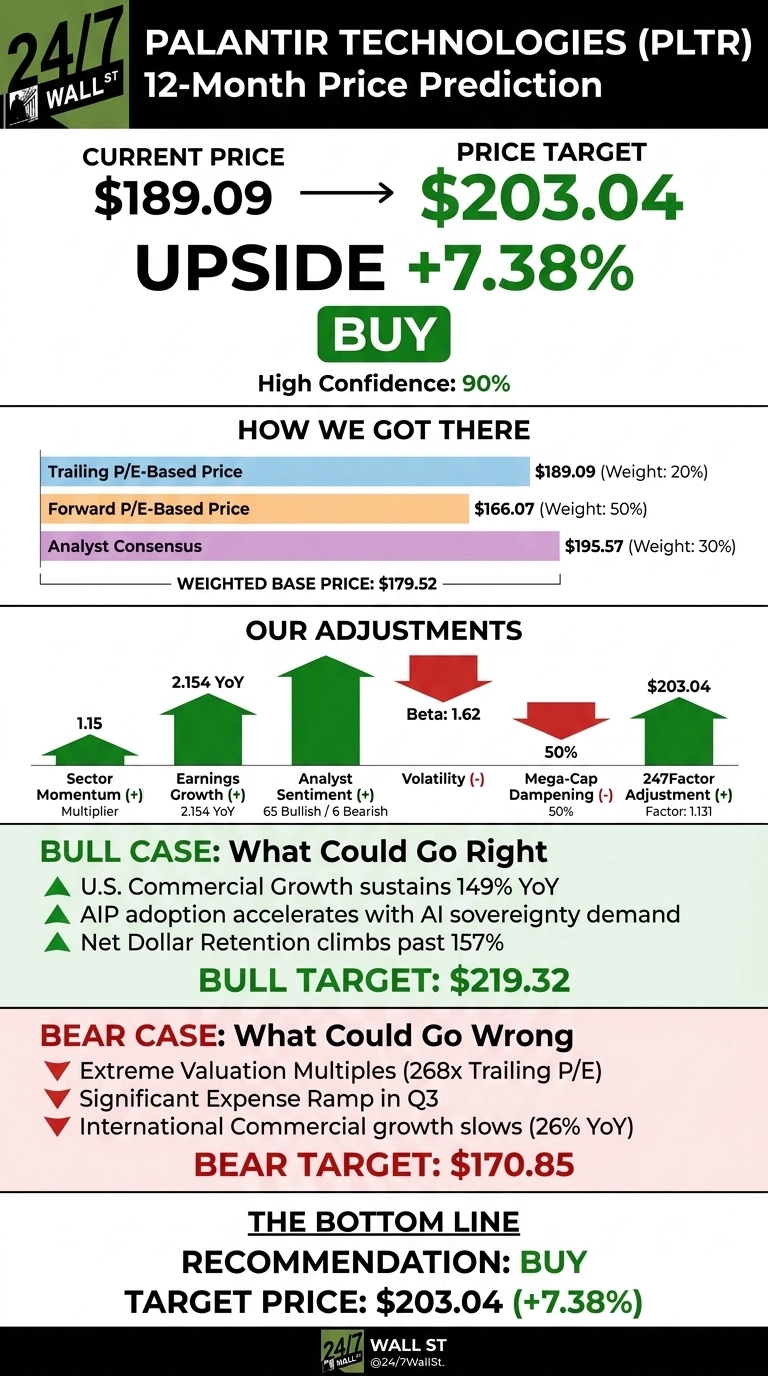
The 24/7 Wall St. price target for Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) is $203.04, which means 7.38% upside from the $189.09 reference price. Shares traded near $191.87 Tuesday afternoon.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $189.09 |
| Price Target from 24/7 Wall St. | $203.04 |
| Upside/Downside | 7.38% |
| Model Signal | BUY |
| Confidence Level | 90% |

Our model has high confidence in that target. The one number that could decide Palantir’s next move is U.S. commercial revenue growth, which reached 149% last quarter.
CEO Alex Karp said he is “driving the business to grow at a rate equal to or above what we have in U.S. commercial for the next 18 months.” If that pace holds, the premium multiple looks justified. If it fades, there is little cushion left.
Record Quarter Sparks a Rally Into October
Palantir rose 2.34% over the past week, 10.06% over the past month, and 7.94% year to date. It now trades in the upper part of its 52-week range of $106.37 to $207.52, well above the $134.44 close on July 16.
Second-quarter adjusted EPS of $0.41 exceeded the $0.28 estimate, the 9th consecutive beat. Revenue rose 92.8% to $1.935B, and the stock gained 29.45% on earnings day. Full-year revenue guidance went up to $8.150-$8.158B. Barron’s argued Tuesday that the stock’s appeal is easier to explain than the company itself (Barron’s).
Why Bulls See $219 and Beyond
The bull case reaches $219.32. Remaining U.S. commercial deal value jumped 124% to $6.238B. Net dollar retention climbed to 157%, and remaining performance obligations rose 103%.
Wall Street mostly agrees: 19 Buy ratings and 1 Strong Buy behind a consensus target of $195.57. Market-implied pricing puts a 0.58 probability on the stock touching $204 in October.

What Could Drag Palantir Toward $171
Our bear case is $170.85. Palantir trades at 268x trailing earnings, and international commercial revenue grew only 26%. Management also expects a “significant ramp in expense in Q3”.
History shows a beat alone may not lift the stock: after an 18.07% surprise in the first quarter, shares fell 6.93%. Bulls can point out that the higher spending pays for technical hiring and sovereign AI work, and a 47% GAAP operating margin leaves room to absorb it.

How Palantir Compares to Snowflake and MongoDB
Snowflake (NYSE:SNOW) belongs here because it sells the same data-sovereignty idea to enterprises. Revenue grew 35.09% last quarter, and Snowflake trades at 107x free cash flow, compared with 207x for Palantir.
MongoDB (NASDAQ:MDB) competes for the same budgets for AI data infrastructure. Its revenue grew 30.5%, with a market value of $29.19 billion.
| Company | Latest Quarterly Revenue Growth | Non-GAAP Operating Margin |
|---|---|---|
| Palantir | 92.8% | 62% |
| Snowflake | 35.09% | 15.3% |
| MongoDB | 30.5% | 24% |
Palantir is growing far faster than either peer and at much higher margins. That supports a premium and makes our target look reasonable.
Palantir Price Prediction 2026-2030
The 24/7 Wall St. price target of $203.04 carries 90% confidence. What matters most is whether U.S. commercial growth stays above the 134% full-year guidance floor.
The case gets stronger if third-quarter revenue exceeded the $2.160-$2.164B guide while margins hold. The case weakens if growth slows as expenses climb. Overall, the numbers support the upside.
Looking further out, here is where our model projects Palantir could trade, assuming current growth and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $203.04 |
| 2027 | $214.76 |
| 2028 | $227.17 |
| 2029 | $240.28 |
| 2030 | $254.16 |
These projections assume Palantir keeps executing on its sovereign AI strategy. A long-run multiple squeeze or a slowdown in U.S. commercial demand could move results well away from these figures.
Palantir is only one way to play the AI buildout; the infrastructure vendors that keep data centers running rarely get the same attention, and we rounded up seven of them in a free report on the AI infrastructure trade.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.