Apple’s 2.5 Billion Devices Unlock a Trillion-Dollar AI Opportunity, 16% Upside Ahead
Apple sits on 2.5 billion active devices and a Services engine already running near $120 billion annually, yet one margin warning and a below-consensus analyst target raise a serious question about whether the premium is earned.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
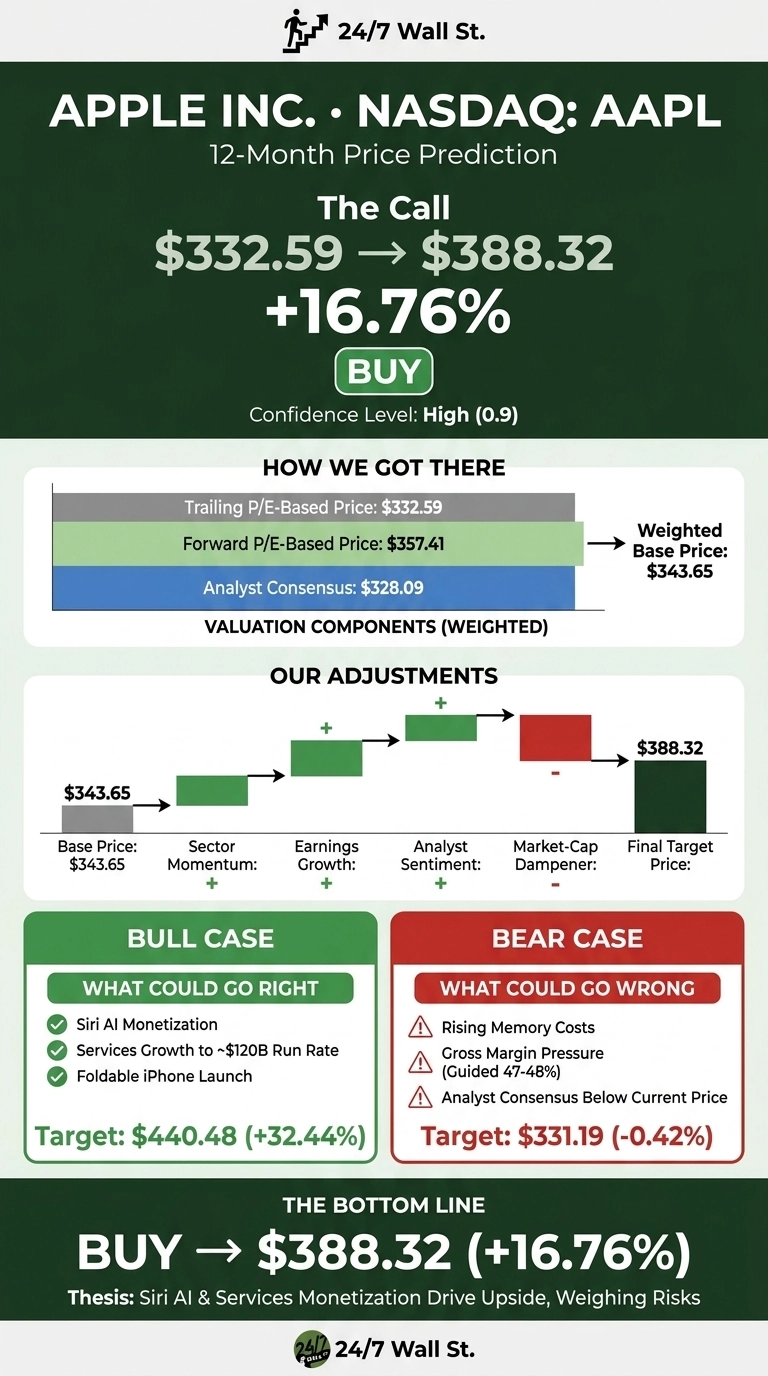
Apple (NASDAQ:AAPL | AAPL Price Prediction) trades at $332.59. Our 24/7 Wall St. price target for Apple is $388.32 over the next 12 months, which means 16.76% upside.
| Metric | Value |
|---|---|
| Current Price | $332.59 |
| 24/7 Wall St. Price Target | $388.32 |
| Upside/Downside | 16.76% |
| Model Rating | BUY |
| Confidence Level | High (0.9 on a 0 to 1 scale) |

Apple’s growth opportunity comes from monetizing Apple’s installed base of more than 2.5 billion active devices running the new Siri AI. Services generated $30.74B last quarter, putting the annual run rate near $120B.
Paid AI levels, smart-home hardware, and a foldable iPhone could each expand recurring revenue. The model carries high confidence because the target rests on actual earnings momentum.
Record iPhone 17 Quarters Keep Apple Near Its 52-Week High
Apple shares slipped 1.7% over the past week but remain up 22.7% year to date and 29.4% over one year, near the top of its 52-week range of $242.76 to $345.34. Fiscal Q3 revenue rose 16.4% to $109.42B, beating the $108.96B estimate. EPS came in at $2.02 against $1.89 expected, the 9th straight beat.
In September Apple launched the iPhone Duo, its first foldable, priced at $1,999. Fortune also reported that Oura pulled its IPO in part because of an “Apple-sized threat”.
Why Bulls See $440 Within Reach
Our bull case reaches $440.48, a 32.44% return. On CNBC’s Fast Money, one panelist argued that “Services have 75% margin and it’s 42% of the business and growing.”
On the July call, Tim Cook, who was CEO at the time, said Apple was considering iCloud Plus upgrades for heavy Siri AI users. Bloomberg’s Mark Gurman expects Apple to produce 7 to 10 million foldables, and he has also pointed to a smart-home hub as an upcoming product category.
Capital returns add support through a $100B buyback authorization. Among covering analysts, 6 rate the stock a strong buy and 19 rate it a buy.

Tariff Refunds and Memory Costs Could Pin Shares Near $331
The bear case is $331.19. Q3 tariff refunds added about 2 pts to gross margin and around $0.11 to EPS. Apple guided September-quarter gross margin to 47% to 48%, down from 50.1%, as memory costs rise.
The consensus target of $328.09 sits below current price, and 3 analysts rate it a strong sell. Bulls counter that margin pressure reflects investment: R&D rose to $11.73B from $8.9B as Apple builds AI capabilities.

Apple Commands a Premium Over Its Big Tech Peers
| Company | Trailing P/E | Latest Quarterly Revenue Growth |
|---|---|---|
| Apple | 43 | 16.4% |
| Microsoft (NASDAQ:MSFT) | 29 | 17.75% |
| Alphabet (NASDAQ:GOOGL) | 15 | 24.23% |
Microsoft (NASDAQ:MSFT) offers the closest AI monetization comparison. Azure grew 43%, yet Microsoft trades at a lower multiple.
Alphabet (NASDAQ:GOOGL) competes through Android and Gemini, but its low P/E reflects a $99.03 billion equity gain and suspended buybacks. Apple’s capital returns help justify its premium.
Against these peers, our 24/7 Wall St. price target looks reasonable.
Siri AI Tips Our Model to a Buy Rating
Our 24/7 Wall St. price target of $388.32 carries a buy rating and high confidence. Earnings growth of 0.287 outweighs the premium multiple.
Our model’s upside case depends on Siri AI driving iCloud upgrades and Services continuing to grow, a theme that goes well beyond the chipmakers (we covered seven of the suppliers supporting the AI expansion, from power to cooling, in a free report you can grab here).
Caution would rise if gross margin stays below 48% after tariff refunds roll off. Overall, the model considering upside above the identified risks.
Apple Price Prediction 2026-2030
| Year | 24/7 Wall St. Price Target | Bull | Bear |
|---|---|---|---|
| 2026 | $347.49 | $353.71 | $330.16 |
| 2027 | $389.11 | $423.16 | $331.36 |
| 2028 | $436.05 | $500.94 | $335.17 |
| 2029 | $482.76 | $546.49 | $340.98 |
| 2030 | $520.21 | $605.18 | $356.98 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.