Prediction: Netflix’s Next Growth Engine Could Surprise Investors
Netflix shares have dropped 26% this year even as revenue keeps climbing, and a largely overlooked segment of its business could be the catalyst that catches investors off guard.

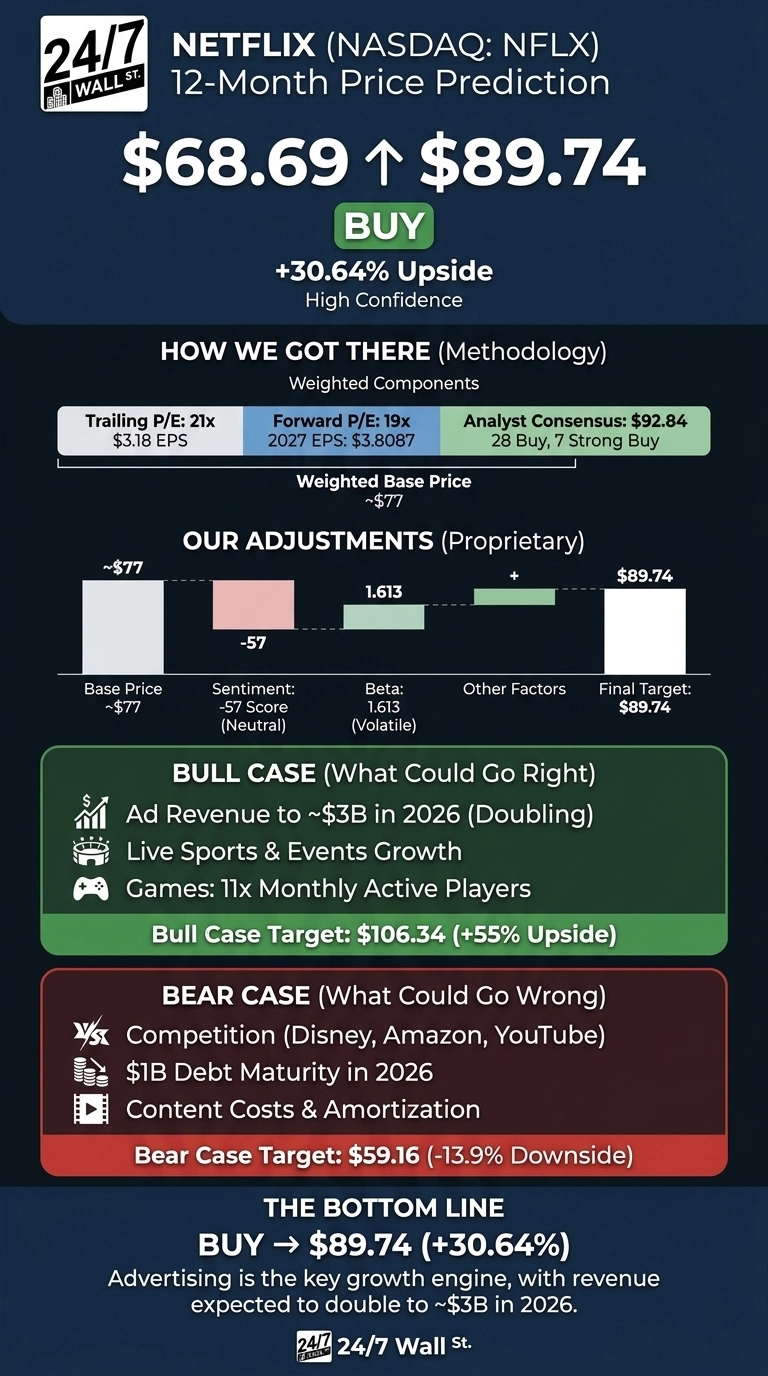
Our 24/7 Wall St. price target for Netflix (NASDAQ:NFLX | NFLX Price Prediction) is $89.74. That means 30.64% upside from the latest close of $68.69. Our model rates its confidence as high.
| Metric | Value |
|---|---|
| Current Price | $68.69 |
| 24/7 Wall St. Price Target | $89.74 |
| Upside/Downside | 30.64% |
| Model Signal | Bullish |
| Confidence Level | High |
Netflix’s business keeps growing despite market pressure. Advertising should roughly double to about $3 billion in 2026. Live events and games add newer revenue streams. Investors appear to be pricing in a slowdown the reported numbers have yet to show.
Shares Slide 26% in 2026 as Revenue Keeps Climbing
NFLX is down 1.89% over the past week, 11.86% over the past month and 26.44% year to date. It trades about 45% below its 52-week high of $124.86 and roughly 5.5% above its low of $65.08.
Q2 revenue rose 13.4% to $12.56 billion, slightly missing the $12.58 billion estimate. EPS of $0.80 beat consensus of $0.7883, and operating margin reached 33.4%.
Earlier this year, Netflix walked away from its Warner Bros. deal and collected a $2.80 billion termination fee. A rival’s merger with Warner Bros. has now closed, and Barron’s says Netflix comes out of that as the better stock (Barron’s). Netflix put its free cash into buybacks instead, buying back $4.7B of stock in Q2, its largest buyback quarter ever.
How Our Model Arrives at $89.74
The 24/7 Wall St. price target combines standard valuation metrics with factor-based adjustments. It considers a trailing P/E of 21 on TTM EPS of $3.18, a forward P/E of 19, and the analyst consensus target of $92.84. That consensus comes from 28 Buy, 7 Strong Buy, 15 Hold and 1 Sell ratings.

Advertising Could Power a Run to $106
Ad revenue exceeded $1.50 billion in 2025. The advertiser count has rose 70% to more than 4,000, and the ad tier accounts for over 60% of sign-ups in ad markets. Management called the narrowing pricing gap between the ad tier and the standard plan “near-term under-realized revenue growth.”
Live programming takes 5% of the content budget, yet it produced six out of top 10 new-member sign-up days over five years. On games, monthly active players for cloud titles have grow 11x, inside a market of roughly $150 billion in consumer spending.
If Netflix reaches the high-end 2027 EPS estimate of $4.09 and the stock gets a 26x multiple, shares would be worth $106.34, about 55% upside.

What Could Keep Netflix Stuck Below $70
Q2 free cash flow fell 32.73%, and content amortization grew faster than revenue. Netflix has $1 billion of debt to refinance, along with FX exposure and competition from Walt Disney (NYSE:DIS), Amazon (NASDAQ:AMZN) and YouTube.
Much of the cash flow drop came from higher cash taxes tied to the termination fee. Full-year free cash flow guidance held at about $12.5 billion. If earnings come in at the low 2027 estimate of $3.48 and the stock trades at 17x, it would be worth $59.16, about 13.9% downside.
Netflix Trades Between Disney’s Discount and a Peer’s Premium
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Netflix | 19 | 13.4% |
| Disney | 14 | 6.8% |
| Roku (NASDAQ:ROKU) | 39 | 21.9% |
Disney trades at a cheaper 14x forward earnings, but its quarterly earnings fell 48.3%, so Netflix’s premium looks gets. Roku commands 39x forward earnings on revenue growth of 21.9%. The 24/7 Wall St. price target at roughly 24x falls between those two.
Netflix Price Prediction 2026-2030
My 24/7 Wall St. price target remains at $89.74 with high confidence. Advertising is the key variable for the outlook. Investors exploring the stock can track whether ad revenue reaches about $3 billion and whether margins hold near guidance.
For 2026, our model applies today’s multiple to the 2026 consensus EPS of $3.5836. From 2028 forward, it assumes 10% annual EPS growth at a steady 24x multiple.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $76.08 |
| 2027 | $89.74 |
| 2028 | $98.71 |
| 2029 | $108.59 |
| 2030 | $119.44 |
These projections assume Netflix executes on its current strategy. Faster ad monetization could push results higher, while grow content costs could push them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.