One Overlooked AI Stock That Could Surprise Investors
Dell's AI customer list is exploding and its backlog dwarfs what Wall Street expects, yet analysts have barely moved their price targets. Here is what the numbers actually suggest about where this stock could go by 2027.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Dell Technologies (NYSE:DELL | DELL Price Prediction) has turned into one of the market’s biggest AI winners, but it still gets less attention than the chipmakers. Shares are up 348.53% year-to-date and 1,048.21% over five years. The driver is a customer base that keeps getting wider.
Dell’s AI infrastructure list passed 6,500 customers, and 3,300 of them signed on in the last three quarters. On Dell’s September 1 earnings call, Jeff Clarke said “IT environments have shifted from cost centers to value drivers that fuel growth and competitive advantage, and customers are investing accordingly.”
So what would it take for Dell to reach $800 by 2027?

Wall Street’s Price Targets Lag Behind Rapidly Rising Estimates
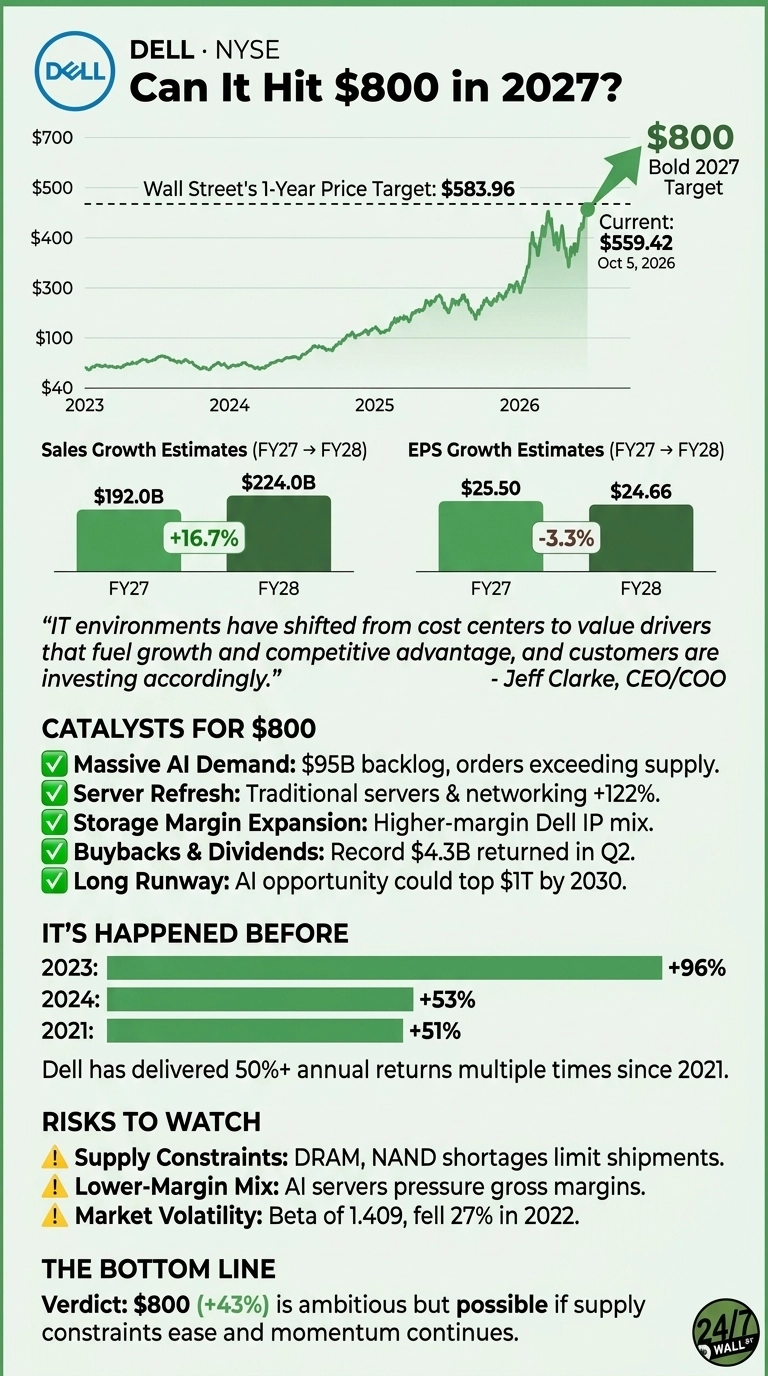
The average analyst target is $583.96. That’s only 4% above today’s $559.42. Still, analysts like the stock: 19 rate it a Buy or Strong Buy and none rate it a Sell.

Earnings estimates have rose faster than targets: ninety days ago, analysts expected $18.3732 in fiscal 2027 EPS. Today the figure is $25.8976, a 41% increase. In the last 30 days there were 22 upward revisions and zero cuts.
Management now guides to $192 billion in revenue (up 69%) and $25.50 in non-GAAP EPS (up 148%). Dell has also beaten EPS estimates in five straight quarters, so actual results may land above forecasts again.

Here’s What It Takes for Dell to Reach $800
Dell currently trades at 22x fiscal 2027 estimates. At $800, that multiple would rise to 31x. Against fiscal 2028’s $24.6637 consensus, it would be 32x.
That fiscal 2028 average is pulled down by one outlier estimate of $9.67, while the high estimate is $30.19. A low-30s multiple is a premium, but it’s justified for a company more than doubling its earnings.
The case for Dell reaching $800.
- Backlog visibility: Dell booked $60.9 billion in AI orders last quarter and ended it with a $95 billion backlog. Management says the pipeline is still multiples of backlog.
- Server refresh: Traditional servers and networking grew 122%, and Dell gained more than 10 points of share over two quarters. Its new 18G server can replace 12 to 14 older machines.
- Storage margins: Storage revenue rose 26%. More of that mix is Dell’s own IP, which has higher margins.
- Buybacks: Dell returned a record $4.3 billion to shareholders in the quarter.
- Long runway: Management estimates the AI opportunity could top $1 trillion by 2030.
The main challenge is supply: management said demand is running ahead of supply, with DRAM and NAND shortages limiting how much it can ship. A falling market would also make $800 harder to reach.

Dell’s History Says $800 Is Within Reach
Getting to $800 requires a 43% gain. Since 2020, Dell has topped that bar in three full calendar years: 51% in 2021, 96% in 2023 and 53% in 2024.
That’s before counting 2026’s run so far. The stock is volatile, though. It fell 27% in 2022 and has a beta of 1.409.
$800 Is a Stretch, but Dell Has the Backlog to Get There
Reaching $800 would take a 43% move. Estimates are rose quickly, Dell keeps beating them, and a $95 billion backlog gives unusual visibility.
Should supply improve and servers and storage keep growing, the multiple has room to expand. Dell is one of the best examples of an AI winner that isn’t a chipmaker, and we rounded up seven more infrastructure names riding the same expansion in a free report here. Returns at this level are rare, but this is how Dell could deliver outsized gains in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.