Strategy Lost More Than 50% of Its Value Last Year: It Will Return 180% According to One Wall Street Pro
Strategy Inc. lost more than half its value while quietly becoming the world's largest corporate Bitcoin treasury, and one Wall Street analyst thinks that combination sets up a trade most investors are too spooked to touch.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
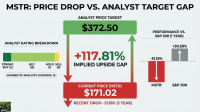
Strategy Inc. (NASDAQ:MSTR | MSTR Price Prediction) currently trades at $153.37. Wall Street’s average price target is $236.80, which implies 54.4% upside.
Strategy Inc. started as enterprise analytics software. Today it is the world’s largest corporate Bitcoin (CRYPTO:BTC) treasury, holding 846,000 bitcoin. Benchmark analyst Mark Palmer repeated a Buy rating and a $435 target, implying 183.6% upside.
Bitcoin’s Slide Pulled Strategy Inc. Down 53% in a Year
Bitcoin’s decline drove the damage. Strategy Inc. lost 53.3% over the past year. Bitcoin fell 32.53% over the same period. With a beta of 3.571, the stock amplifies every move in the coin.
Fair value accounting turned that decline into large paper losses. Over the last three reported quarters, unrealized losses came to $17.44 billion, $14.46 billion and $8.32 billion. Second-quarter EPS of -$24.45 badly missed the $3.07 consensus. At-the-market offerings brought in $8.41 billion, and the firm paid $400.7 million in preferred dividends.
Benchmark’s $435 Call Depends on BTC Yield and a NAV Premium
Palmer’s thesis rests on three elements: BTC Yield (bitcoin held per diluted share as the company issues equity and debt to buy more coin), a lasting premium to net asset value, and a software business generating recurring revenue.
Management’s latest figures back parts of the thesis. Subscription revenue grew to $62.86 million from $40.82 million, and the company is targeting a 4.5% BTC Yield this year. CEO Phong Le said the company “reduced our convertible debt by 18% to $6.7 billion”. Strategy Inc. also has a $3.75 billion USD Reserve covering more than 2.1 years of obligations.
Analysts are nearly unanimous. 2 rate the stock Strong Buy, 13 rate it Buy, 1 rates it Hold and none rate it Sell. Their earnings estimates are shakier. The fiscal 2026 EPS average fell from 31.0171 to -21.9385 over 90 days, though fiscal 2027 picked up three up revisions in the past month.
Michael Saylor said on the fourth-quarter call, “Our objective is to double your Bitcoin per share over seven years.” The NAV premium is the weakest leg. If it contracts, every share sale buys less bitcoin per share.
Coinbase and MARA Sank With Strategy Inc. While Riot Held Up
Strategy Inc. had plenty of company. Most of the crypto group sold off together.
Coinbase Global (NASDAQ:COIN) fell 52.51% over the year. Trading at $178.45 versus a $208.73 target, it offers only 17.0% upside. Its ratings are more divided, with 12 Holds and 2 Sell ratings.
MARA Holdings (NASDAQ:MARA) dropped 48.84%. At $10.36 against an $18.69 target, it offers 80.4% upside. Analysts are split across 8 bullish, 4 Hold and 1 Sell ratings.
Riot Platforms (NASDAQ:RIOT) is the outlier, down just 13.65% over the year and up 46.33% year to date. Trading at $18.54 versus a $31.54 target, analysts see 70.1% upside.
Strategy Inc. Is Flat This Year as the S&P 500 Gains 13.98%
At $153.37, Strategy Inc. trades well below the $236.80 consensus target from 16 analysts, leaving 54.4% implied upside. Shares are up 0.93% so far this year, and the S&P 500 has gained 13.98%. Over one year, the stock lost 53.3% while the index rose 16.16%.
Shares rose 7.4% over the past month as Bitcoin climbed 28.33% over 60 days, though the stock dropped 6.79% last session.
I Lean Bullish, With the Consensus Target as My Anchor
The bull case for Strategy Inc. improves if Bitcoin’s rebound holds and the company keeps adding bitcoin per share without heavy dilution. Rising coin prices would lift reported earnings, the NAV premium could rebuild, and $236.80 looks reachable. The bear case takes over if Bitcoin rolls over. Preferred dividends, $6.7 billion of convertible debt and constant share issue would weigh on common shareholders with no earnings buffer.
I lean cautiously bullish. Bitcoin is down 4.89% this year while the stock is roughly flat, suggesting much of the de-rating is priced in. Benchmark’s $435 target needs a lasting premium and a strong Bitcoin rally. I treat the consensus target as realistic upside and the 183.6% call as best case. Riding a crypto-proxy like this is fine as long as you plan the exit, which is the whole point of our free bubble survivor’s handbook.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.