Goldman Sachs Upgrades Palantir to Buy, Sees 18% Upside and Further Outperformance Into 2027
Goldman Sachs just broke from the Wall Street pack and handed Palantir a rare upgrade, arguing the AI data company is entering a new growth phase that could stretch well beyond what most analysts expect.

Goldman Sachs (NYSE:GS | GS Price Prediction) analyst Gabriela Borges upgraded Palantir (NASDAQ:PLTR) to Buy from Neutral with a $230 price target. Goldman’s industry conversations suggest the stock is setting up for another phase of outperformance into 2027.
The upgrade shows growing Wall Street confidence that sovereign AI can extend Palantir’s opportunity again, even though the stock already has a premium valuation.

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| PLTR | Palantir | Goldman Sachs | Upgrade | Neutral | Buy | Not disclosed | $230 |
Analyst’s Case: A Bigger Market Takes Shape
Borges told investors Palantir’s total addressable market “may be setting up for another step function change in depth”. She credits three drivers: sovereign AI, bespoke applications, and the company’s newer verticalization strategy.
Palantir’s second-quarter call supports each point. Management said customers want control over their enterprise data, logic, actions, security, models, and weights.
Customers are also expanding from single operating companies into wider portfolios. One multinational technology company did exactly that and converted to a three-year, nearly $370 million deal.
Goldman adds that after the stock’s underperformance year-to-date, Palantir is trading at a discount to its growth compares.
Palantir’s Growth Engine Keeps Accelerating
Palantir sells the Gotham, Foundry, and AIP platforms. For the second quarter of fiscal 2026, reported August 3, 2026, revenue reached $1.94 billion, up 92.83% YoY. EPS of $0.41 beat the $0.28 consensus, making its 9th consecutive EPS beat.
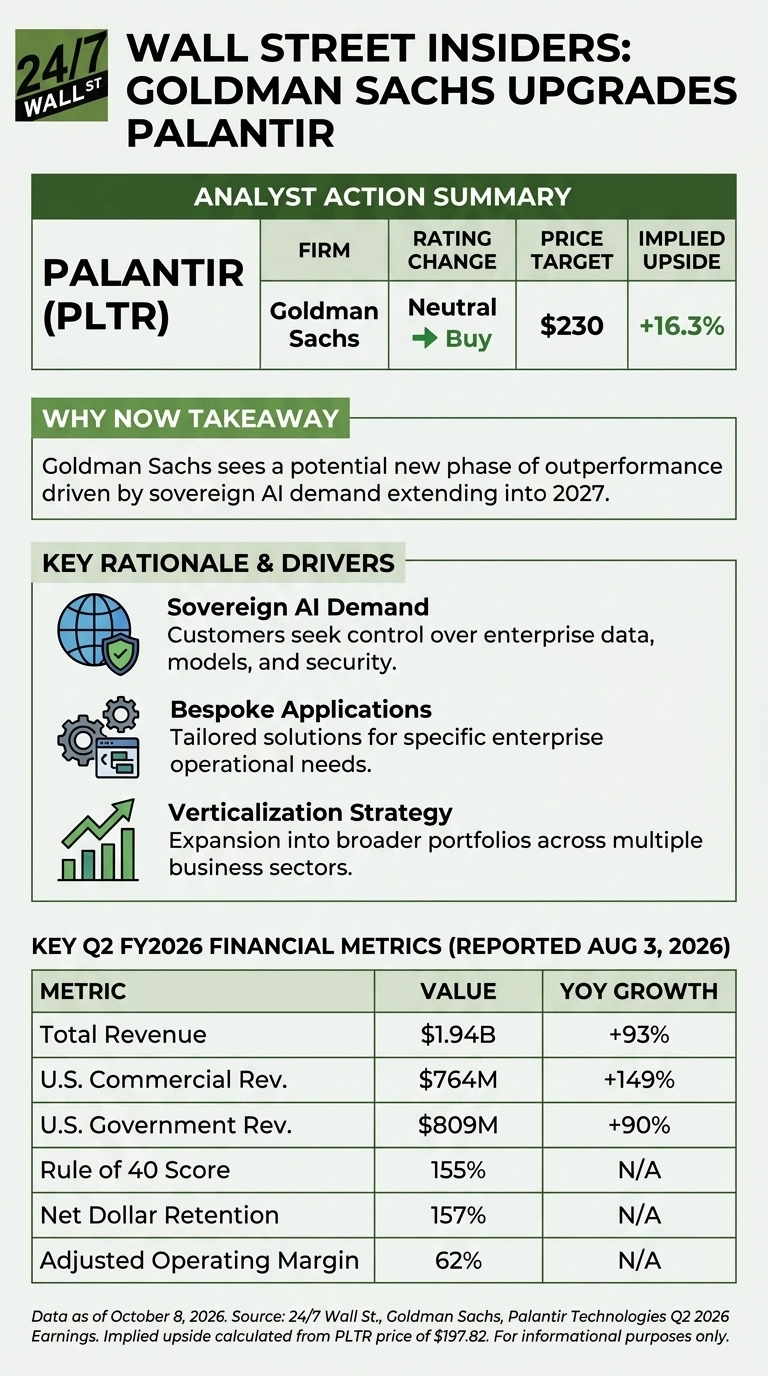
- U.S. commercial revenue: $764M, up 149% YoY
- U.S. government revenue: $809M, up 90% YoY
- Net dollar retention: 157%
- Rule of 40 score: 155%

Management raised full-year revenue guidance to $8.150 billion to $8.158 billion and expects U.S. commercial growth of at least 134%.
Why the Move Matters Now
Palantir stock trades at $197.82, up 11.29% year to date and 13.47% over the past month. Its 52-week high is $207.52. The forward P/E sits near 85x, which makes Goldman’s “discount” argument a relative call against other high-growth names.

Goldman’s $230 target sits above the consensus target of $195.57. Coverage leans bullish, with 19 Buy and 1 Strong Buy ratings against 9 Hold ratings. CEO Alex Karp has set an ambitious bar: “I am driving the business to grow at a rate equal to or above what we have in U.S. commercial for the next 18 months.”

What It Means for Your Portfolio
Goldman’s upgrade gives retirement-focused investors a big bullish voice on Palantir, though the risks are real. Stock-based compensation totaled $265M in Q2 2026.
The company’s filings point to long sales cycles, contracts that customers can terminate for convenience, and heavy U.S. concentration, with U.S. revenue at over 81% of total revenue. A beta of 1.602 points to larger swings than the wider market.
(We reverse-engineered the traits past monster tech winners shared before their runs and put the pattern in a free playbook: The Next Nvidia Playbook.)
The next test is third-quarter revenue against guidance of $2.160 billion to $2.164 billion. Management has also highlighted a significant third-quarter expense ramp. Keep an eye on whether bookings momentum holds up as 2027 approaches.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.