Apple’s Strategy Is Starting to Look Like a Masterstroke of Genius
While rivals burn billions rebuilding their balance sheets around AI infrastructure, Apple is quietly running a very different play, and nine straight earnings beats suggest it might be working better than anyone expected.

I have added to my Apple (NASDAQ:AAPL | AAPL Price Prediction) position after every earnings report this year, and the latest results reinforce that thesis. The company just delivered its ninth consecutive EPS beat, and each quarter gives me more evidence that management’s playbook works.
An AI Strategy That Pays Apple Instead of Draining It
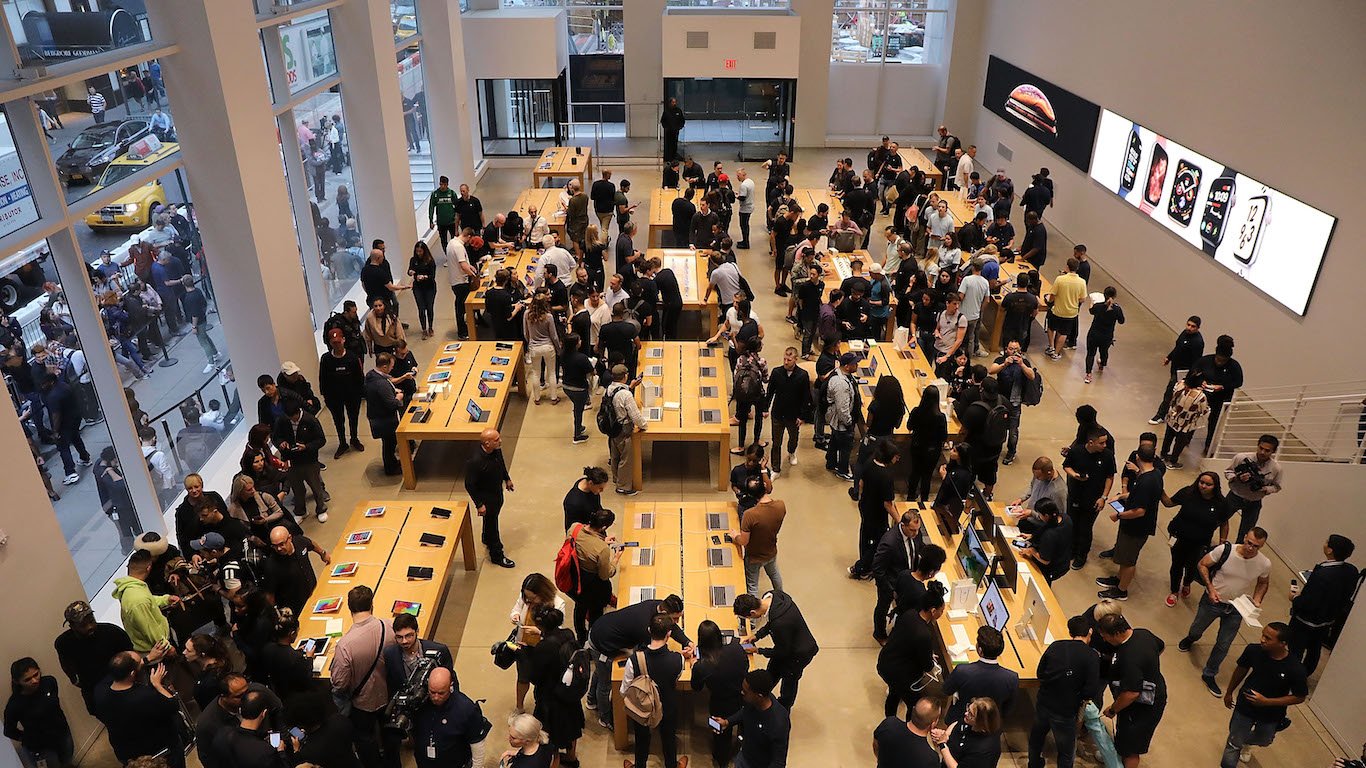
Apple’s approach to AI is what keeps pulling me back. Rivals pour cash into data centers. Apple puts AI on the device already in your pocket and lets an installed base of more than 2.5 billion active devices handle distribution. On the July call, Tim Cook called on-device processing “very strategic and sort of a competitive weapon, if you will.” The all-new Siri AI launched at WWDC26, and management already sees room for upgrade possibilities on iCloud Plus. Every iPhone becomes an AI platform while Apple keeps its capital intact. December-quarter capex came in at just $2.37 billion against operating cash flow of $53.93 billion.
Three Numbers That Strengthen Apple’s Bull Case
First, Services keeps growing. Revenue rose from $26.6 billion in the March 2025 quarter to a record $30.98 billion a year later, and Services gross margin reached 75.6% in the June quarter. That recurring stream turns hardware buyers into long-term customers.
Second, Apple reduces my share count for me. The 0.31% dividend yield looks thin, so I treat the buyback as the real income engine. Apple bought back $62.094 billion of stock in the nine months through June 27, 2026, added a $100 billion authorization, and raised the dividend 4% to $0.27 per share.
Third, growth is accelerating. June-quarter revenue rose 16.36% to $109.42 billion, net income grew 27.12%, and EPS of $2.02 topped the $1.89 consensus. Apple posted June-quarter records in every geographic segment while generating a 53.35% return on invested capital.
Why Apple’s AI Path Looks Stronger Than Microsoft’s
Microsoft (NASDAQ:MSFT) stands out as the clear choice, and its cloud business is excellent. Its AI path, however, runs through concrete and servers. Microsoft spent $115.95 billion on capex in fiscal 2026, up 79.62%, and full-year free cash flow fell 6.46%. Investors pay roughly 59 times free cash flow for Microsoft versus about 50 for Apple. I prefer the company that monetizes AI without rebuilding its balance sheet around it.
Risks That Could Test My Patience
Valuation is the real threat. Apple trades near 44 times trailing earnings, compared with about 30 for Microsoft, so any slip gets punished. Tariff refunds also flattered the June quarter by about 2 percentage points of gross margin and $0.11 of EPS, a one-time benefit. Cook described memory costs as “a 100-year flood on the memory pricing,” and Greater China slipped to $14.49 billion in the September 2025 quarter. Friday also brought a report of iPhone 18 Pro production cuts.
None of it breaks my thesis. China bounced to $25.53 billion one quarter later, and management blamed supply constraints on “very high levels of demand.” Even with those constraints, Apple guided September-quarter revenue growth of 9% to 11%.
What Could Power Apple’s Next Leg Higher
The stock gained 141.51% over five years, and the engine behind it looks stronger today. Apple holds $147 billion in cash and marketable securities, and it plans to charge for AI on devices people already own. Apple has turned the AI race into a low-cost upgrade cycle on devices it already sold, and it collects the rent.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.