If This Tech Stock Doubles, Here’s What $10,000 Could Become
Alphabet's cloud backlog just hit half a trillion dollars and AI Mode crossed a billion users, yet the stock still trades at a fraction of where some models say it could land by 2031. Whether that gap closes or collapses…

Alphabet (NASDAQ:GOOG | GOOG Price Prediction) Class C shares trade at $346.72, up 40.67% over the past year. What might a $10,000 stake become by 2031, five years from now?
Alphabet is worth a forward look because its AI spending is already showing up in revenue: Google Cloud is growing faster than at any point in the past several years, and Search is still expanding.
What $10,000 Could Become by 2031
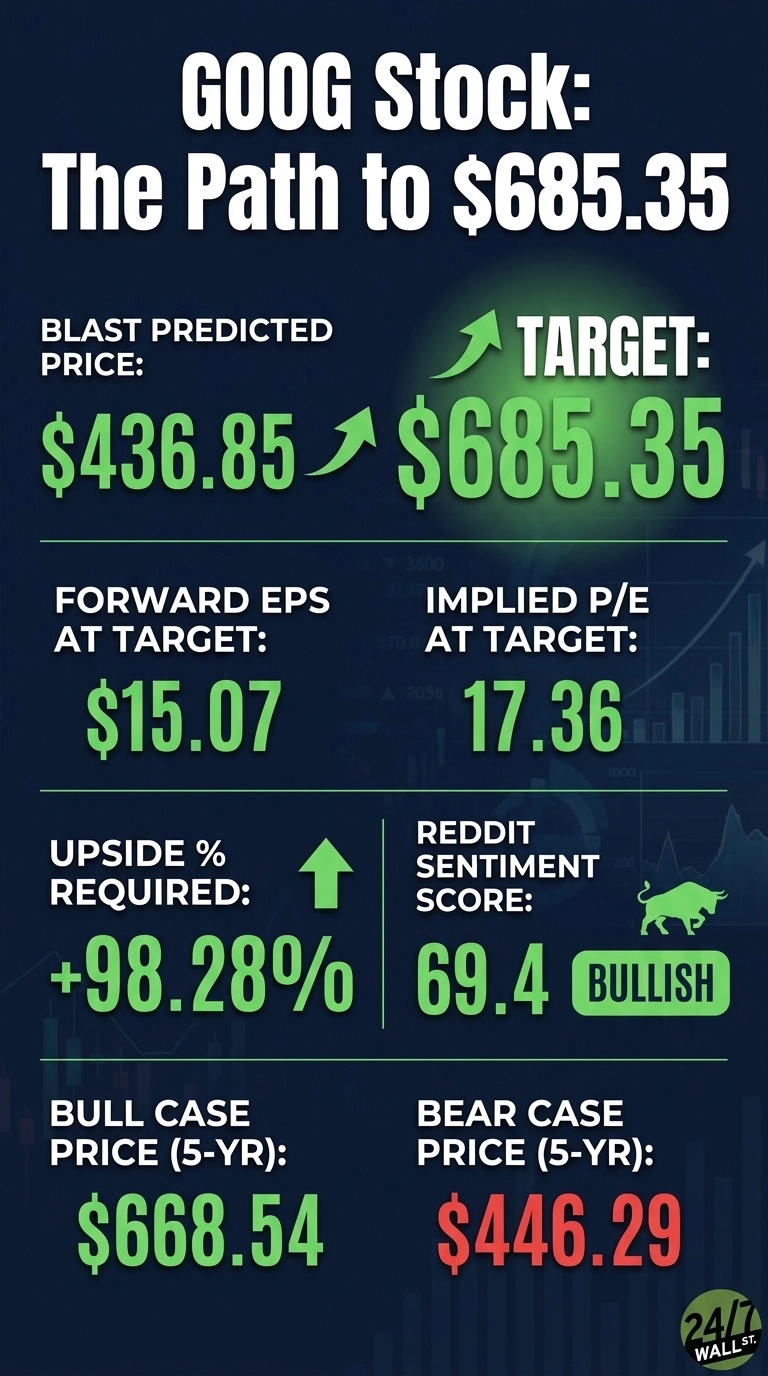
The base-case scenario shows a $10,000 investment could be worth about $19,828 by 2031, a total return of 98.28%. That is close to a double.
Behind it is a five-year base-case target of $685.35 per share, which annualizes to 14.67% from a modeled starting price of $345.64. The model gives this forecast a confidence level of 0.7 on a 0-to-1 scale.
Three Scenarios for a $10,000 Stake
| Scenario (five-year) | Target Share Price | Total Return | Value of $10,000 |
|---|---|---|---|
| Base | $685.35 | 98.28% | $19,828 |
| Bull (optimistic) | $668.54 | 93.42% | $19,342 |
| Bear (conservative) | $446.29 | 29.12% | $12,912 |
Over five years, the model’s bull and base paths end up close together, and the base case actually finishes slightly higher. In practice, the model’s best results center around a double, while even the conservative case leaves your stake ahead of where it started.
The one-year view is more modest. Next year’s base-case target is $436.85, which would turn $10,000 into $12,639. Bull-case projections point to $13,139 and the bear case to $10,691.
Wall Street stands firmly on the optimistic side. Of the analysts covering the stock, 13 rate it a strong buy, 42 a buy and 5 a hold, with no sell ratings. Their consensus price target is $419.65.

What Could Push Alphabet Toward a Double
Cloud Is Becoming a Second Profit Engine
Last quarter, Google Cloud revenue rose 82% to $24.8 billion, and its operating margin expanded to 35.6% from 20.7% a year earlier. Backlog reached $514 billion, and management expects to recognize just over 50% of it within 24 months.
That is booked demand, which gives the base case real visibility (all of those data centers have to be powered and cooled by someone, and we rounded up seven of the companies doing exactly that in a free AI infrastructure report).
AI Is Expanding Search
Search and Other revenue grew 17% to $63.3 billion. AI Mode has passed 1 billion monthly active users, and the Gemini app has 950 million.
Alphabet also launched a Gemini AI agent aimed at OpenAI and Microsoft (NASDAQ:MSFT), Barron’s reported. On the earnings call, the chief executive said: “If anything, over the past year, we’ve gotten more bullish on the opportunities ahead.”
Earnings Estimates Keep Rising
Analysts expect EPS of $15.0715 next year, compared with $11.81 this year. That 2027 estimate has rose from $14.5333 90 days ago.
The stock trades at about 22x forward earnings, which leaves room for the share price to rise along with profits. Alphabet has also beaten EPS estimates for 11 straight quarters.

Risks That Could Derail the Double
The greatest risk to your $10,000 comes from Alphabet’s own spending. Capital expenditures reached $44.9 billion in the quarter, which drove free cash flow to negative $5.9 billion. Full-year capex guidance is $175B to $185B.
Alphabet’s debt has grown to about $100 billion from about $16 billion a year earlier, and the company suspended its buyback program last quarter. Should AI returns disappoint, the bear case of $12,912 could turn out optimistic.
There is also near-term pressure on margins. Management warned that leasing third-party capacity to work around supply constraints will weigh on Cloud margins.
Reported profits can also swing with unrealized gains on equity holdings: last quarter’s net income included a $99.03B gain of this kind. Regulatory pressure remains, including a prior $3.5B fine from the European Commission. And with a beta of 1.21, the stock tends to swing more than the broader market.

Bottom Line for Your $10,000
Based on the model’s five-year scenarios, a $10,000 stake in Alphabet could be worth between $12,912 and $19,828 by 2031, with the base case close to a double.
They reflect modeled scenarios. The key things to watch are Cloud backlog conversion and whether free cash flow recovers as AI spending matures. It is a projection, not investment advice.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.