Buffett Just Made a $37 Billion Bet on This Tech Giant. Should You Buy?
Warren Buffett almost never chases mega-cap tech, which makes Berkshire's massive new position in Alphabet one of the most surprising moves in years and a signal worth taking seriously before the rest of the market catches on.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Berkshire Hathaway’s roughly $37 billion stake in Alphabet, disclosed as a 48 million share position, has recalibrated how investors view the search giant. Warren Buffett rarely chases mega-cap tech, so his conviction here forces a fresh look at whether Alphabet (NASDAQ:GOOG | GOOG Price Prediction) still offers meaningful upside from $344.59.
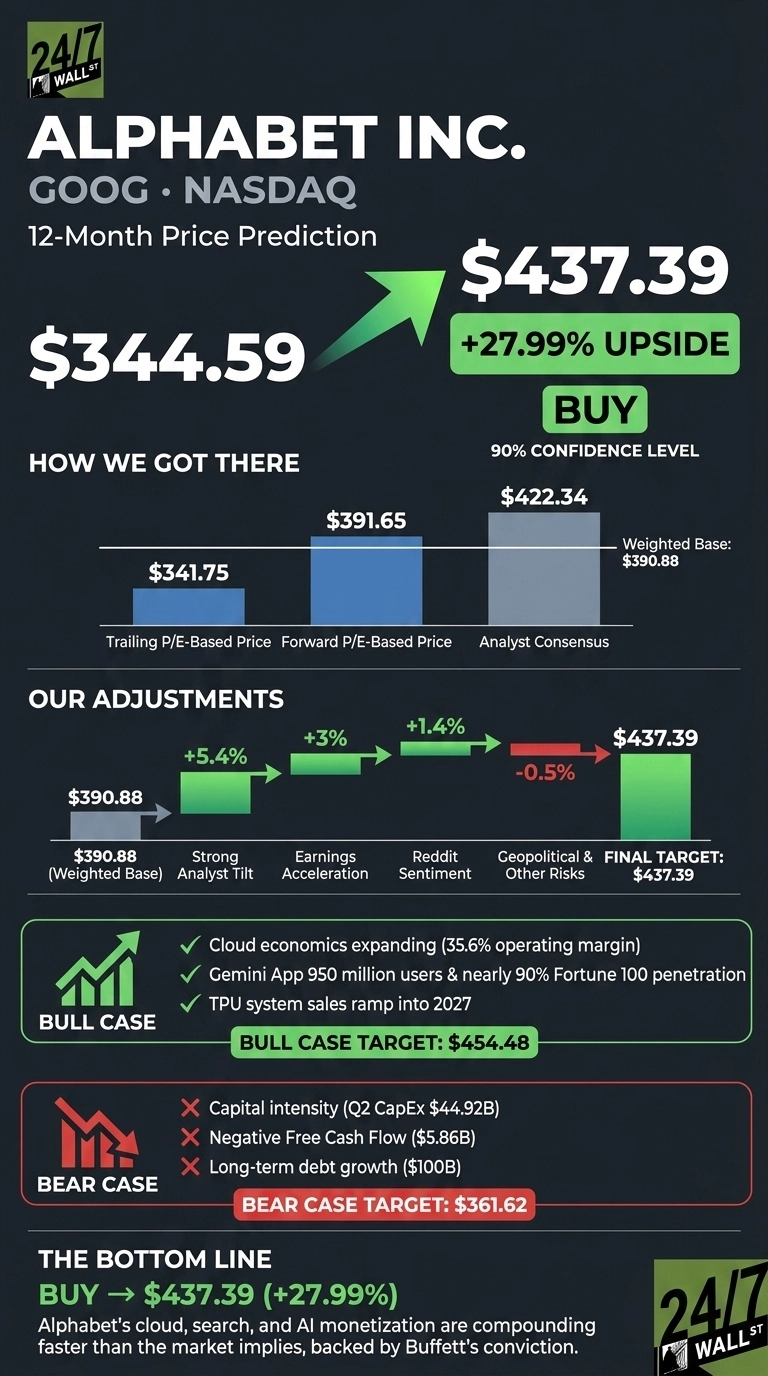
Our 24/7 Wall St. price target for Alphabet is $437.39 over the next 12 months, implying 27.99% upside. We rate GOOG a buy with high (90%) confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $344.59 |
| 24/7 Wall St. Price Target | $437.39 |
| Upside | 27.99% |
| Recommendation | BUY |
| Confidence Level | 90% |

What Alphabet’s Post-Earnings Melt-Up Tells Us
GOOG has climbed 7.99% in the past month and 67.17% over the past year, though shares sit below the $404.23 52-week high.
The catalyst was a landmark Q2. Alphabet posted EPS of $9.11 against a $3.042 estimate, and revenue of $119.8 billion, up 24.23% year over year. Google Cloud accelerated to 82% growth and backlog swelled to $514 billion. Buffett’s disclosure validated the view that even at a $4 trillion market cap, GOOG trades at a reasonable multiple relative to its cash-generation engine.

Why Bulls See a Breakout Ahead
The bull case rests on cloud economics. Google Cloud operating margin expanded from 20.7% to 35.6% year over year, and management said just over 50% of that $514 billion backlog converts to revenue within 24 months.
Gemini App’s 950 million monthly users and Fortune 100 penetration of nearly 90% show Alphabet monetizing AI at scale peers cannot yet match. Our bull scenario puts GOOG at $454.48 within 12 months if TPU system sales ramp as guided into 2027.

What Could Go Wrong
The bear thesis centers on capital intensity. Q2 CapEx hit $44.92 billion, free cash flow swung to negative $5.86 billion, long-term debt climbed to roughly $100 billion from $16 billion a year earlier, and the buyback was suspended.
2026 CapEx guidance of $175 billion to $185 billion is substantial, and every dollar of it flows to the power, cooling, and networking suppliers behind the data centers (we profiled seven of them in a free AI infrastructure report). Bulls counter that this reflects a supply-constrained cloud opportunity backed by contracted demand. Our bear scenario points to $361.62 if AI ROI slips.

How Alphabet Compares to Microsoft and Meta
Microsoft (NASDAQ:MSFT) is the natural cloud comparison. MSFT trades at a P/E of 27 with a P/FCF of 54, versus GOOG’s leaner trailing multiple. Azure crossed $100 billion in annual revenue and Copilot passed 30 million paid seats, but investors already pay a premium for that.
Meta Platforms (NASDAQ:META) is the ad-market comparable. META carries a P/E of 20 and Q2 revenue growth of 27.96%, but its Q2 EPS missed by 14.42% and free cash flow collapsed to $784 million. Alphabet’s advertising engine grows at similar rates with cleaner monetization. Against this peer group, our 24/7 Wall St. price target looks reasonable.
| Company | P/E | Q2 Revenue Growth |
|---|---|---|
| Alphabet | 17 | 24.23% |
| Microsoft | 27 | 17.75% |
| Meta | 20 | 27.96% |
Alphabet Price Prediction 2026-2030
The 24/7 Wall St. price target of $437.39 with 90% confidence reflects a company where cloud, search, and AI monetization compound faster than the multiple implies.
The setup strengthens if Google Cloud sustains 60%-plus growth and TPU revenue ramps in 2027. It weakens if CapEx keeps outpacing operating cash flow into next year. On balance, Buffett’s conviction and the numbers align.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $369 |
| 2027 | $453 |
| 2028 | $548 |
| 2029 | $614 |
| 2030 | $658 |
These projections assume Alphabet continues executing on cloud, search AI integration, and Waymo scaling. Meaningful upside or downside could result from an AI infrastructure ROI shock or a regulatory outcome in the Search antitrust remedy phase.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.