Oracle Is Trucking In Natural Gas to Keep Its AI Data Centers on Schedule
Oracle's AI data centers are running behind on pipelines and permits, so the company found an unusual workaround to keep construction on schedule and avoid penalties on hundreds of billions in signed contracts.

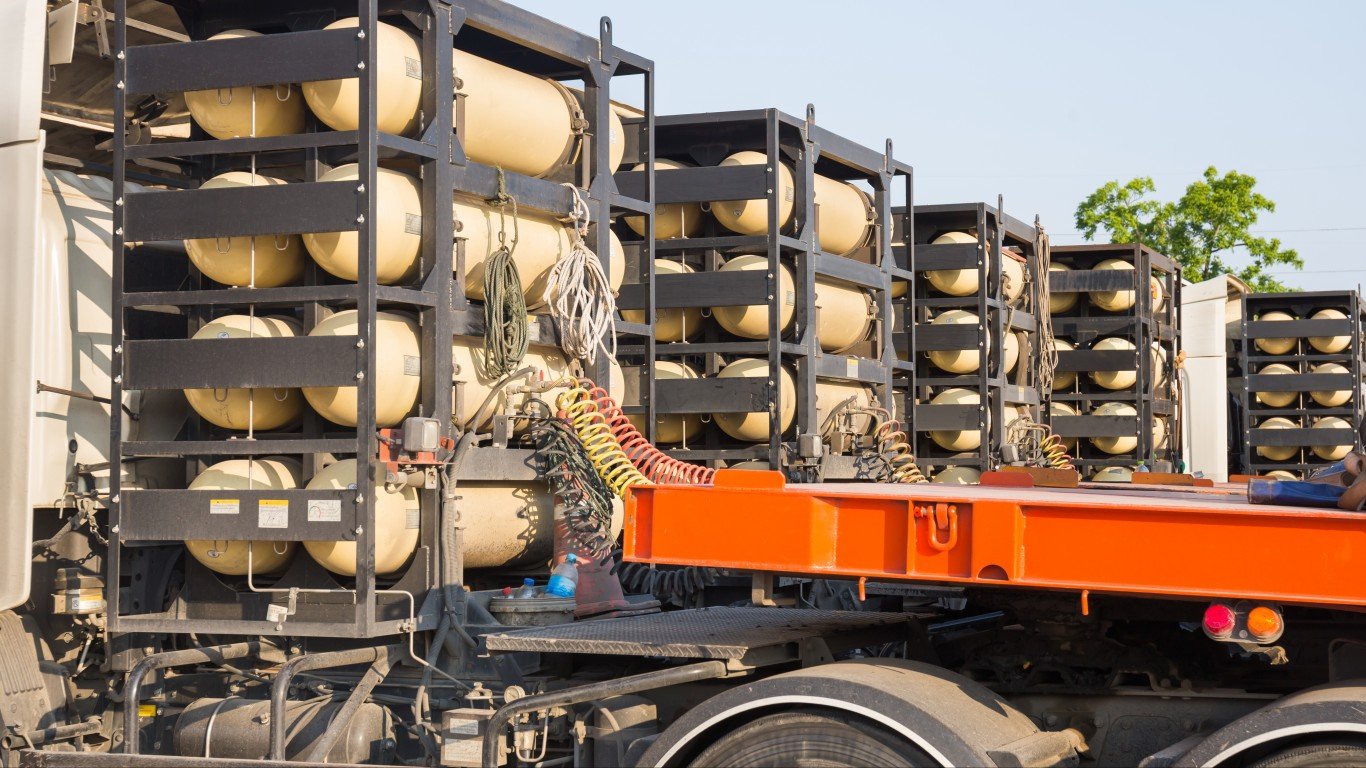
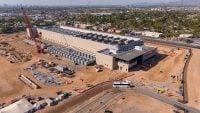
For more than a year, a data center outside Salt Lake City ran on natural gas that arrived by truck. The pipeline meant to feed it was still being built. Oracle (NYSE:ORCL | ORCL Price Prediction) now uses or is considering the same solution at three sites.
The stock closed at $141.40. The average analyst target is $237.97, which implies about 68% upside.
A gap above 40% means Wall Street and the market disagree about something basic. Oracle’s signed contracts show plenty of demand for its AI capacity, so investors are asking whether Oracle can deliver it all on time.
Pipelines, utility interconnection queues and state land offices each run on their own calendars. Oracle’s customer contracts carry fixed delivery dates.
Trucked gas is what that mismatch looks like in practice. With shares about 56% below their high of the past year, the market is pricing in the risk that the calendars never line up.
How a Virtual Pipeline Keeps Oracle’s AI Campuses Powered
A data center needs firm power before it can serve a single customer, and on-site gas turbines or fuel cells can supply that power once gas arrives.
If a pipeline is unfinished or a right-of-way is refused, developers haul compressed gas in by trailer, a practice the industry calls a virtual pipeline. Certarus supplied the gas in Utah, and VoltaGrid trucks are powering early work at the OpenAI campus in Shackelford County, Texas.
Project Jupiter in New Mexico is the third case. The state land office twice refused rights-of-way for the Energy Transfer pipeline, pushing its start to February. Oracle is considering trucked gas for the 2.45-gigawatt campus. The schedule slipped, and Oracle publicly thanked its supplier with a post reading “Shoutout to the Voltagrid team for finding cost-effective power solutions.”
Paying a Steep Fuel Premium to Hit Contract Dates
Jack Weixel estimates that trucked gas costs roughly four times the price of gas at a major pipeline hub once delivered. Ellie Holbrook estimates that at an assumed 100-megawatt load at Jupiter, one large trailer would supply about 40 minutes of electricity.
Even a small part of the planned campus would therefore need a steady stream of trucks. Oracle accepts that cost because missing an agreed delivery date on a hyperscale deal risks penalties and delayed revenue that would likely exceed the fuel bill.
Oracle’s force majeure notice to the Jupiter developer in late September shows the strain more clearly. The clause exempts obligations interrupted by events outside a party’s control, although Oracle says Jupiter remains on schedule for 2028.
A $664 Billion Backlog Spends Before It Earns
Remaining performance obligations, meaning revenue under agreements that Oracle has not yet earned, reached $664 billion, up $209 billion from a year earlier. Oracle has to spend on capacity before it can book revenue from that backlog. Revenue rose 30% to $19.3 billion in the fiscal first quarter, and cloud infrastructure revenue grew 121% to $7.4 billion.
Capital spending reached $28 billion in the quarter, and free cash flow was-$5 billion. Management expects $90 billion to $95 billion of capital spending this fiscal year.
Total debt stands at $169.14 billion. With that much debt, a delayed campus or a major customer renegotiating would leave Oracle little room to take the hit.
Mizuho Sees $320 While Yorkville Ives Waits for Proof
Mizuho named Oracle a top pick for October with a $320 target, more than double the current price. Yorkville Ives started coverage in line with a $155 target, roughly 10% above the close. The firm said it is “staying on the sidelines until the company shows it can execute a build of this scale.”
Coverage leans bullish, with 7 Strong Buy, 28 Buy, 7 Hold and 1 Sell ratings. Price targets are estimates of how well Oracle will execute, so they carry no guarantee.


Last Thursday, the shares fell 5.48% to $135.69 as AI stocks generally dropped after a report on OpenAI’s revenue. They rose 4.59% the next session. Year to date, Oracle is down 26.49%, while the S&P 500 is up 14.17%.
Delivery Risk Outweighs Oracle’s Cheap Multiple
A forward earnings multiple of about 18 looks cheap. But free cash flow is negative, debt is heavy, and the delivery schedule depends on permits and pipelines that Oracle doesn’t control.
The lower target looks wrong. If the Jupiter pipeline reaches service, backlog will keep growing in the next quarterly report and free cash flow will improve as campuses ramp up. The higher target looks wrong if more sites need trucked gas or a large customer cuts back its commitments.
Microsoft (NASDAQ:MSFT) offers a useful comparison for AI demand exposure. Azure revenue grew 43% last quarter, and Microsoft produced $19.639 billion of free cash flow while spending $35.802 billion on capital projects.
That self-funding expansion is what Oracle still needs to prove it can manage, and until it does, Microsoft shows how an AI expansion can be funded with far less balance-sheet risk.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.