Broadcom is The Steady Hand The Market Keeps Discounting
Broadcom's revenue exploded while its stock sat nearly flat for a year, and that gap keeps widening every quarter. Before dismissing this as a broken trade, consider what the market may be missing about where this cash machine is actually…

I added to my Broadcom (NASDAQ:AVGO | AVGO Price Prediction) position again this week, and I’ll keep doing it every time the market marks down a business that keeps getting bigger. Shares closed at $357.31 on October 13, up just 0.91% over the past year. Over that same stretch, third-quarter fiscal 2026 revenue grew 85.5% year over year to $29.59 billion. That gap explains every share I’ve bought.
Broadcom designs the custom AI chips that Google (NASDAQ:GOOGL), Anthropic, OpenAI and Meta Platforms (NASDAQ:META) build around their own models. It sells the Ethernet switches that wire those clusters together. It runs a VMware software business that brings in recurring cash. Then it pays me to wait. For a retirement account, I want exactly that mix: AI growth, a dividend that keeps rising and a management team that treats cash as shareholder money.
Cash Flow Strong Enough to Fund Growth, Debt Paydown and Dividends
Free cash flow reached $13.67 billion last quarter, or 46% of revenue. Out of that cash, Broadcom paid $3.1 billion in dividends and repaid $5.6 billion of long-term debt. After the quarter closed, it retired another $1.5 billion of senior notes. The remaining fixed-rate debt totals $59.6 billion at a 4% weighted-average coupon, with 7.4 years to maturity. A capital structure like that can take a weak quarter without putting the payout at risk.
The payout keeps climbing. The December 2025 raise to $0.65 per quarter was the fifteenth consecutive annual increase since fiscal 2011. At today’s price, the forward yield works out to about 0.73%. That looks thin until I remember how consistently this board raises it. The earnings behind it have beat EPS estimates for 10 straight quarters, most recently $3.32 against a $3.24 estimate.
Custom Chips Are Driving Broadcom’s Explosive AI Growth
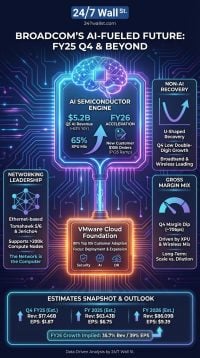
AI semiconductor revenue hit $16.70 billion in Q3, up 221%. Q4 guidance calls for $21.7 billion, up 236%. Management expects AI revenue of roughly $115 billion in fiscal 2027 and $230 billion in fiscal 2028. Google signed a long-term agreement covering future TPU generations, and management expects that deal to deliver multi-tens of billions of dollars of TPUs annually. Hock Tan put the economics simply: customers “can do all this at half the cost of a GPU.” Software adds stability. Infrastructure Software revenue rose 29% to $8.8 billion at a 94% gross margin.
Why My Money Skips NVIDIA and AMD
NVIDIA (NASDAQ:NVDA) is the default pick, and it trades near 46 times earnings. It only lifted its quarterly dividend from $0.01 to $0.25 in May 2026. I want an income record built over fifteen years of raises. Advanced Micro Devices (NASDAQ:AMD) trades near 228 times earnings and declared no dividend in its recent reports. Its latest quarter produced $1.558 billion of free cash flow, while Broadcom generated $13.67 billion.
Concentration Risk Is Real, and I Still Hold
A few of frontier labs drive this story. Tan said “the vast majority of compute demand for AI workloads today originates from this concentrated group”, and he expects Anthropic to become Broadcom’s largest XPU customer in 2027. Broadcom also built a financing platform with Apollo and Blackstone and may provide modest residual-value guarantees, which means a lab stumble could reach Broadcom’s balance sheet. Sentiment is weak too. Chip stocks dropped this week after Tan’s “casino” comment about AI investors, and the stock fell 12.59% on the day of its Q2 earnings report despite beating estimates.
I accept that risk because these customers sign multi-generation deals, the debt keeps shrinking and the dividend used $3.1 billion of $13.7 billion in quarterly free cash flow.
What Could Drive Broadcom’s Next Leg Higher
Q4 guidance calls for $34.8 billion in revenue, up 93%, with operating margin near 66%. Management also says it is on target to exceed $30 in earnings per share in fiscal 2028. The next earnings report lands December 9, 2026. The market keeps dismissing the steady hand, and I keep collecting that discount, one dividend and one share at a time.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.