Home Depot Stock: One Big Catalyst Could Change Its Outlook
Home Depot beat earnings and still lost a quarter of its value from its 52-week high, and analysts say one overlooked catalyst sitting outside the company's control could flip that story fast.

Home Depot (NYSE:HD | HD Price Prediction) trades at $292.62, and our 24/7 Wall St. Price Target of $357.14 points to 22.05% upside over the next 12 months. Our model rates the stock a buy with high confidence.
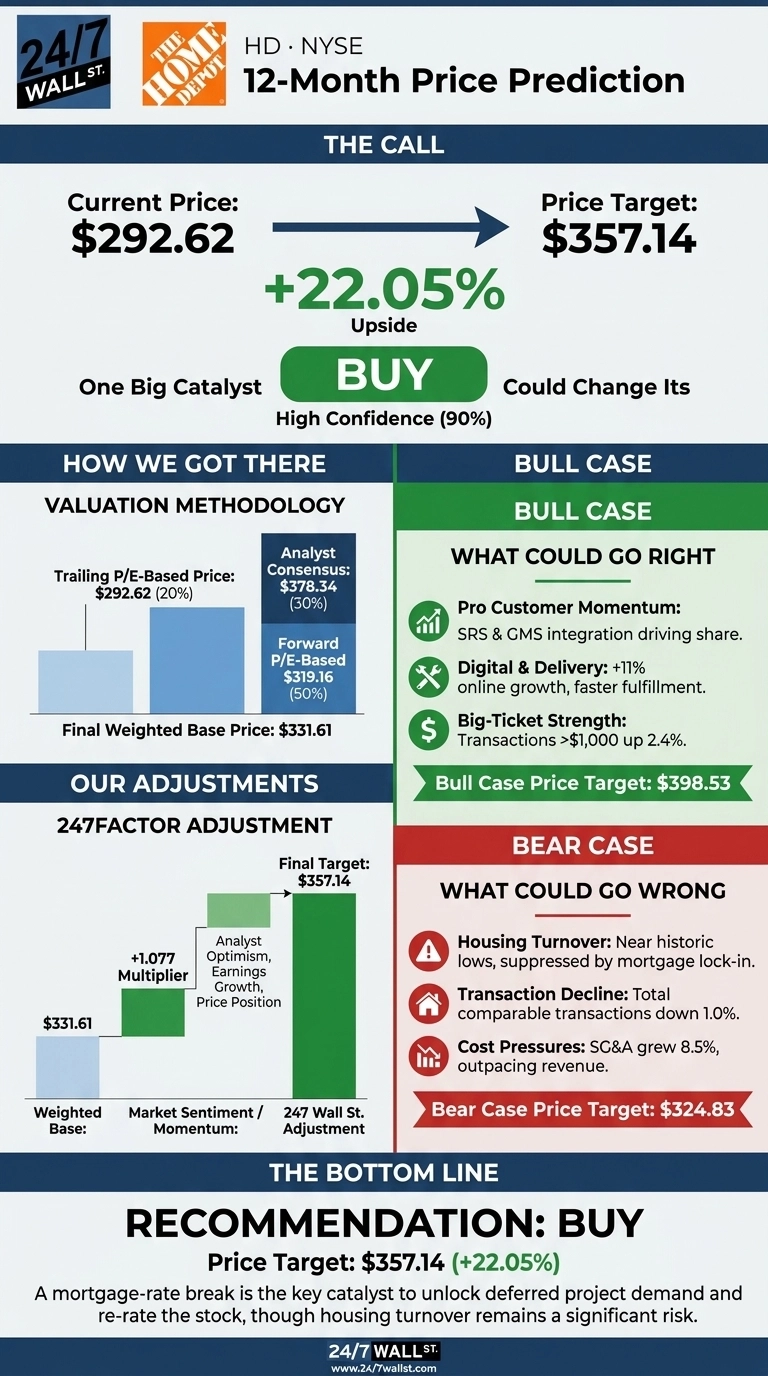
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $292.62 |
| Price Target from 24/7 Wall St. | $357.14 |
| Upside/Downside | 22.05% |
| Recommendation | BUY |
| Confidence Level | 90% |

The whole setup hinges on housing turnover. CFO Richard McPhail said in August that turnover “has never been lower as a percentage of the housing stock.”
A sustained break in mortgage rates is the one catalyst that could free up deferred projects and re-rate the stock.
Shares Slide Despite a Clean Earnings Beat
Home Depot is at $291.14 intraday, up 1.55% over the past week but down 5.7% over a month, 15.61% quarter to date and 13.54% year to date. That leaves shares roughly 25% below the $389.18 52-week high and about 5% above the $277.15 low. On Tuesday, the stock outperformed competitors on a strong trading day, MarketWatch reported.
The selloff came after solid results. Q2 revenue rose 5.7% to $47.86 billion, exceeding the $47.24 billion estimate, and adjusted EPS of $4.92 beat the $4.73 consensus.
Comparable sales grew 1.7%, accelerating to 2.3% in July. Management reaffirmed guidance for adjusted EPS growth of flat to +4%.
Why Bulls See $398 if Rates Break
The bull case is $398.53. McPhail noted that when turnover hits roughly 3% of housing stock, “it’s always bounced up relatively quickly.”
Also, SRS is posting comparable sales above the company average, digital sales rose 11%, and big-ticket transactions above $1,000 grew 2.4%. Wall Street’s consensus target is $379.75, with 21 Buy or Strong Buy ratings and no Sells.

Risks That Could Stall the Rebound
McPhail also admitted “there’s just no sign of an inflection point at this moment.” Existing home sales of 3.99 million remain down 2.2% year over year, transactions fell 1%, and SG&A grew 8.5%.
Our bear case is $324.83. Bulls would counter that high costs reflect the GMS and SRS build-out aimed at capturing pro share.

How Home Depot Compares to Lowe’s and Floor & Decor
Lowe’s (NYSE:LOW) is the direct big-box rival. It trades at 16x earnings versus Home Depot’s 21x, but Q2 comps rose just 0.2% and guidance was narrowed to flat comps. Stronger execution justifies Home Depot’s premium.
Floor & Decor (NYSE:FND) is the most rate-sensitive comp, with management mentioning high mortgage rates. Comps fell 2.1%. Relative to both peers, our target looks reasonable.
| Company | Q2 Comp Sales | FY26 Comp Guide |
|---|---|---|
| Home Depot | +1.7% | Flat to +2.0% |
| Lowe’s | +0.2% | Flat |
| Floor & Decor | -2.1% | -4.0% to flat |
Rates Hold the Key to Re-Rating
Our 24/7 Wall St. price target of $357.14 has a buy rating at 90% confidence. Even our bear case is above today’s price.
The case strengthens if mortgage rates step down and turnover rises. It weakens if transactions keep shrinking and SG&A outpaces sales into fiscal 2027.
Here is where our model projects Home Depot could trade, assuming current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $296.60 |
| 2027 | $358.42 |
| 2028 | $415.11 |
| 2029 | $453.57 |
| 2030 | $499.89 |
These estimates assume continued execution on the pro and digital strategy. A housing recovery could drive significant upside, while extended mortgage lock-in creates the main downside risk.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.