Home Depot Just Updated Its Full-Year Outlook. Here’s the Price Target to Watch

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
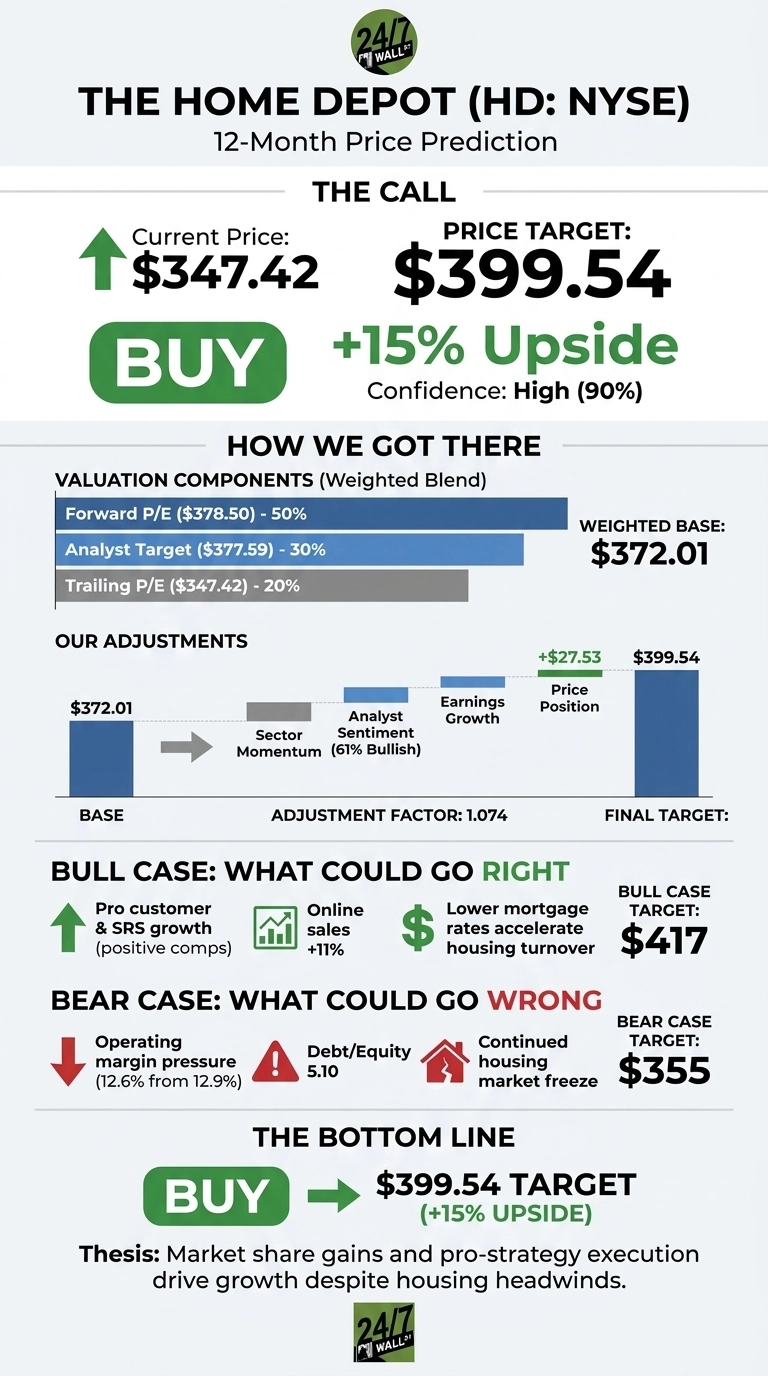
Our 24/7 Wall St. price target for Home Depot (NYSE:HD | HD Price Prediction) is $399.54. That means 15% upside from the model’s reference price of $347.42. The model rates the stock a buy with high conviction.
| Metric | Value |
|---|---|
| Current Price | $347.42 |
| Price Target from 24/7 Wall St. | $399.54 |
| Upside/Downside | 15% |
| Recommendation | BUY |
| Confidence Level | 90% |

Home Depot reported third-quarter results before the open this morning, raised its full-year sales outlook, and named Richard McPhail CEO effective November 23, 2026[1]. Shares traded at $341.89 premarket, down 1.62%. Our target also sits above the Street consensus of $377.59.
A Q3 Beat and a Higher Sales Outlook Set Up the Next Leg
Revenue came in at $43.398 billion, ahead of the $42.78 billion estimate and up 4.95% year over year. Adjusted EPS of $3.86 beat the $3.838 consensus. Comps rose 2.2% because customers spent more per visit: average ticket climbed 3% to $93.09 while transactions slipped 0.5%.
Management now expects fiscal 2026 sales growth of about 4.5%, the top of the prior 2.5% to 4.5%[2] range. It narrowed adjusted EPS growth to about 2% off a $14.69 base.
The stock gained 10.42% over the past month. It is down 3.26% for the week and up 1.53% year to date. Its 52-week range runs from $277.15 to $389.18. McPhail said “Results in the third quarter exceeded our expectations.”

Why Bulls See $417 Within Reach
The bull case hits $416.99, driven mostly by pro customers. In Q2, SRS comped above the company average and was positive in every vertical. Management in August targeted $400 million[3] in cross-selling across SRS, GMS and the stores.
Online comps rose 11%[3]. Lower mortgage rates that loosen housing turnover could speed this up. Coverage leans positive: 4 Strong Buy, 18 Buy and 14 Hold ratings, with no Sells.

Shrinking Margins and Frozen Housing Are the Risks
The bear case comes to at $354.51. Operating margin fell to 12.6% from 12.9%, and cost of sales rose faster than revenue. Debt-to-equity stands at 5.10. On housing, McPhail said in August that “there’s just no sign of an inflection point at this moment.”[3]
Part of the margin pressure is acquisition accounting. Amortization rose to $182 million from $158 million, while interest expense fell to $579 million from $628 million.
How Home Depot Compares to Lowe’s and Floor & Decor
Lowe’s (NYSE:LOW) is the direct big-box rival. The shares trade at 17x forward earnings, versus 22x for Home Depot. Lowe’s posted Q2 comps of 0.2% and cut its full-year comp outlook to flat. Barron’s also reported a downgrade to Sell. Home Depot’s share gains help support its premium.
Floor & Decor (NYSE:FND) offers a contrast on growth. The shares trade at 33x forward earnings even though Q3 comps declined 1.4%, because new stores drive its expansion. Taken together, the peer multiples place Home Depot between Lowe’s and Floor & Decor on forward earnings.
| Company | Forward P/E | EV/EBITDA |
|---|---|---|
| Home Depot | 22x | 16.03 |
| Lowe’s | 17x | 12.98 |
| Floor & Decor | 33x | 11.61 |
Our Model Still Rates Home Depot a Buy
The 24/7 Wall St. price target of $399.54 carries a buy rating with 90% confidence. What tips the scale is taking share in a weak housing market.
I would find the stock compelling if SRS keeps rose faster than the core business and comps hold above 1.4%. I would rose cautious if transactions keep falling and margins fall below 12.4%. For now, those are the signs that support the model’s buy rating.
The table below extends the 24/7 Wall St. price target model, assuming current growth patterns and market conditions remain.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $351.29 |
| 2027 | $405.59 |
| 2028 | $448.14 |
| 2029 | $486.22 |
| 2030 | $516.98 |
The estimates rest on Home Depot continuing to execute on its pro strategy. A housing recovery could drive results higher, while a longer housing freeze would drag them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.