Home Depot Stock Could Be Poised for a Turnaround. Here’s How High It Could Go
Home Depot just posted a quarter that beat expectations, but the housing market remains frozen at historical lows and shares are still in the red for the year. Whether those two forces collide or cancel each other out shapes everything…

Home Depot (NYSE:HD | HD Price Prediction) gained 14.37% over the past month, and our model expects the rebound to continue. The 24/7 Wall St. price target for Home Depot is $386.52 over the next 12 months. That implies 17.5% upside and supports a buy rating, which our model gives with high confidence.
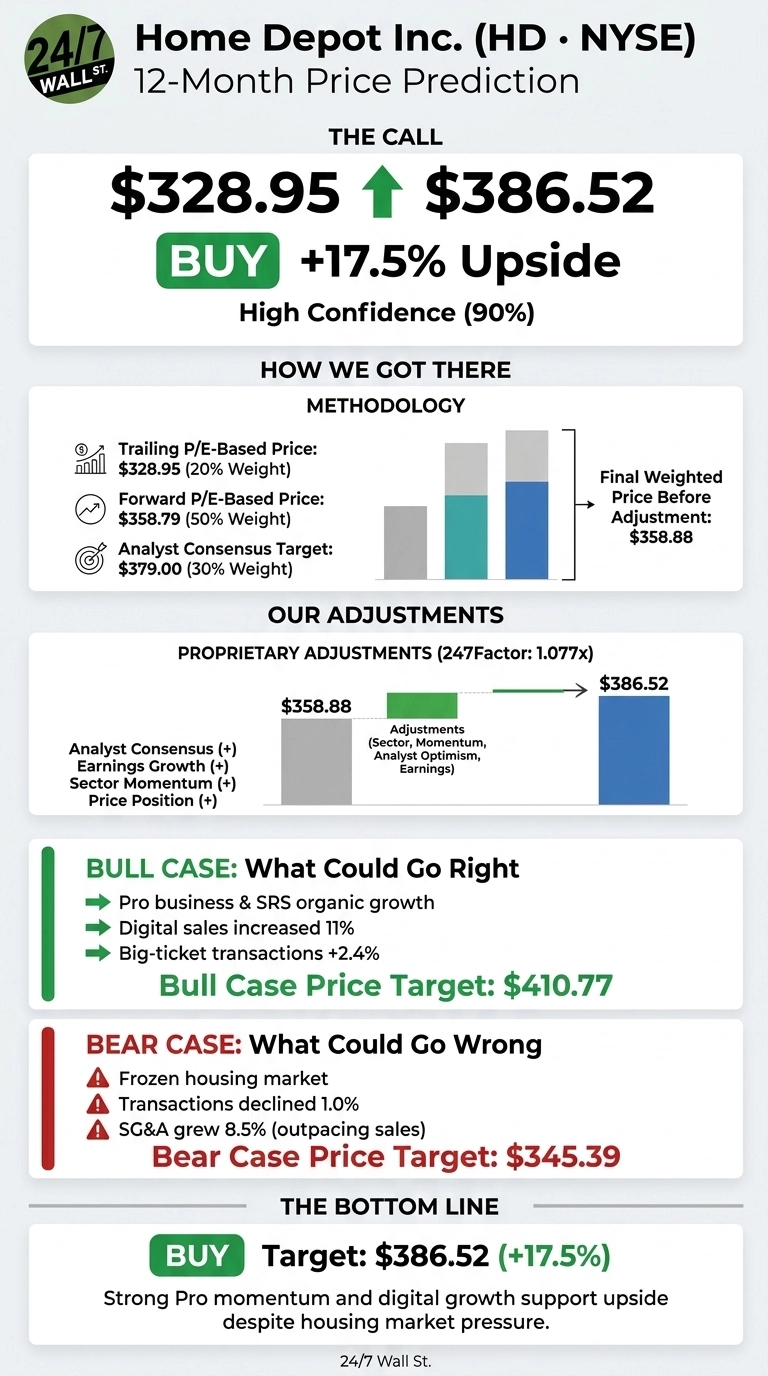

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $328.95 |
| Price Target from 24/7 Wall St. | $386.52 |
| Upside/Downside | 17.5% |
| Recommendation | BUY |
| Confidence Level | 90% |
Home Depot has been stuck in a housing freeze for years, so the timing matters. Earnings are beating estimates and management kept its full-year outlook in place. Shares are still down 2.17% year to date. That leaves room for the stock to rise if demand holds.
October Rally Follows a Second-Quarter Beat
The stock rose 0.52% over the past week but remains down 10.37% over one year. Shares sit 15.5% below the 52-week high of $389.18 and 18.7% above the low of $277.15. On Thursday, Home Depot outperformed competitors.
In the second quarter, revenue rose 5.71% to $47.861 billion, ahead of estimates. Adjusted EPS of $4.92 beat the $4.7326 consensus. Comparable sales grew 1.7%, and management maintained its fiscal 2026 guidance.
Why Bulls See $410 and Beyond
The pro business is the main growth engine. On the call, management said “SRS comped above the company average this quarter” and guided to mid-single-digit organic growth at SRS. Digital sales rose 11%, and big-ticket transactions over $1,000 grew 2.4%.
Wall Street is positive: 4 analysts rate the stock Strong Buy, 17 rate it Buy, and none rate it Sell. If mortgage rates ease, the upside scenario points to $410.77.

Frozen Housing Is the Risk Worth Watching
Management called housing turnover “at historical lows” and said there is “no sign of an inflection point at this moment.” September housing starts dropped 5.2% to 1.22M. SG&A grew 8.5%, faster than sales.
Bulls would argue that spending is funding delivery and SRS capabilities that are already winning market share. Higher fuel and energy costs are expected to cancel out $730 million in tariff refunds. The downside scenario lands at $345.39.

Home Depot Commands a Premium Over Lowe’s and Floor & Decor
Lowe’s (NYSE:LOW) is Home Depot’s direct rival. Lowe’s trades at about 17x trailing earnings, compared with 23x for Home Depot, and offers a 6.58% free cash flow yield versus 3.85%. However, Lowe’s cut its comp outlook to flat, while Home Depot held its range. That difference in momentum helps justify Home Depot’s premium.
Floor & Decor (NYSE:FND) shows how weak big-ticket remodeling demand has been. It guides to fiscal 2026 comps of (3.5)% to (2.0)%. Against both peers, our target looks reasonable.
| Company | Latest Quarter Comps | Fiscal 2026 Comp Outlook |
|---|---|---|
| Home Depot | +1.7% | Flat to +2.0% |
| Lowe’s | +0.2% | Flat |
| Floor & Decor | -1.4% | (3.5)% to (2.0)% |
Turnaround Tilts in Home Depot’s Favor
Our 24/7 Wall St. price target of $386.52 carries a buy rating with 90% confidence. What tips the scale is that Home Depot is winning share even with housing frozen.
The bull case improves if comps stay positive and SRS keeps growing faster than the core business. The bear case winning weight if transactions fall further or higher costs push margins down. On balance, our model weighs the upside more heavily than the downside.
Home Depot Price Prediction 2026-2030
Here is where our model projects Home Depot could trade if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $339.01 |
| 2027 | $386.52 |
| 2028 | $431.82 |
| 2029 | $481.35 |
| 2030 | $507.96 |
They rest on Home Depot continuing to execute its current strategy. A recovery in housing turnover could push the stock well above these levels, while a extended freeze could pull it below them.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.