Nvidia and Broadcom Narratives Define the AI Chip Landscape
NVIDIA doubled its revenue while Broadcom grew AI chip sales 221%, yet the two companies are betting on completely opposite visions of who actually controls the future of AI computing.


Within a week of each other, NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) and Broadcom (NASDAQ:AVGO) reported, and the two calls made opposing cases. NVIDIA posted $96.22 billion in revenue, which more than doubled year over year. Broadcom grew AI semiconductor revenue 221% by building custom chips for frontier labs. NVIDIA sells the whole AI factory. Broadcom designs chips meant to replace the factory’s core.
Full Racks Carry NVIDIA. Custom Silicon Carries Broadcom.
NVIDIA’s Data Center revenue reached $89.02 billion, up 117%. Networking grew even faster, at 138%, which tells me customers want complete systems connected together. Jensen Huang summed it up: “Now, compute is revenue.” Vera Rubin orders came from “every major hyperscaler, AI cloud, and system OEM.”
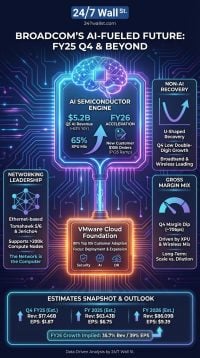
Broadcom’s pitch is narrower. XPUs made up 73% of AI revenue, and Hock Tan argued that a co-developed chip “will outperform any GPU.” Management claims custom XPUs match GPU performance at half the cost. Since that claim comes from the supplier, I discount it somewhat. VMware adds stability: Infrastructure Software grew 29% to $8.75 billion, a recurring revenue stream NVIDIA lacks.

| Business Driver | NVIDIA | Broadcom |
|---|---|---|
| Growth Engine | Blackwell Ultra, Vera Rubin systems | Custom TPUs, MTIA, Jalapeno |
| Next-Quarter Guide | $108.0B revenue | $21.7B AI revenue |
| Customer Reach | Clouds, governments, enterprises | Six XPU customers |
Six Customers Versus Every Cloud
To disrupt NVIDIA, Broadcom has to turn a few design wins into gigawatts of deployed computing power. That roadmap exists. Anthropic plans five gigawatts of TPU v8i in 2027, and OpenAI plans 1.3 gigawatts of Jalapeno. Management projects about $115 billion of fiscal 2027 AI revenue. Customer concentration is the weak point. Tan said most computing demand comes from a “concentrated group” of leading model builders.
Huang’s response is that XPUs are “inference-specific chips for one cloud or one service,” while NVIDIA runs “in every cloud.” Still, NVIDIA says it has supply for only about 70% of demand, and memory costs are driving Q4 gross margin down to 71% to 72%. Each order NVIDIA can’t fill gives Broadcom an opening.
Vera Rubin’s Ramp and AI Debt Are the Next Tests
Whether Vera Rubin reaches about 20% of Q3 data center revenue is worth watching. For Broadcom, keep an eye on Meta’s MTIA shipments in the Q4 report due December 9. Financing is a risk for both. Each company relies on Apollo and Blackstone vehicles to fund lab buildouts, and worries about AI debt at NVIDIA-backed CoreWeave hit chip stocks. On October 14, NVIDIA fell 3.16% and Broadcom fell 3.1%, which shows both stocks depend on the same credit cycle.
Why I Lean Toward Broadcom as the Disruptor
NVIDIA is up 18.94% year to date. Broadcom is up just 0.59%, even though its AI chip revenue is growing faster. At a forward P/E near 19x, Broadcom’s valuation assumes less about its roadmap. To me, that makes it the more interesting way to follow the disruption story.
Investors who want breadth may find NVIDIA sturdier, with CUDA behind it and a presence in every major cloud. The chipmakers are only half the AI capex story, though; the power, cooling, and networking suppliers behind the data centers are the other half, and we covered seven of them in a free report here. My view would change if the Anthropic or OpenAI deployments slip, because Broadcom’s whole case depends on six customers.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.