POET Technologies Could Be Sitting on a Much Bigger Opportunity Than Investors Realize
POET Technologies has already swung hundreds of percent in a single month, and Wall Street sees even bigger moves ahead as the company races to prove its silicon optical interposer can handle the pressure of real purchase orders and AI-scale…

POET Technologies (NASDAQ:POET) builds a silicon optical interposer, a platform that combines electronic and photonic devices into a single chip-scale package assembled at wafer scale on standard semiconductor equipment.
Management has said the technology could “become a de facto integration standard in the photonics industry.” In 2026, that pitch began turning into purchase orders. CEO Suresh Venkatesan described late 2025 as “a decisive transition from development to execution.”
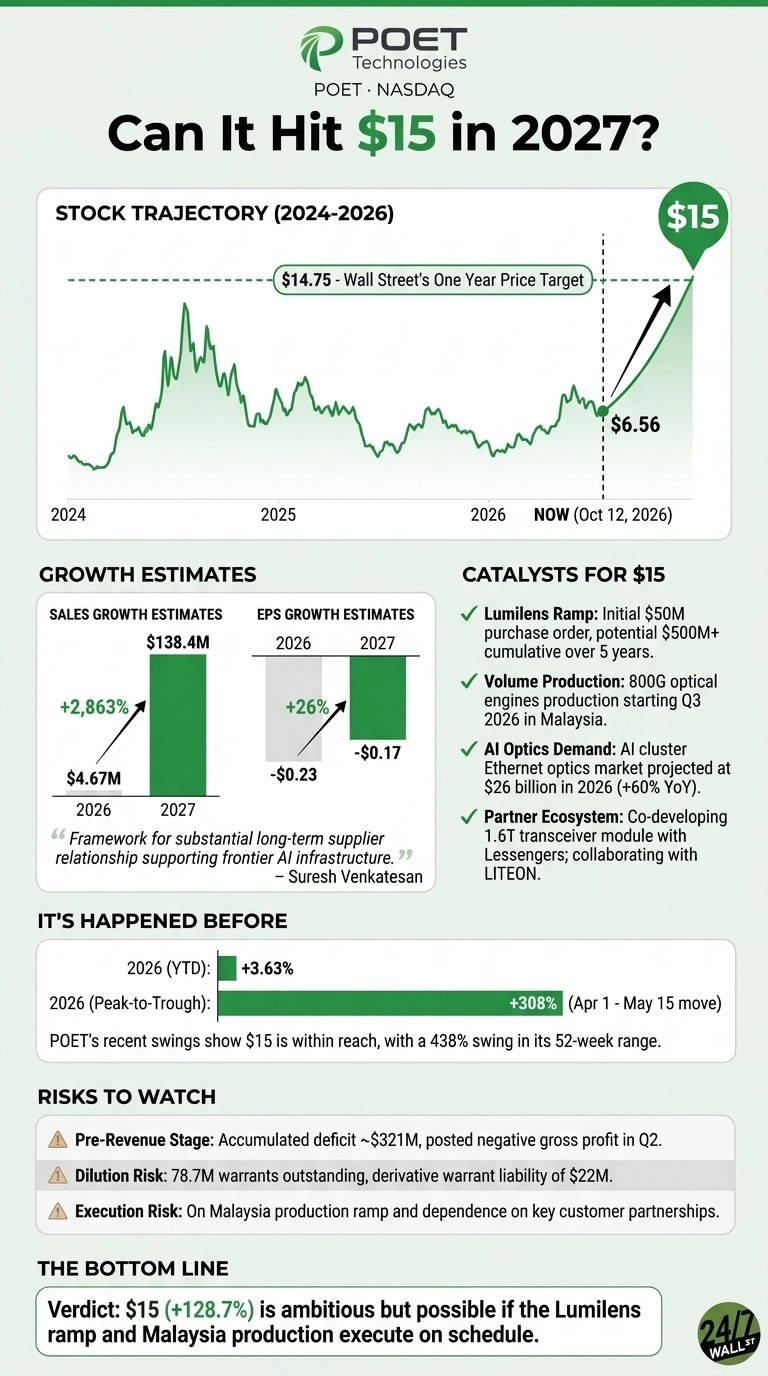
The stock has been far choppier. POET is up 3.63% year-to-date at $6.56, but it is down 18% over the past month after hitting a 52-week high of $20.81. With roughly $796M in cash and short-term investments, let’s look at what POET needs to accomplish to reach $15 in 2027.
Wall Street Already Sees the Stock More Than Doubling
The consensus price target stands at $14.75, indicating 124.8% upside. Coverage is thin (estimates come from one analyst), and revenue is expected to climb from $4.67 million in 2026 to $138.4 million in 2027. The 2026 EPS estimate improved from -$0.24 to -$0.23 over the past 30 days.
POET’s record against estimates is mixed. Revenue exceeded estimates by 44.66% in Q1 2026 but fell short in the other recent quarters, while Q2 EPS of -$0.07 matched expectations.
Here’s What It Takes for POET to Reach $15
With no profits yet, price-to-sales is the right metric. Today POET trades at about 8x its 2027 revenue estimate. At $15, its market cap would be roughly $2.6 billion, or about 19x 2027 sales. That is a premium multiple, but a cash pile that covers a large slice of the current valuation supports it.
What Could Push POET to $15?
- Lumilens ramp: An initial $50M purchase order could grow to $500M+ over five years. Venkatesan called it the framework for “a substantial long-term supplier relationship supporting frontier AI infrastructure.”
- Volume production: POET guided to more than 30,000 optical engines shipped in 2026. 800G engines enter production in Malaysia in Q3 2026, with 800G/1.6T transmit engines targeted for Q2 2027.
- AI optics demand: The AI cluster Ethernet optics market is projected at $26 billion in 2026, up about 60% year over year.
- Partner ecosystem: POET is co-developing a 1.6T transceiver module with Lessengers and collaborating with LITEON.
- U.S. redomiciliation: Moving from Canada would remove PFIC classification risk and could widen the investor base.
POET’s Recent Swings Show $15 Is Within Reach
Reaching $15 requires a 128.7% gain. Recent moves show what this stock can do. Shares ran from $5.61 on April 1 to $22.89 by May 15, a 308% move in about six weeks. The 52-week range from $3.87 to $20.81 works out to a 438% swing.
That volatility runs in both directions. POET carries an accumulated deficit of about $321M and 78.7M warrants outstanding, and it posted negative gross profit in Q2.
Is $15 Realistic? Here’s My Take
Hitting $15 would require POET to more than double in 2027. Wall Street’s target already sits just below that level, and the case depends on revenue jumping from under $5 million to more than $138 million.
If the Lumilens orders scale, Malaysia production ramps on schedule and AI optics spending keeps growing, $15 is within reach (the same data-center expansion boost we mapped across seven non-chipmaker suppliers in a free AI infrastructure report). Returns at this level shouldn’t be expected every year, but we’ve outlined the case for how POET could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.