Prediction: Poet Technologies Has 160% Upside as AI Infrastructure Demand Accelerates
POET Technologies has shed nearly half its value from a May peak, yet institutional heavyweights are quietly building stakes as a landmark supply agreement hints at a manufacturing inflection that could reshape the entire pre-revenue thesis.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
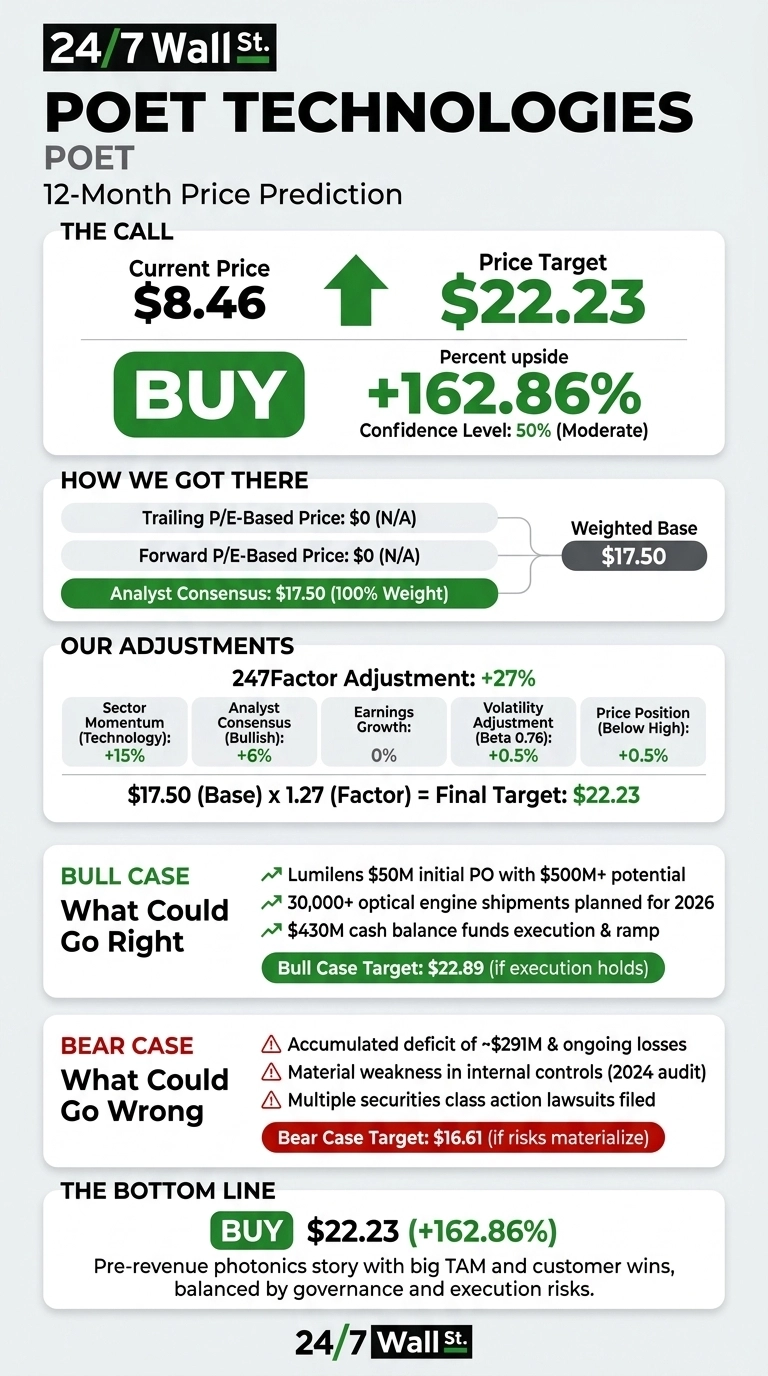
POET Technologies (NASDAQ:POET) trades at $8.46, well off its 52-week high of $20.81. Our 24/7 Wall St. price target for POET is $22.23, implying 162.86% upside over the next 12 months.
We rate the stock a buy, with a 50% confidence level. Confidence is deliberately moderate: this is a pre-revenue photonics story with a big TAM, real customer wins, and equally real governance and execution risks.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $8.46 |
| 24/7 Wall St. Price Target | $22.23 |
| Upside | 162.86% |
| Recommendation | BUY |
| Confidence Level | 50% |
From a May Blowoff to a Litigation-Driven Reset
POET is up 26.38% year to date, but shares are down 10.61% in the past week and 36.15% in the past month after peaking near $20 in May.
Q1 FY26 revenue rose 201.9% year over year to $503,389, beating estimates by 44.66%, though EPS came in at -$0.08, missing expectations. The bigger story was the Lumilens supply agreement with an initial $50 million purchase order and potential to scale beyond $500 million over five years.
Sentiment deteriorated on multiple class action filings tied to PFIC tax disclosures and the cancellation of Celestial AI purchase orders. Offsetting that, Citadel disclosed a 5.1% to 5.9% stake and Jane Street a 6.8% stake, signaling institutional conviction into the drawdown.
The Case for $22 and Beyond
The bull case rests on manufacturing conversion. Management guided to shipping more than 30,000 optical engines in 2026, with high-volume light source production in Q2 and 800G engines in Q3 from Malaysia.
CEO Suresh Venkatesan called the Lumilens deal “an important commercial milestone… establishing the framework for what we believe could become a substantial long-term supplier relationship supporting frontier AI infrastructure.”
With approximately $430 million in cash, POET is funded to execute. Exposure to a $9.8 billion 800G transceiver market by 2032 at 22.8% CAGR gives the bull scenario oxygen. Our bull case one-year target is $22.89.
What Could Go Wrong
POET carries an accumulated deficit of roughly $291 million and a material weakness in internal controls identified in the 2024 audit. Multiple securities class actions have been filed.
Bulls counter that Q4 FY25’s $42.67 million net loss was driven largely by a $30.69 million non-cash warrant fair value adjustment, a non-operating item, and the planned U.S. redomiciliation eliminates the PFIC overhang. Still, our bear case target of $16.61 assumes ramp slippage and lingering legal drag.
How POET Compares to Lumentum and Coherent
Lumentum (NASDAQ:LITE | LITE Price Prediction) is a direct optical peer and the go-to benchmark for commercial scale. Lumentum operates at meaningful commercial scale with multibillion-dollar annual revenue and positive non-GAAP EPS. Its market cap sits near $60 billion versus POET at $1.46 billion. That gap is exactly the bull thesis on POET and the execution mountain the target implies.
Coherent (NYSE:COHR) offers a valuation contrast. Coherent generates multibillion-dollar quarterly revenue, has secured a significant strategic investment from NVIDIA, and joined the S&P 500. Its scaled cash flow makes POET’s pre-revenue multiple look demanding. Against these two, our $22.23 target looks reasonable given POET’s small base and optionality on the Lumilens ramp.
POET Price Prediction 2026-2030
The 24/7 Wall St. price target for POET is $22.23, a buy rating at 50% confidence. The tipping factor is the H2 2026 Malaysia ramp: if 800G engines and light source shipments land on schedule, re-rating is likely. The setup favors accumulation on weakness if Q2 shows shipments tracking toward the 30,000-unit target. Caution is warranted if class actions escalate or redomiciliation slips.
Our model projects POET could trade if execution holds:
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $22.23 |
| 2027 | $34.00 |
| 2028 | $52.00 |
| 2029 | $78.00 |
| 2030 | $125.44 |
These projections assume POET converts its pipeline into recurring revenue and clears its governance overhang. Significant upside could come from a full Lumilens $500 million ramp; downside would follow ramp delays or dilutive capital raises.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.