One Under-the-Radar Stock With 100% Upside Potential
A small-cap silicon photonics company has quietly built a cash fortress and locked in a major anchor customer, positioning itself to compete in a $26 billion AI optics market where the giants are not paying attention yet.

Silicon photonics has become one of the most closely watched corners of the AI infrastructure trade, and POET Technologies (NASDAQ:POET) sits right at the intersection of that story.
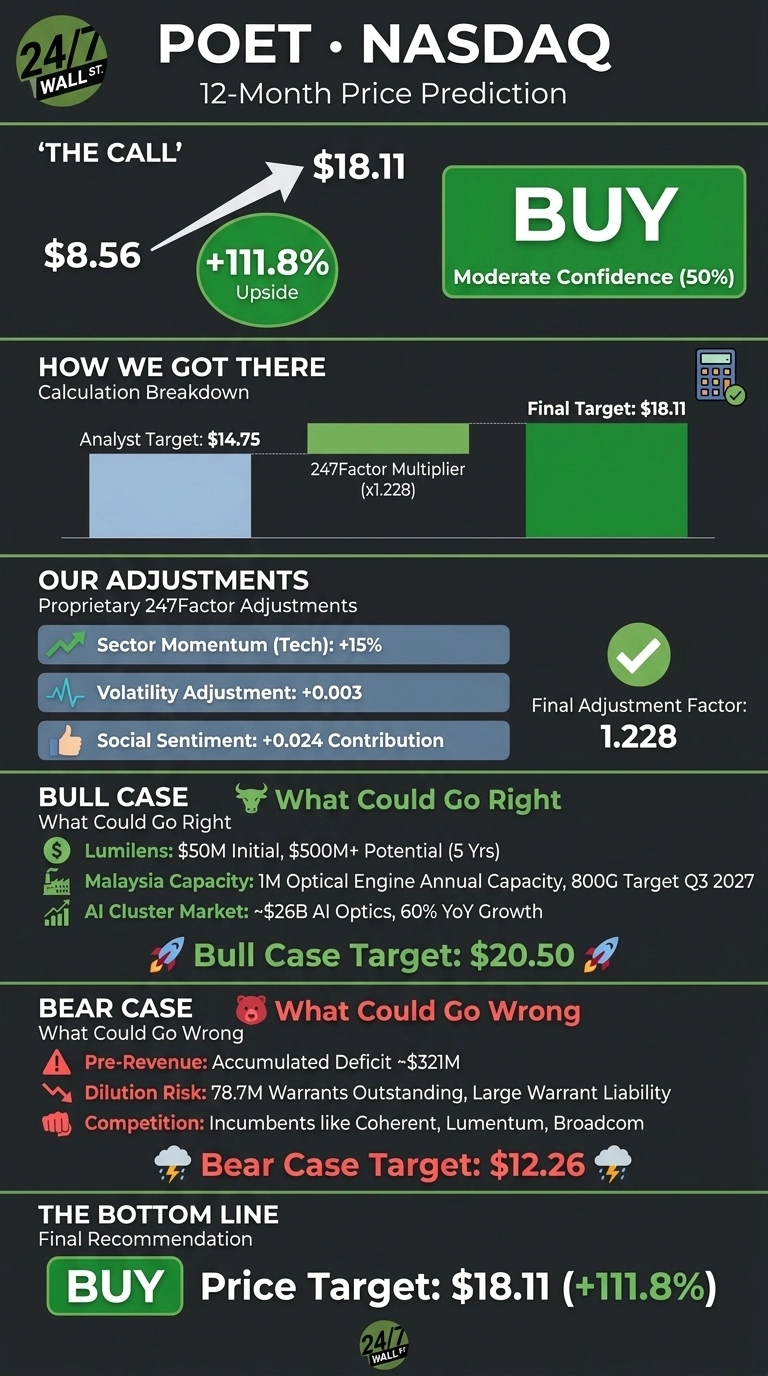
Our 24/7 Wall St. price target for POET is $18.11, versus a current price of $8.56. That implies upside of 111.8% over the next 12 months, and our recommendation is buy. Model confidence sits at a moderate 50%, reflecting the wide range of outcomes typical of a pre-revenue commercial ramp.
| Metric | Value |
|---|---|
| Current Price | $8.56 |
| 24/7 Wall St. Price Target | $18.11 |
| Upside | 111.8% |
| Recommendation | BUY |
| Confidence Level | 50% |
A Volatile Year That Ended Higher
POET has traded like a call option on AI photonics. Shares are up 63.51% over the past year and 35.23% year to date, swinging from a 52-week low of $3.87 to $20.81.
The most recent quarter, reported August 13, 2026, delivered revenue of $569,925, up 112.29% year over year but missing the $691,530 consensus. GAAP EPS of -$0.07 beat the -$0.08 estimate.
The balance sheet stands out: roughly $796 million in cash and short-term investments after a $400 million offering, against total liabilities of just $34.3 million.
Why Bulls See a Breakout Ahead
The bull case rests on commercial traction. The Lumilens supply agreement carries an initial $50 million purchase order and a potential $500 million cumulative over five years for optical engines.
Malaysia manufacturing with Globetronics targets 1 million optical engine annual capacity, with 800G production slated for Q3 2027. Collaborations with LITEON, Lessengers, NTT, and Quantum Computing position POET in the $26 billion AI cluster Ethernet optics market growing 60% year over year. Bull-case scenario projects $20.50 in 12 months if execution is clean.
What Could Go Wrong
POET remains pre-revenue at scale with an accumulated deficit of roughly $321 million and 78.7 million warrants outstanding driving dilution. The 800G production timeline slipped from Q3 2026 to Q3 2027. Competition includes Coherent, Lumentum, Marvell, and Broadcom.
Recent losses were amplified by a $30.69 million non-cash derivative warrant charge tied to CAD-denominated warrants, an issue management expects to substantially eliminate after repricing. Bear-case target is $12.26, still above today’s price.
How POET Compares to Coherent and Credo
Coherent (NYSE:COHR | COHR Price Prediction) is the incumbent competitor. It trades at a forward P/E of 31 on trailing revenue of $7.1 billion, with quarterly revenue growth of 33.7% year over year. That is the scaled version POET is trying to become.
Credo Technology (NASDAQ:CRDO) is the closer growth analog: an AI connectivity pure-play with quarterly revenue up 114.7% year over year and a forward P/E of 28. Credo already earns $2.83 in trailing EPS, the profitability inflection POET needs. Our $18.11 target prices POET as a credible AI photonics platform without requiring Credo-level margins.
| Company | Forward P/E | YoY Revenue Growth |
|---|---|---|
| POET | n/a (pre-profit) | 112.3% |
| Coherent | 31 | 33.7% |
| Credo | 28 | 114.7% |
POET Price Prediction 2026-2030
The 24/7 Wall St. price target of $18.11 with a buy rating reflects a company where the cash war chest, the Lumilens anchor customer, and the AI optics tailwind align.
The setup favors investors who can size POET as a speculative sleeve and stomach volatility. The risk profile tilts less favorable if further 800G timeline slips or another dilutive raise emerges before Malaysia production comes online.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $10.19 |
| 2027 | $18.15 |
| 2028 | $30.18 |
| 2029 | $43.87 |
| 2030 | $56.15 |
These projections assume POET executes on its Malaysia ramp, converts the Lumilens framework into recurring volume, and captures share as 800G and 1.6T pluggables scale. Significant upside or downside could result from hyperscaler design wins or additional program delays.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.