Billionaire Ray Dalio Says an AI-Fueled $4.4 Trillion Debt Crisis Is Coming
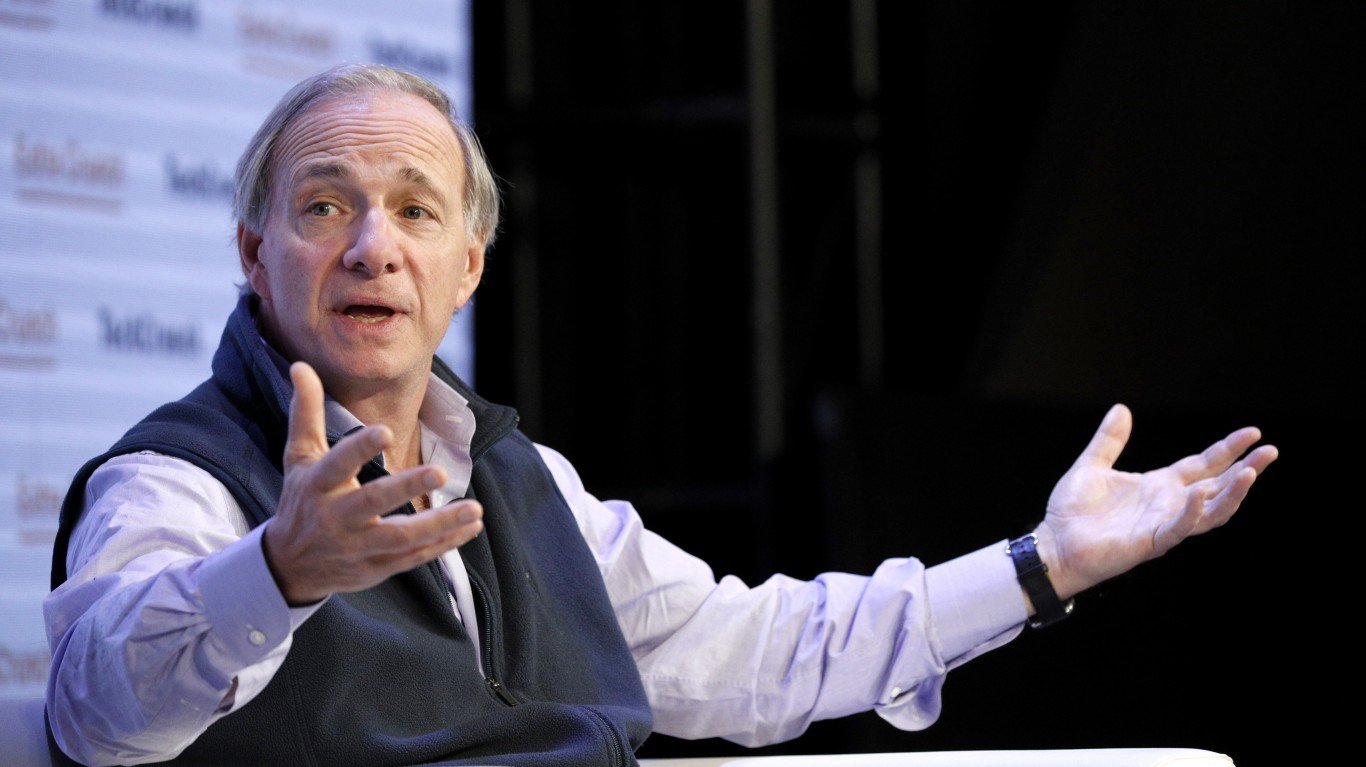
Ray Dalio sees a collision forming between Washington's appetite for debt and Silicon Valley's hunger for capital, and AI's biggest players are borrowing at a pace that could turn even their wins into losses for shareholders.


Artificial intelligence’s next obstacle may be the cost of money. Building data centers requires financing today, while the revenue needed to justify those investments arrives later. Washington also needs buyers for its debt, putting government borrowing and corporate expansion in competition for investors’ dollars.
For shareholders, that creates a risk beyond whether AI delivers useful technology: even successful businesses can become disappointing investments when financing costs consume their profits. The pressure spreading beyond the bond market could make the price of funding growth as important as growth itself.
Bridgewater Associates founder Ray Dalio warns that this competition is intensifying. His analysis deserves attention, although they describe a financing squeeze that could develop, rather than an inevitable crash.
What Ray Dalio’s $4.4 Trillion Warning Means
In a post on Tuesday over at LinkedIn, “The Numbers Behind the Bond Bear Market,” Dalio projects annual net U.S. debt supply will reach approximately $4.4 trillion in 2027, up from $3.5 trillion in 2025. That represents roughly a 26% increase.
The figure covers borrowing across the economy, not AI debt alone. It also excludes refinancing existing obligations. Separately, Dalio estimates corporations will need approximately $2 trillion to refinance debt in 2027, alongside $1.4 trillion in new borrowing.
Refinancing replaces an old loan; new borrowing adds another claim on future income. Both require willing lenders.
If buyers demand higher yields to absorb that supply, borrowers must pay more. For example, a one-percentage-point increase on $10 billion of newly priced debt adds $100 million in annual interest. That money cannot fund another data center or reach shareholders through dividends.
AI Is Making the Financing Squeeze Bigger
Dalio puts hyperscaler bond issuance at approximately $220 billion during the first half of 2026, compared with $108 billion throughout all of 2025. These giant cloud operators borrowed more than twice the prior year’s total in just six months.
The International Monetary Fund’s October Global Financial Stability Report reinforces the concern. According to Reuters, hyperscalers now account for 10% of global investment-grade bond issuance compared to less than 1% in 2024.
As AI construction consumes more cash, investors must distinguish growth financed by customers from growth sustained by repeated trips to lenders.
Supplier financing adds another complication. Broadcom (NASDAQ:AVGO | AVGO Price Prediction) just agreed to lend Anthropic up to $42 billion. Nvidia (NASDAQ:NVDA) is involved in more than $750 billion worth of similar AI investments, financing deals, and partnerships. While such chip-buying arrangements connect sales with customers’ ability to repay, it also leaves the supplier exposed if the customer struggles.
Key Takeaway
Dalio’s forecast suggests investors should be selective about the AI stocks they buy, not abandon them. Certainly, higher borrowing requirements alone do not prove lenders will retreat, as stronger earnings, productivity gains, or additional investment could help absorb the supply.
Still, investors should favor businesses that can cover expansion and interest payments from operating cash over their peers who are dependent on continual refinancing. Due diligence requires comparing cash that remains after capital spending, upcoming debt maturities, and lease commitments before treating two AI companies as equally attractive.
The technology can succeed while an expensive financing structure results in disappointing shareholders. Buying growth at any price becomes harder to defend when the interest bill keeps rising.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.