One Stock That Could Become Much More Important to AI
AI clusters live and die by the connections between their processors, and one small-cap company is quietly positioning itself to own that reliability problem across every major hyperscaler. Its stock just took a sharp hit despite record numbers, and the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
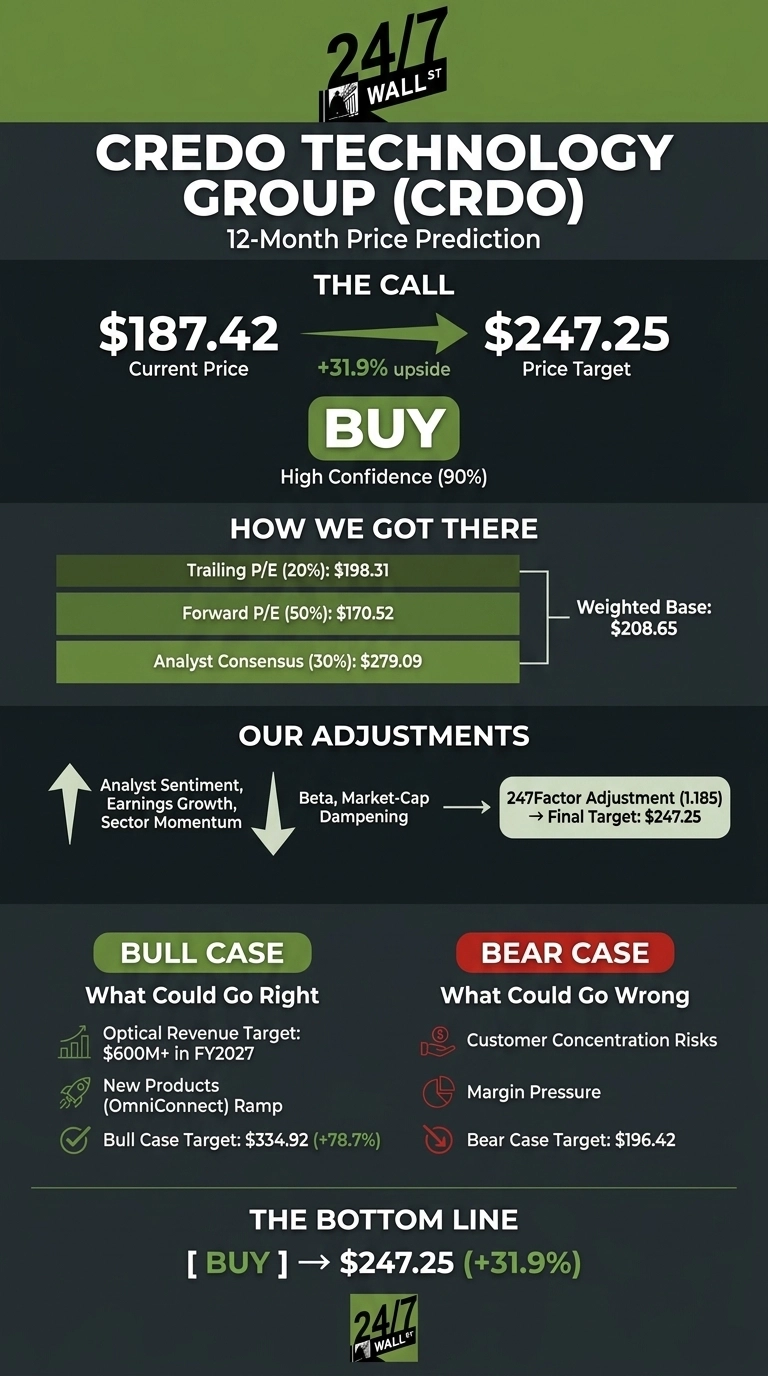
As AI clusters grow, the links between processors matter more and more, and one company is becoming a key supplier of those links. Credo (NASDAQ:CRDO | CRDO Price Prediction) traded at $187.42 Wednesday morning.
The 24/7 Wall St. price target is at $247.25, meaning 31.9% upside over the next 12 months. The stock gets a buy rating with high confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $187.42 |
| Price Target from 24/7 Wall St. | $247.25 |
| Upside | 31.9% |
| Recommendation | BUY |
| Confidence Level | 90% |
Credo started out as a copper cable specialist. Today it sells both copper and optical connections to five hyperscalers. Every link between a GPU and a switch is a place where a cluster can fail.
Credo wants to own that reliability problem from end to end, and its revenue growth suggests customers are paying for it.
A Sharp Post-Earnings Slide Reset the Valuation
Shares are down 15.13% over the past week, including a 5.49% drop today. They are still up 15.02% over the past month and 30.25% year to date. The stock is 39.3% below its 52-week high of $308.67.
Credo reported fiscal Q1 2027 results on September 1. Revenue came in at $479 million, up 114.7% from a year earlier. Non-GAAP EPS of $1.20 beat the $1.17 estimate, marking an 8th consecutive beat. Even so, shares fell from $227.76 on the day of the report to $170.57 by September 5. Management guided fiscal Q2 revenue to $525M to $535M.
Why Bulls See $335 Ahead
Optics is quickly becoming Credo’s second growth engine. Management expects more than $600 million in fiscal 2027 optical revenue. ZeroFlap optics, silicon photonics chips and optical DSPs are each expected to contribute more than $100 million. Fiscal 2028 brings three more products.
Active LED Cables connect equipment at longer distances, and NPO is a dense optical design for linking GPUs inside a system. OmniConnect, which connects processors to memory, could represent “thousands of dollars of Credo content per GPU”.
Chief Executive Bill Brennan called fiscal 2027 “just a stepping stone for where we’re going with our optical business.” Of the analysts covering Credo, 5 rate it Strong Buy, 14 rate it Buy and 1 rates it Hold. The bull case is $334.92, or 78.7% upside.

Customer Concentration Is the Risk Worth Watching
Credo’s largest customer accounted for 33% of revenue, and the second-largest for 28%. GAAP gross margin slipped to 64.5% from 68.2%, and stock-based compensation totaled $87.98 million for the quarter. Much of the margin fall comes from amortization linked to an acquisition that raised goodwill to $986.4 million.
Non-GAAP gross margin held at 68%. Management also expects three to four customers to each exceed 10% of revenue. Our bear case is $196.42.

How Credo Compares to Astera Labs and Marvell
Astera Labs (NASDAQ:ALAB) is the closest pure-play AI connectivity peer. It grew revenue 104.45% with a 39.1% non-GAAP operating margin, and it trades at 258x trailing earnings.
Marvell Technology (NASDAQ:MRVL) competes with Credo in optical DSPs, including 800G and 1.6T scale-out optics. Marvell is far larger but growing more slowly.
| Company | Revenue Growth (YoY) | Non-GAAP Operating Margin | Market Cap |
|---|---|---|---|
| Credo | 114.7% | 48.2% | $35.2B |
| Astera Labs | 104.45% | 39.1% | $53.7B |
| Marvell | 36.55% | 36.6% | $222.3B |
Credo is growing faster and gets higher margins than both peers, yet it has the lowest market cap of the three. Against that group, this 24/7 Wall St. price target looks reasonable, and arguably conservative.
Credo Price Prediction 2026-2030
The 24/7 Wall St. price target is $247.25, and we rate the stock a buy with 90% confidence. A forward multiple of 28x for a company growing at triple-digit rates makes the case for me.
The thesis improves if optical revenue keeps pace with the $600 million target. The thesis weakens if hyperscaler orders slow or the top two customers cut back. At today’s price, our model sees the potential reward outweighing the risk.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $247.25 |
| 2027 | $250.14 |
| 2028 | $296.97 |
| 2029 | $314.97 |
| 2030 | $360.16 |
These estimates assume Credo keeps executing its copper and optical strategy. Faster ramps for NPO and OmniConnect could drove the stock well above these targets. A slowdown in AI spending could leave it well below them.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.