Amazon Pops on a Target Raise. 59 Analysts, Zero Sells
Morgan Stanley just called Amazon a top pick and lifted its price target, but with negative free cash flow and $200 billion in planned spending ahead, the real question is whether AWS momentum can turn that mountain of capex into…

Amazon (NASDAQ:AMZN | AMZN Price Prediction) is up 5.18% today at $262.96. The move follows Morgan Stanley (NYSE:MS) raising its price target, keeping an overweight rating, and calling the stock a top pick on Monday morning.
Our own model sets the 24/7 Wall St. price target for Amazon at $329.36 over the next 12 months. That means 25.3% upside, a buy rating, and fairly high confidence.
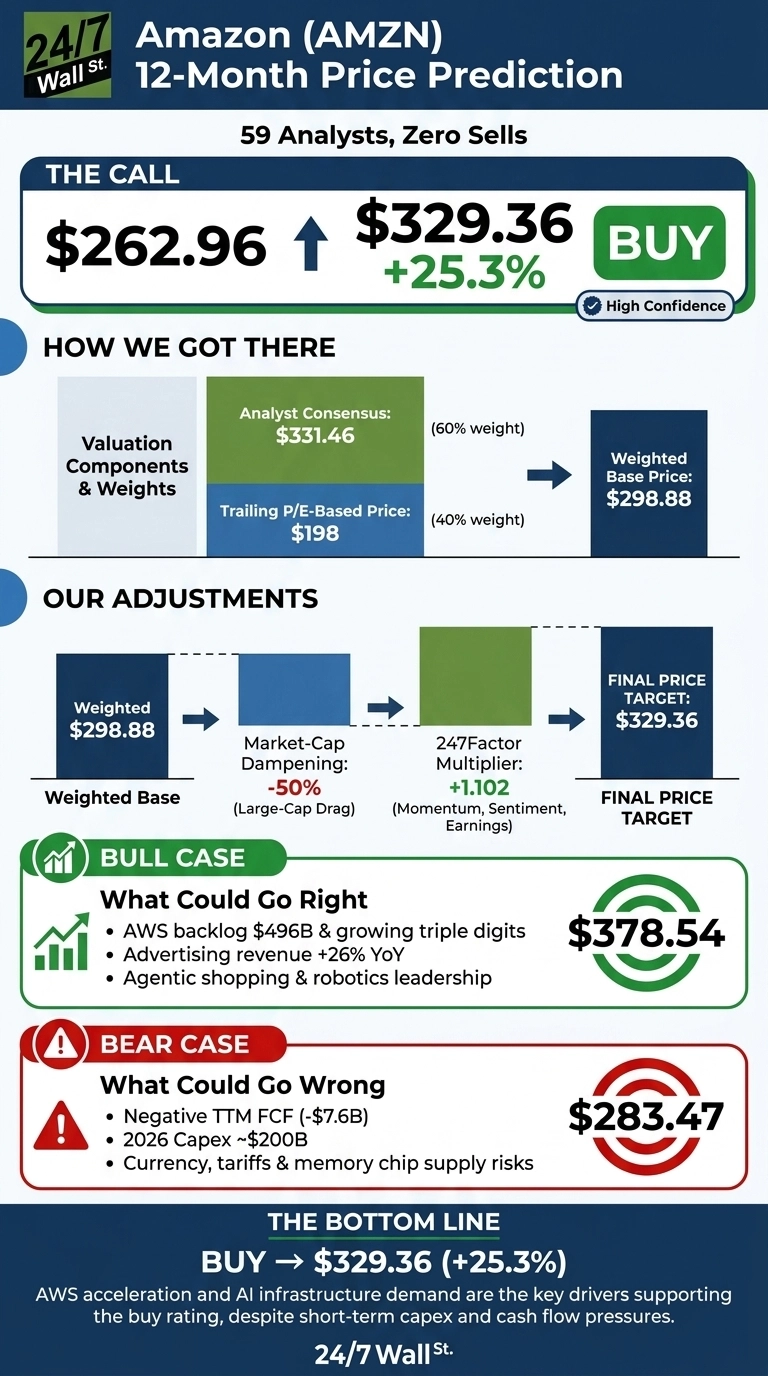
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $262.96 |
| 24/7 Wall St. Price Target | $329.36 |
| Upside/Downside | 25.3% |
| Recommendation | BUY |
| Confidence Level | 70% |

Wall Street generally agrees. Analysts give Amazon 16 strong buy ratings, 43 buys, 2 holds and zero sells. The consensus target of $331.46 lands almost exactly on our number.
Morgan Stanley analyst Brian Nowak wrote, “We continue to think AWS’s growth and profit runway is underappreciated.”

AWS Acceleration Pushed Amazon Back Toward Its Highs
Over the past week the stock is up 0.2%. It has gained 6.91% over the past month, 13.92% year to date and 22.61% over the past year. That leaves it 8.4% below its 52-week high of $287.20 and well above the $196 low.
In Q2, revenue grew 19.6% to $200.61 billion, beating estimates by 2.12%. GAAP EPS came in at $5.75, lifted by a $53.4 billion one-time gain tied largely to Anthropic. Comparable EPS was about $1.88 against a $1.83 estimate. AWS grew 37% to $42.23 billion, its fastest pace in 18 quarters. For Q3, management guided net sales to $197 billion to $202 billion.
Why Bulls See $378 and Beyond
The AWS backlog stands at $496 billion and is growing by triple digits. Amazon’s chief executive said AWS “will be at least double that and very possibly be a trillion-dollar annual revenue business for us in time.” Amazon’s AI and chips businesses each run above $25 billion a year, and management is exploring selling Trainium chips outside AWS.
Advertising grew 26%. Morgan Stanley also sees Amazon as a winner in agentic shopping and robotics, even after Meta Platforms (NASDAQ:META) launched its Muse agent. The bull case reaches $378.54.

Capex and Cash Burn Are the Risks Worth Watching
Trailing free cash flow is negative $7.6 billion, and 2026 capex is planned near $200 billion. Other pressures include currency drags of about 80 bps in Q3, tariffs, and swings in memory chip supply.
That $200 billion has to be powered, cooled, and networked by somebody, which is the whole thesis of the seven suppliers we profiled in a free AI infrastructure report.
Still, operating cash flow rose 40%. Management also says most AI capacity is signed for at least five-year terms. Even the bear case of $283.47 sits above today’s price.
How Amazon Compares to Microsoft and Alphabet
| Company | Forward P/E | Revenue Growth (YoY) |
|---|---|---|
| Amazon | 24x | 19.6% |
| Microsoft | 25x | 17.7% |
| Alphabet | 23x | 24.2% |
Microsoft (NASDAQ:MSFT) is the most direct rival to AWS through Azure. It trades at a slightly higher multiple while growing more slowly. Its 45.1% operating margin is far above Amazon’s 13.7%, which reflects Amazon’s large retail business.
Alphabet (NASDAQ:GOOGL) competes with Amazon in both cloud and digital advertising. It is growing faster at a similar multiple. Against these two peers, Amazon’s valuation sits in the middle, which makes our target look reasonable.
AWS Momentum Tips the Scale to BUY
The 24/7 Wall St. price target of $329.36 supports a buy rating at 70% confidence. AWS acceleration is the deciding factor. The setup holds up as long as AWS keeps growing above 30% and capex turns into signed revenue. It weakens if free cash flow remains negative into 2027 or margins slip.
Looking further ahead, these are the levels our model projects, assuming current growth trends hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $274.12 |
| 2027 | $330.07 |
| 2028 | $389.28 |
| 2029 | $466.68 |
| 2030 | $495.38 |
The outlook depends on Amazon continuing to carry out its current strategy. Returns on AI capex and competition in agentic commerce could swing the outcome significantly in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.