I Ran the Numbers on Salesforce. Here’s Where I Think It Could Be in 2030
Salesforce is building an AI agent empire while its stock sits near multi-year lows, and the math behind a potential 184% gain by 2030 comes down to whether three very specific things happen in the next four years.

Salesforce (NYSE:CRM | CRM Price Prediction | CRM Price Prediction) runs the world’s largest CRM platform, and it is turning into an AI agent company. Agentforce ARR passed $1.5 billion in the August quarter, up more than 240% year over year.
Even so, shares are down 6.44% year to date at $246.11. The gap between business momentum and the share price is the whole story, so I ran the numbers on one question: can Salesforce reach $700 per share by 2030?

What’s Holding Salesforce Back Right Now
The market concerns that AI agents will hollow out seat-based software, but Salesforce has spent the year making the opposite case, and investors remain skeptical. Shares fell 4.96% over the past month, even after a 9.6% rise this week. Over five years, the stock is down 13.98%.
Doubts about earnings quality remain too. Q2 FY27 non-GAAP EPS of $5.90 included a $2.53 per share boost from strategic investment gains. Free cash flow growth is guided to just 4% to 5% this year, and management noted volatile license revenue. With a beta of 1.256, Salesforce moves harder than the market when sentiment turns.
Wall Street Is Too Cautious on Salesforce. Here’s My Case
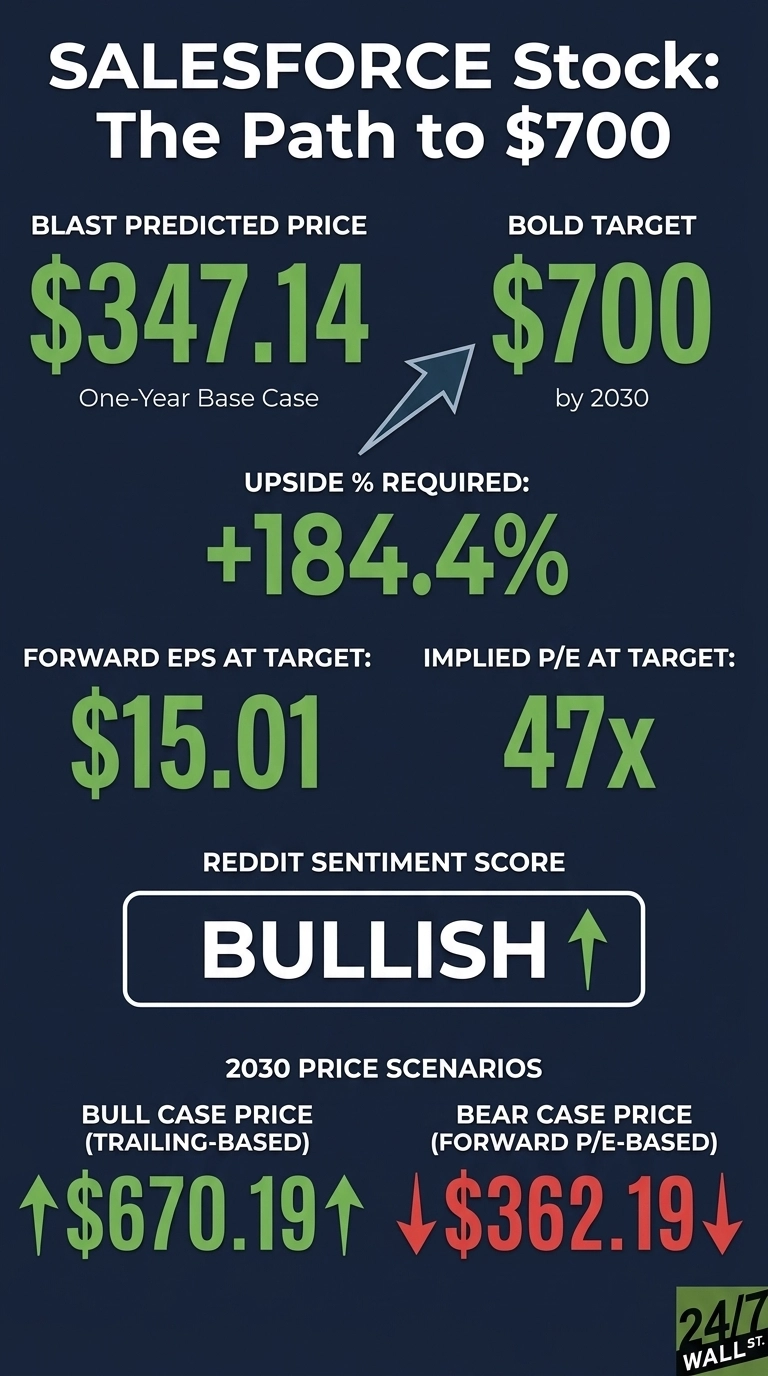
The consensus target is $285.68, roughly 16.1% higher than the current price. Coverage includes 6 strong buys, 32 buys, 15 holds, 0 sells and 2 strong sells. Our model’s one-year base case is $347.14, meaning 47.6% upside with a high confidence level of 0.9. The scenarios run from $282.43 in the bear case to $386.92 in the bull case.

In my view, analysts are still stuck on to a rough 2026 for the stock and are underweighting what the business is doing. 69% of analysts are bullish, and earnings growth adds 0.03 to our projections. cRPO grew 14%, and net-new annual contract value growth was the strongest in four years. Bank of America argued this week that the AI pivot will drive shares higher.
Here’s What It Takes for Salesforce to Reach $700
Reaching $700 from today’s price of $246.11 would require a gain of 184.4%.
With forward EPS of $15.0129, a price of $700 meaning a forward P/E of 47x. Our base case of $347.14 already meaning 23x, so the bold target needs about 24x of additional multiple expansion on today’s earnings.
That multiple looks extreme until you add four years of earnings growth. If EPS rises, the forward P/E contracts fast. FY27 non-GAAP EPS guidance already stands at $16.67 to $16.71. Management is targeting $63 billion in FY30 revenue, up from $41.5 billion in FY26.
The buyback cut reduced shares to 821M from 962M. At $25 of EPS, $700 works out to a more reasonable 28x. A 1.195 adjustment factor, driven by a 1.15 tech sector multiplier and analyst optimism, supports a premium. Our 2030 base and bull cases sit at $634.17 and $670.19.
On the August call, CEO Marc Benioff said, “We’re going from the dumb software era to the smart software era in real time.” Combined Agentforce and Data 360 ARR is nearly $3.9 billion, up more than 210%.
A key risk is that AI agents shrink seat counts faster than consumption pricing can make up the lost revenue.
Where Salesforce Trades Today vs Its Earnings Power
At $246.11, Salesforce trades at 16x forward earnings. That looks cheap for a business guiding to 11% to 12% revenue growth with a 34.3% non-GAAP operating margin.
Shares are trading between a 52-week low of $146.06 and a high of $267.80. The 10-year return is 237.81%. A multiple in the mid-teens leaves the bull case plenty of room to run.
$700 Is a Stretch, but Here’s Why It’s Possible
Hitting $700 requires a 184.4% gain. It’s a stretch, but reachable if three things happen. Agentforce ARR keeps compounding. Premium edition upgrades scale from just 5% of sales and service workers today.
And the $63 billion FY30 target arrives with wider margins. A stall in AI monetization would disrupt it. Such gains shouldn’t be expected every year, but we’ve outlined the plan for how Salesforce could reach $700 in 2030.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.