What Will $5,000 Invested in Marvell Stock Be Worth in 5 Years?
Marvell stock has surged more than 200% in a year on the back of explosive AI data center demand, but whether that momentum carries a $5,000 investment higher or leaves it worse off depends on forces that could shift fast.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
If you put $5,000 into Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) today, what could it be worth by 2031? Shares traded at $269.87 in early trading, after a 213.75% gain over the past year.
The rally comes from AI data center demand that management says is still speeding up, and that is why it makes sense to look five years ahead.

What Your $5,000 Could Become by 2031
Under the model’s central scenario, a $5,000 investment could be worth about $6,763.50 by 2031, a total return of 35.27%.
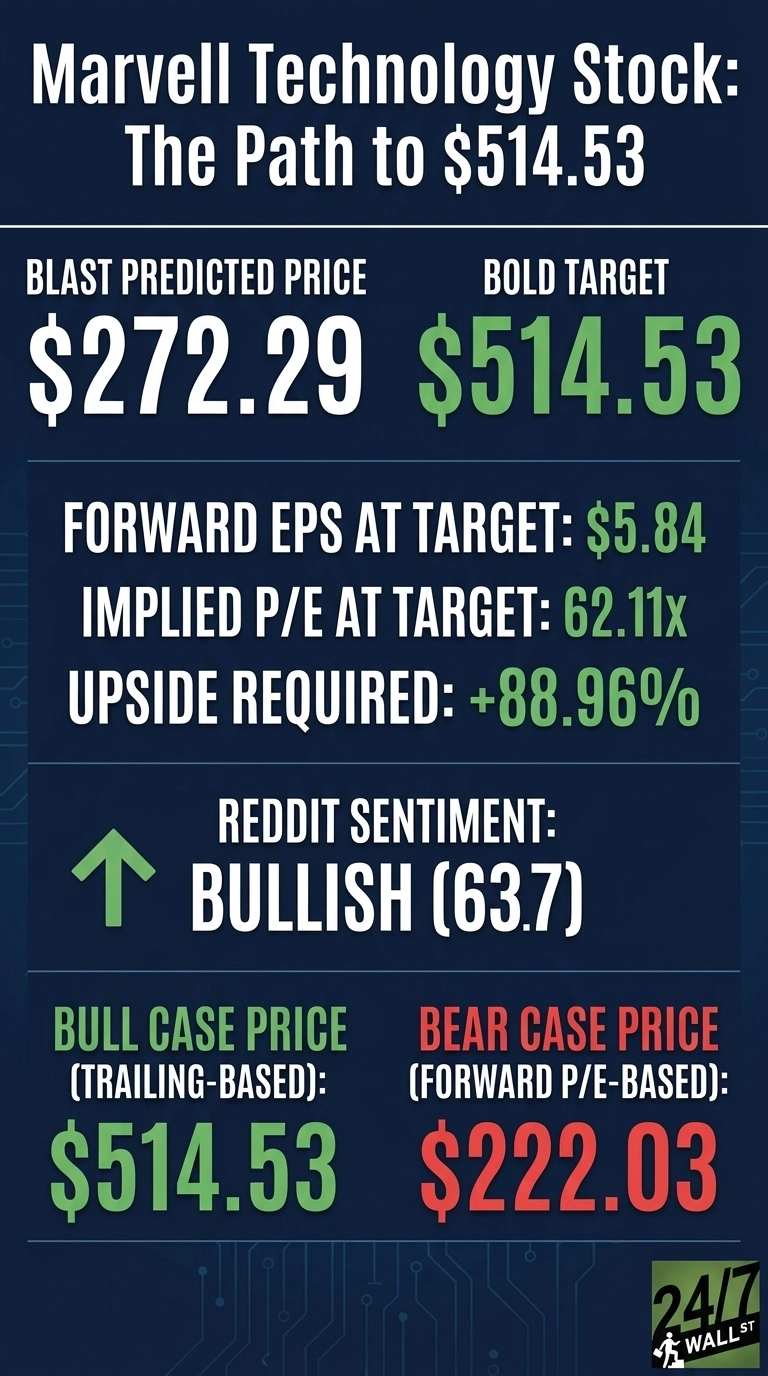
That figure rests on a projected five-year share price of $368.34, measured from the model’s starting price of $272.29. The annualized return comes to 6.23%. The model rates its confidence at 0.9, a level it views high.
Bull, Base and Bear Scenarios for a $5,000 Stake
| Scenario | 2031 Target Price | Total Return | Value of $5,000 |
|---|---|---|---|
| Bull | $514.53 | 88.96% | $9,448 |
| Base | $368.34 | 35.27% | $6,763.50 |
| Bear | $222.03 | -18.46% | $4,077 |
Wall Street is bullish. Analysts list 8 Strong Buy ratings, 32 Buys, 6 Holds and no Sell ratings, with a consensus price target of $293.88.
Over one year, the model’s base case calls for $293.18, or 7.67% upside. That is close to the analyst target, so most of the projected gain is expected to build gradually after the first year.

Three Drivers Behind the Target
Data Center Revenue Keeps Accelerating
Second-quarter fiscal 2027 revenue reached $2.739 billion, up 36.55% year over year and ahead of the $2.7068343 billion estimate. Data center sales rose 46% to $2.1715 billion and now make up 79% of revenue.
Management expects fiscal 2027 revenue to grow about 45% to roughly $12 billion. It also raised its fiscal 2028 growth outlook to about 50%. CEO Matt Murphy said: “AI-related bookings remain exceptionally robust, and we expect our revenue growth to accelerate further through the remainder of fiscal 2027.”
Custom Silicon and Google Deal Could Drive the Bull Case
Marvell expanded its custom silicon partnership with Alphabet (NASDAQ:GOOGL) unit Google. The deal includes a warrant that lets Google buy up to 7% of Marvell’s shares if revenue targets are met. Management expects the custom business to more than double year over year in fiscal 2028.
It also confirmed a custom revenue path toward a “$10 billion kind of plus number” in fiscal 2029, and said the Google agreement raises that potential. Tuesday’s Investor Day in New York is expected to include a longer-term revenue framework, and that update could move the scenarios above.
Margins Are Widening
Non-GAAP operating margin expanded to 36.6% from 34.8%, and non-GAAP EPS of $0.94 beat the 0.9289 estimate. Management expects the margin to reach its 38% to 40% long-term target range in the fourth quarter of fiscal 2027.
Guidance for the third quarter calls for $3.150 billion in revenue and non-GAAP EPS of $1.10, plus or minus 5 cents.
Risks That Could Shrink Your $5,000
A lot of growth is already in the price. Marvell trades at 90 times trailing earnings and 62 times forward earnings. Its beta of 2.253 means the stock tends to move about twice as much as the market.
Over the past 52 weeks it has traded as low as $70.64 and as high as $329.80. If growth slows, the bear case would leave your investment at $4,077.
- Customer concentration: a small group of hyperscalers drives a large share of revenue, and any of them could cut spending or design chips in-house.
- Supply constraints: advanced wafers, substrates and test capacity are tight. Marvell plans about $1 billion in capacity prepayments to suppliers this fiscal year.
- Trade and tariffs: restrictions on Chinese customers and tariff uncertainty add risk.
- Balance sheet and dilution: long-term debt totals $4.963 billion. The Google warrant could dilute existing shareholders, and stock-based compensation rose to $207.6 million in the first quarter from $142.1 million a year earlier.
Where a $5,000 Marvell Stake Could Land
Under the projected scenarios, a $5,000 Marvell investment could be worth anywhere from $4,077 to $9,448 by 2031, with a base case of $6,763.50.
Over the next year, keep an eye on Investor Day targets, custom silicon ramps and whether hyperscalers keep spending at their current pace. The traits that showed up early in the biggest AI chip winners are the ones we cataloged in a free playbook here: The Next Nvidia Playbook. These are projections, not guarantees, and this is not investment advice.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.