What Happened to $1,000 Invested in Microsoft Before Its Cloud and AI Boom?
Satya Nadella inherited a company synonymous with Windows and turned it into something Wall Street barely recognized a decade later. Whether that transformation actually rewarded patient investors depends on when you started the clock.

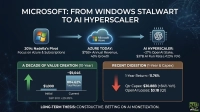
From Windows Company to AI Landlord
Ten years ago, Microsoft (NASDAQ:MSFT | MSFT Price Prediction) was still known as the Windows company. Satya Nadella became CEO in 2014 and shifted the business to a cloud-first model. The following decade showed the shift was the right call.
Azure went from challenger to a dominant cloud platform and passed $100 billion in annual revenue in fiscal 2026. Office turned into Microsoft 365 subscriptions. The 2019 OpenAI investment became the company’s defining move of the AI era. After a restructuring, Microsoft owns roughly a 27% stake valued at nearly $135 billion, and OpenAI committed to an additional $250 billion in Azure services.
Record Profits Collide With Record Spending
Fiscal 2026 revenue reached $331.84 billion (up 17.79%), and net income rose 31.34% to $133.75 billion. Commercial remaining performance obligation jumped 84% to $678 billion. Capex also climbed 79.62% to $115.95 billion, which pushed free cash flow down 6.46%.

Your $1,000 Grew to More Than $10,000
1-Year Return
- Initial Investment: $1,000
- Current Value: $1,043.30
- Total Return: 4.33%
- S&P 500 (same period): $1,161.60 (16.16%)
5-Year Return
- Initial Investment: $1,000
- Current Value: $1,800
- Total Return: 80%
- Annualized Return: 12.47%
- S&P 500 (same period): $1,705.90 (70.59%)
10-Year Return
- Initial Investment: $1,000
- Current Value: $10,023.10
- Total Return: 902.31%
- Annualized Return: 25.92%
- S&P 500 (same period): $3,606.80 (260.68%)

Over 10 years, recurring cloud revenue grew year after year, and investors paid up for it. The 5-year margin over the index is much thinner. That window includes the 2022 tech selloff. Over the past year, Microsoft trailed the S&P 500 by a wide margin as capex climbed faster than revenue. Shares are up 10.5% year to date and trade at $531.
All of these figures track share price only. The quarterly dividend rose from $0.36 in early 2016 to $0.98, payable December 10, 2026. Reinvesting those payouts would have raised the total.
Azure Growth Versus Capex Will Decide What Comes Next
Microsoft’s case strengthens if Azure keeps growing faster than the spending behind it and weakens if capex keeps rising while returns flatten.
Bull case: Azure grew 43% last quarter, and management guided for about 45% in constant currency next quarter. Copilot has passed 30 million paid seats. CFO Amy Hood said, “Demand continues to exceed available supply.”
Bear case: Management expects capex to rise again in fiscal 2027 and operating margins to slip by less than a point. More Personal Computing revenue fell 4%, and a P/E near 30 on a $3.94 trillion company leaves little room for mistakes.

The bull case has more data to back it up. A $678 billion backlog makes demand easy to see, which the market rarely gets. Free cash flow is the number I’d check every quarter.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.