One Semiconductor Stock That Could Surprise Investors in 2027
ON Semiconductor supplies the power chips running AI data centers, EVs, and grid storage, and its stock still sits nearly 50% below its 52-week high. A specific combination of catalysts could change that in a dramatic way by 2027.


Few chipmakers are as tied to the AI power buildout as ON Semiconductor (NASDAQ:ON | ON Price Prediction). Onsemi sells silicon carbide, gallium nitride and silicon power chips that carry electricity “from the wall to the core” in AI data centers, EVs and grid storage.
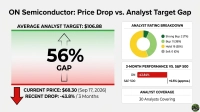
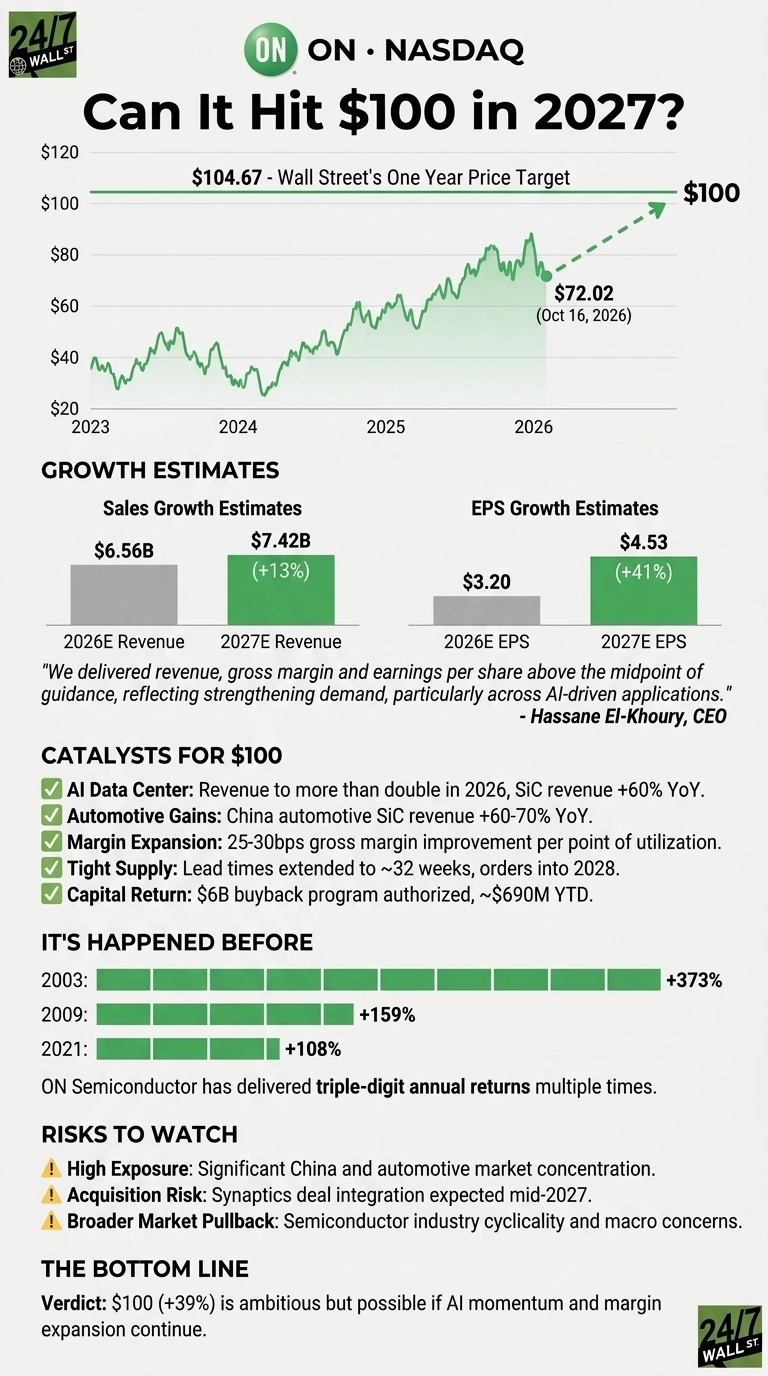
Shares are up 33% year-to-date at $72.02. They also sit 47% below their 52-week high of $134.92. CEO Hassane El-Khoury says onsemi has “moved beyond the cyclical trough on a path to recovery.” So what would it take for onsemi to reach $125 per share in 2027?

Wall Street Already Sees 45% Upside in ON Semiconductor
The average analyst price target of $104.67 implies 45% upside. Ratings break down to 2 Strong Buys, 12 Buys, 16 Holds and zero Sells. Analysts expect 2027 EPS of $4.5288, compared with $3.2018 for 2026.

That works out to 41% growth on revenue of $7.42 billion. Ninety days ago, the 2027 estimate stood at $4.3136. Onsemi has also beaten EPS estimates four quarters in a row, so actual results could come in above forecasts.
Here’s What It Takes for ON Semiconductor to Reach $125
Onsemi trades at 16x 2027 earnings at current prices. At $125, the multiple would be 28x. The premium over the S&P 500’s forward multiple of about 22x is a reasonable one for a company growing earnings at 41%.

Several factors could drive onsemi to $125.
- AI data center growth: Revenue from this business is on track to “more than double in 2026,” and silicon carbide sales into AI data centers should rise nearly 60%. The move to 800-volt DC racks adds more high-voltage content per rack.
- Margin expansion: Non-GAAP gross margin reached 39.3%, and guidance calls for 40% to 42%. Management estimates “25 to 30 basis points of gross margin improvement for every point of utilization,” and utilization rose to 83% from 77%.
- Tight supply: Lead times stretched from 27 weeks to 32 weeks, with orders extending into 2027 and, in some cases, 2028.
- EV share gains: Automotive silicon carbide revenue in China is expected to rise 60% to 70%. Onsemi chips also power the R2 platform from Rivian Automotive (NASDAQ:RIVN).
- Buybacks: Onsemi bought back $690.5 million of stock year-to-date under a $6 billion authorization.
The expansion onsemi is feeding also runs through the power, cooling and networking suppliers around the data center, and we covered seven of them in a report: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).

ON Semiconductor Has Delivered Years Like This Before
Reaching $125 requires a 74% gain. Since 2000, onsemi has topped that in three calendar years: 373% in 2003, 159% in 2009 and 108% in 2021.
Shares traded above $125 within the past 52 weeks, and a beta of 2.05 means big moves can happen in either direction.
$125 Is a Stretch, but the Pieces Are in Place
Several risks could slow the path. Analog and Mixed-Signal revenue fell 2%, onsemi has heavy China and automotive exposure, and the Synaptics (NASDAQ:SYNA) deal is not expected to close until mid-2027.
Still, rising estimates, expanding margins and doubling AI revenue give onsemi a credible path to $125. Gains of this size are rare, and this is how onsemi could deliver outsized gains in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.