ON Semiconductor Has Cratered for 3 Months: This Wall Street Pro Remains Bullish, Citing 120% Returns for Buyers
ON Semiconductor shed nearly half its value in three months while its peers barely flinched, yet one Wall Street analyst just doubled down with the most aggressive price target on the Street. The disconnect between the selloff and the operating…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
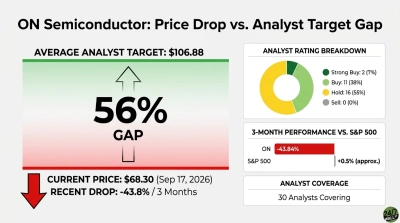
ON Semiconductor (NASDAQ:ON | ON Price Prediction) trades at $68.30 after a brutal summer, while the average Wall Street price target sits at $106.88. That leaves the stock roughly 56% below where analysts, on average, think it should trade.
ON is the Phoenix-based designer behind onsemi, a top supplier of intelligent power and sensing chips for cars, factories, and increasingly, AI server racks. Its EliteSiC silicon carbide and GaNEXUS gallium nitride families are pitched as the plumbing for 800-volt vehicle platforms and the next generation of hyperscaler power trees. Wall Street cares because that story sits at the intersection of two of the biggest capex cycles in tech.
Even after a brutal selloff, business metrics are improving and analysts have not wavered. One has doubled down.
A Three-Month Wipeout in a Rallying Market
Shares of ON have plunged 43.84% over the past three months, a decline steep enough to qualify as a full-blown crash. The stock started that window at $121.62 and has bled all the way down to its current level, with a 14% drop just in the last month.
The selloff came despite strong results. Q2 fiscal 2026 revenue of $1.60 billion beat estimates and rose 9.18% year over year, with non-GAAP EPS of $0.74 topping the $0.7153 consensus. Shares popped more than 5% after the report. The unwind has been driven by broader concerns: high automotive exposure, China cyclicality, a rich trailing valuation, and profit-taking after a run that had ON near $134.92 on a 52-week basis. The peer group softened too, but ON fell harder and faster.
Why Susquehanna Still Sees Roughly 120% Upside
Analysts have not chased the stock lower. Coverage sits at 2 Strong Buy, 11 Buy, 16 Hold, and zero Sell ratings, and estimate revisions have skewed sharply higher, with 25 upward EPS revisions for fiscal 2026 in the trailing 30 days against just two down.
Susquehanna’s Christopher Rolland reiterated a Buy with a Street-high $150 price target, implying roughly 120% upside from $68.30. His thesis: EliteSiC capturing dominant share as EV platforms shift from 400V to 800V architectures, AI data center power scaling through smart power stages and point-of-load converters, and gross margins recovering toward 40%+.
Management backs that narrative. AI data center is now expected to more than double in 2026. CEO Hassane El-Khoury told investors, “Our growth in data center is literally from the wall to the core.” Silicon carbide revenue in data centers is guided to grow nearly 60% year over year, with content per rack jumping from $15,000 to $115,000 in an 800-volt DC architecture. Non-GAAP gross margin already expanded to 39.3%, with Q3 guidance calling for 40% to 42%.
Analog Peers Held Up While ON Broke Down
This selloff is largely a single-name story. Peers softened but held ground.
NXP Semiconductors (NASDAQ:NXPI) trades at $227.95 against a target of $311.10, roughly 36% of implied upside. NXPI is up 5.02% year to date with 6 Strong Buy, 16 Buy, 7 Hold and 1 Sell ratings, a solidly bullish tilt.
Analog Devices (NASDAQ:ADI) has been the sector standout, up 33.72% year to date at $362.65 against a $470.72 target, about 30% upside. Coverage skews aggressively bullish at 7 Strong Buy, 24 Buy, 3 Hold.
ON’s analyst-implied upside is the widest in the group. That makes ON the outlier in the group.
Numbers That Frame the Setup
ON trades at $68.30 versus a consensus target of $106.88 from 30 covering analysts, implying 56% upside to the average and about 120% to Susquehanna’s $150. The forward P/E of 16 reflects the sharp fiscal 2026 earnings ramp analysts are modeling toward $3.2028 full-year EPS.
ON is up 26.13% year to date, ahead of the S&P 500‘s 11.85%, but that lead was built and lost in a violent round trip. Over three months, ON’s 43.84% drawdown stands in stark contrast to a flat-to-up broad market.
Where I Land on ON at $68
The bull case for ON here rests on the AI data center ramp and silicon carbide share gains materializing over the next few quarters. Q3 guidance already points to gross margins of 40% to 42%, book-to-bill has been above 1 for several quarters, and lead times have extended to roughly 32 weeks. Deliver on those numbers and even the consensus $106.88 becomes conservative.
The bear case centers on automotive weakness in Europe, China exposure, and the pending Synaptics acquisition integration risk are what the market is pricing in. A stalled industrial recovery or a slip in AI content per rack could keep the multiple compressed.
My lean is cautiously bullish. The analyst dispersion is wide for a reason, but the operating data is moving in the bulls’ direction, and ON’s dislocation looks larger than the fundamentals justify.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.