Prediction: ON Semiconductor Could Be a Sleeper AI Infrastructure Winner
Wall Street still prices ON Semiconductor like a cyclical auto chipmaker, but something quietly shifted inside its data centers that the broader market has not yet noticed.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

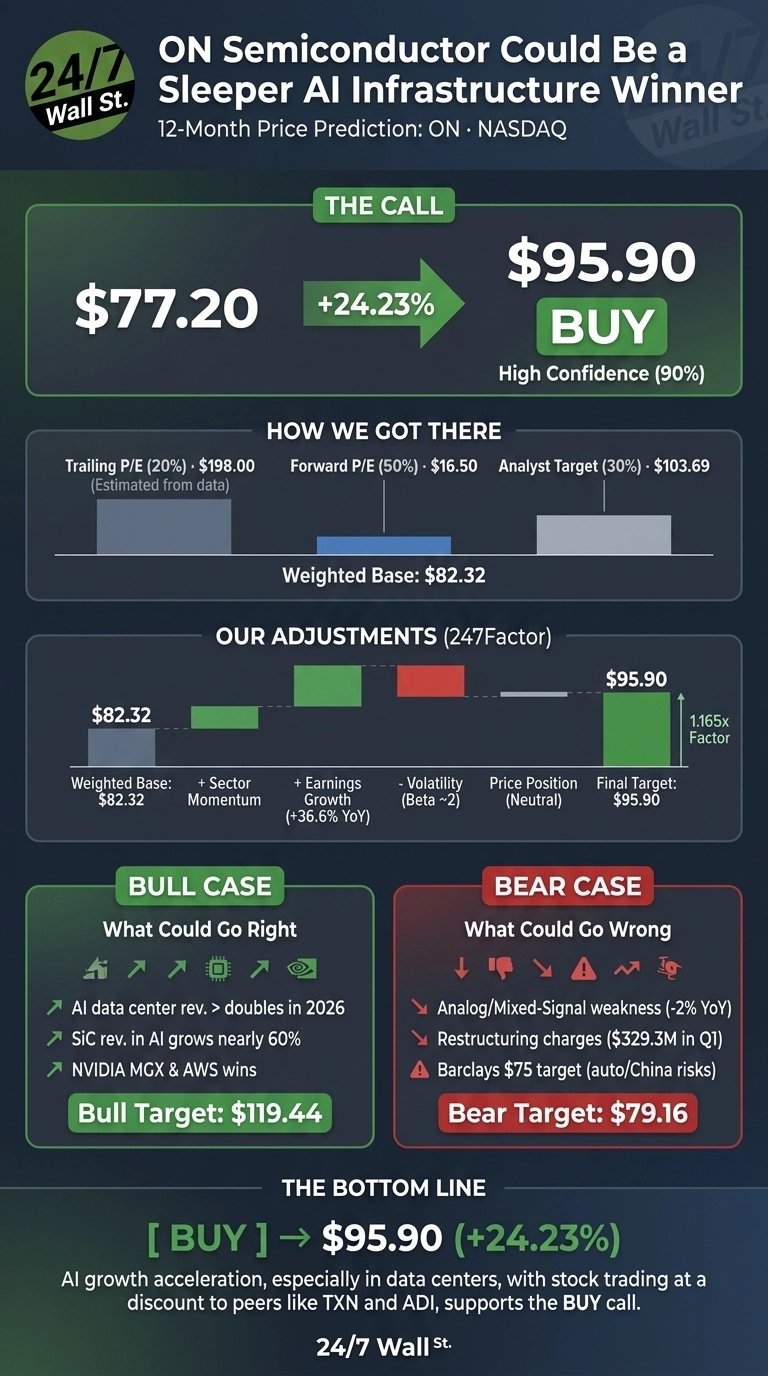
Our 24/7 Wall St. price target for ON Semiconductor (NASDAQ:ON | ON Price Prediction) is $95.90 over the next 12 months. That points to 24.23% upside from the current $77.20 share price.
| Metric | Value |
|---|---|
| Current Price | $77.20 |
| Price Target from 24/7 Wall St. | $95.90 |
| Upside/Downside | 24.23% |
| Recommendation | BUY |
| Confidence Level | 90% |

onsemi gets a buy rating in our model because the market still prices it like a cyclical automotive chipmaker, while management expects its AI data center business to more than double in 2026. That gap is the opportunity.
A 10% Weekly Rally Brings the AI Power Story Back
Shares rose 10.32% over the past week and 42.57% year to date. It trades 42.8% below its 52-week high of $134.92 and 73.2% above its low of $44.56.
In its second-quarter earnings report, non-GAAP EPS of $0.74 beat estimates of $0.7153. Revenue of $1.6035 billion also came in ahead of expectations and rose 9.18% year over year. Free cash flow jumped 300.94% to $425.4 million. Third-quarter guidance calls for EPS of $0.81 to $0.93.

Why Bulls See $119 Within Reach
Management puts AI data center content at roughly $15,000 per rack today and sees it rising to about $115,000 as racks shift to 800-volt DC power. Silicon carbide revenue from AI data centers should grow nearly 60% in 2026. Recent wins include a bigger role in NVIDIA’s MGX ecosystem and design wins for AWS power supply and battery backup systems.
Lead times extended from 27 weeks to 32 weeks, and utilization rose to 83%. Each utilization point adds 25 to 30 basis points of gross margin.
For 2027, the high analyst EPS estimate is $5.3992. Of analysts covering the stock, 13 rate it a buy or strong buy and none rate it a sell. Our bull case target is $119.44.


Risks That Could Pin ON Near $79
Revenue in the Analog and Mixed-Signal Group fell 2% year over year. When Barclays initiated coverage, it set an equal-weight rating and a $75 target, citing heavy exposure to automotive and China. Restructuring charges of $329.3 million in the first quarter weighed on GAAP results.
Those charges fund a leaner manufacturing operations, which should yield about $35 million in annualized savings. Other risks include possible dilution from convertible notes and integrating the Synaptics acquisition. Buybacks are also running at about 105% of free cash flow. The bear case target is $79.16.
ON Trades at a Deep Discount to TI and Analog Devices
| Company | Forward P/E | Price/Sales |
|---|---|---|
| ON Semiconductor | 17x | 4.85x |
| Texas Instruments | 28x | 13.05x |
| Analog Devices | 23x | 13.74x |
Texas Instruments (NASDAQ:TXN) sells analog and power chips into industrial, automotive and data center markets. Its second-quarter revenue grew 22.82%.
Analog Devices (NASDAQ:ADI) acquired Empower Semiconductor for AI server power. Revenue rose 39.63% with adjusted operating margin of 50.0%. ON’s lower margins explain part of the discount. Our target works out to about 21x the 2027 consensus EPS of $4.5288, below both peers’ forward multiples.
ON Semiconductor Price Prediction 2026-2030
The 24/7 Wall St. price target of $95.90 carries a buy rating with 90% confidence. AI data center growth coming while ON trades at a steep discount to peers tips the scale.
The case improves if gross margin reaches the forecast 40% to 42% range. I would grow cautious if automotive demand in China fades.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $84.24 |
| 2027 | $96.72 |
| 2028 | $112.46 |
| 2029 | $125.05 |
| 2030 | $132.82 |
These projections assume onsemi keeps implementing its existing strategy. The results could land well above or below them depending on how fast 800-volt data center power is adopted and how the Synaptics integration goes.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.