This article is updated throughout the trading day. Check back for more.
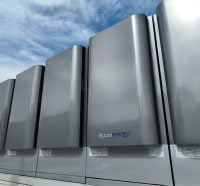
Bloom Energy (NYSE:BE) is expected to report third-quarter results today at 4:05 PM ET, after the market closes. The stock fell 10.04% ahead of the release, and tonight’s results will show whether it can recover by the end of the week.
Billion-Dollar Quarter Meets a Sharp Pullback
Last quarter, Bloom Energy reported its first quarter with over $1 billion in revenue. Q2 revenue came in at $1.065 billion, up 166% year-over-year, and non-GAAP EPS of $0.78 beat the $0.4066 estimate. The stock gained 43.1% in the seven days after that report. It has since pulled back, though it remains up 146.96% year to date. Operating cash flow reached $226 million and free cash flow hit $175 million.
Management raised 2026 guidance to $3.9-$4.2 billion in revenue and $2.55-$2.85 in non-GAAP EPS. The company also said all major U.S. hyperscalers have approved its systems.
Bloom Energy Consensus Estimates
| Metric |
Q3 2026 Estimate |
YoY Change |
FY 2026 Estimate |
FY 2027 Estimate |
| Revenue |
$1.07B |
+106.4% |
$4.12B |
$6.82B |
| EPS (Normalized) |
$0.6724 |
+348.3% |
$2.7079 |
$4.9384 |
The revenue consensus is about flat with Q2, so analysts are modeling a pause in sequential growth after an uneven delivery quarter. The Q3 EPS estimate has risen from $0.5216 90 days ago. Full-year consensus already falls inside management’s guided ranges.
What I’m Watching Tonight: Margins, Financing and Delivery Timing
One of the top numbers I’m watching tonight is the gross margin. Q2 gross margin hit 34.3%, and services margin reached 22%. However, management said it will prioritize fast delivery over protecting margin in any one quarter.
Another focus is how much of Brookfield’s recently expanded $25 billion financing framework gets used. A second group led by Industrial Development Funding has committed $2.6 billion. The more of these commitments become funded installations, the clearer the revenue path through 2027.
Analysts will also be watching revenue concentration among customers. Management warned that “one or two customers may lead revenue in a given quarter” because large campus deliveries are uneven. Any comments on project delays matter, along with the claim that its equipment can be moved from one site to another.
Investors are going to be watching operating leverage too. In Q2, revenue grew 166% while operating expenses rose 48%, and management called $375 million plus a new baseline for cash flow from operations. Analysts will also be listening for updates on manufacturing capacity and scandium supply, which management said is secured for 25 gigawatts of deployments.
Earnings History
| Quarter |
EPS Surprise |
1-Day Move |
7-Day Move |
30-Day Move |
| Q2 2026 |
+91.83% |
+26.49% |
+43.1% |
+28.71% |
| Q1 2026 |
+242.41% |
-1.6% |
-0.87% |
-5.02% |
| Q4 2025 |
+50.35% |
+8.49% |
-2.3% |
+11.31% |
| Q3 2025 |
+50.15% |
-4.38% |
+5.76% |
-26.01% |
On average, shares have swung 11.4% in the week following earnings over the past year.
Contact [email protected] for any questions or corrections.