Prediction: One of the World’s Biggest Stocks Could Still Have Room to Run
Alphabet's cloud business just posted growth that would make most tech companies blush, yet the stock sits well below its recent highs. Whether that gap represents a value opportunity or a warning sign depends on what you believe about one…

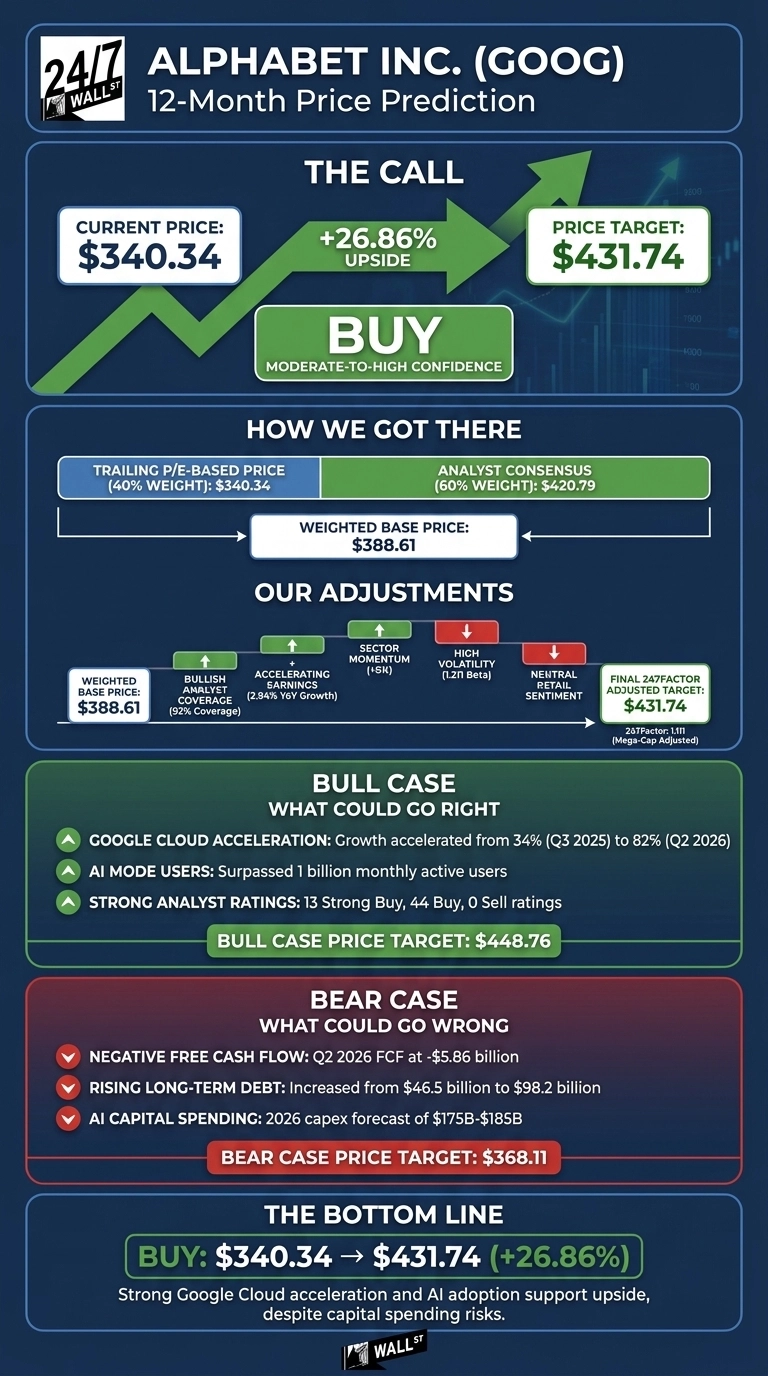
Our 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG | GOOG Price Prediction) is $431.74 over the next 12 months. From $340.34, that means 26.86% upside. Our rating is buy, with moderate-to-high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $340.34 |
| Price Target from 24/7 Wall St. | $431.74 |
| Upside/Downside | 26.86% |
| Recommendation | BUY |
| Confidence Level | 70% |

Alphabet has a market value of about $4.16 trillion, and its growth is still speeding up. Revenue growth rose from 15.95% in Q3 2025 to 24.23% in Q2 2026.
Over the same period, Google Cloud growth went from 34% to 82%. The stock has not kept pace with that momentum, and that gap supports our upside case.
Shares Stall Even After a Strong Cloud Quarter
GOOG is down 3.2% over the past week and 1.91% over the past month. It is still up 7.86% year to date and 33.46% over the past year. At $337.82 midday Tuesday, the stock sat 16.4% below its $403.96 52-week high and 35.2% above its $249.80 low.
In Q2, revenue came in at $119.80 billion, ahead of the $116.91 billion estimate. EPS was $9.11, though a $99.03 billion gain on equity securities inflated that number. The cloud backlog hit $514 billion.
Why Bulls See $448 and Beyond
Google Cloud’s operating margin rose to 35.6% from 20.7% a year earlier. Management expects just over 50% of the backlog to turn into revenue within 24 months.
AI Mode has passed 1 billion monthly users, and Alphabet expects most of its TPU system sales revenue to land in 2027. On the Q2 earnings call, management said Alphabet had become “more bullish on the opportunities ahead”.
Wall Street generally agrees. Of the analysts covering the stock, 13 rate it Strong Buy, 44 rate it Buy and none rate it Sell. The consensus target is $420.79. In the bull case, the target reaches $448.76.

Spending Spree Is the Risk to Monitor
Alphabet guided to $175 billion to $185 billion in 2026 capex, and Q2 free cash flow turned negative at -$5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion.
Buybacks are paused, and a stock sale program of up to $40 billion could dilute shareholders. Renting outside computing capacity will also weigh on cloud margins. The bear case sits at $368.11, which is still above today’s price.

Operating cash flow rose 40.8% to $39.07 billion, and management says “demand still outpaces that investment.”
Alphabet Looks Cheapest Among Its AI Rivals
Azure goes up against Google Cloud for the same enterprise AI budgets, which is why Microsoft (NASDAQ:MSFT) belongs in this comparison.
For digital ad dollars, Meta Platforms (NASDAQ:META) competes with Google and sits in a similar AI capex race. All of that spending requires infrastructure support from someone, and we pulled seven of those suppliers into a free report on the AI infrastructure buildout.
| Company | P/E | Operating Margin | Latest Revenue Growth |
|---|---|---|---|
| Alphabet | 14 | 32.06% | 24.23% |
| Microsoft | 30 | 46.78% | 17.75% |
| Meta | 26 | 41.44% | 27.96% |
Microsoft has higher margins, but it trades at a much higher multiple than Alphabet while growing revenue more slowly. Meta grew faster, but in Q2 its operating margin fell to 31% and it missed EPS estimates by 14.42%.
Equity gains improve Alphabet’s P/E, but even its 22x forward multiple is well below both rivals. Our 24/7 Wall St. price target looks reasonable, and arguably conservative, next to this peer group.
What Could Push Alphabet Toward Our Target
My 24/7 Wall St. price target is $431.74, with a buy rating and 70% confidence.
What tips the scale for me is Google Cloud: its growth is accelerating and it is getting more profitable at the same time. The bull case holds as long as the backlog keeps turning into revenue. The thesis weakens if capex keeps rose while cloud margins shrink.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $356.40 |
| 2027 | $440.96 |
| 2028 | $513.09 |
| 2029 | $567.17 |
| 2030 | $631.69 |
Alphabet’s AI strategy execution supports these estimates. Much faster TPU adoption could push results above these figures, while AI spending that fails to earn a return or new regulatory penalties could pull them below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.