Prediction: Alphabet Could Be Sitting on More Upside Than Investors Realize
Alphabet just posted its biggest Cloud growth quarter yet while the stock sits more than 20% below its highs, but the bear case risks are real enough to give even bulls pause. Here is what our model found when it…

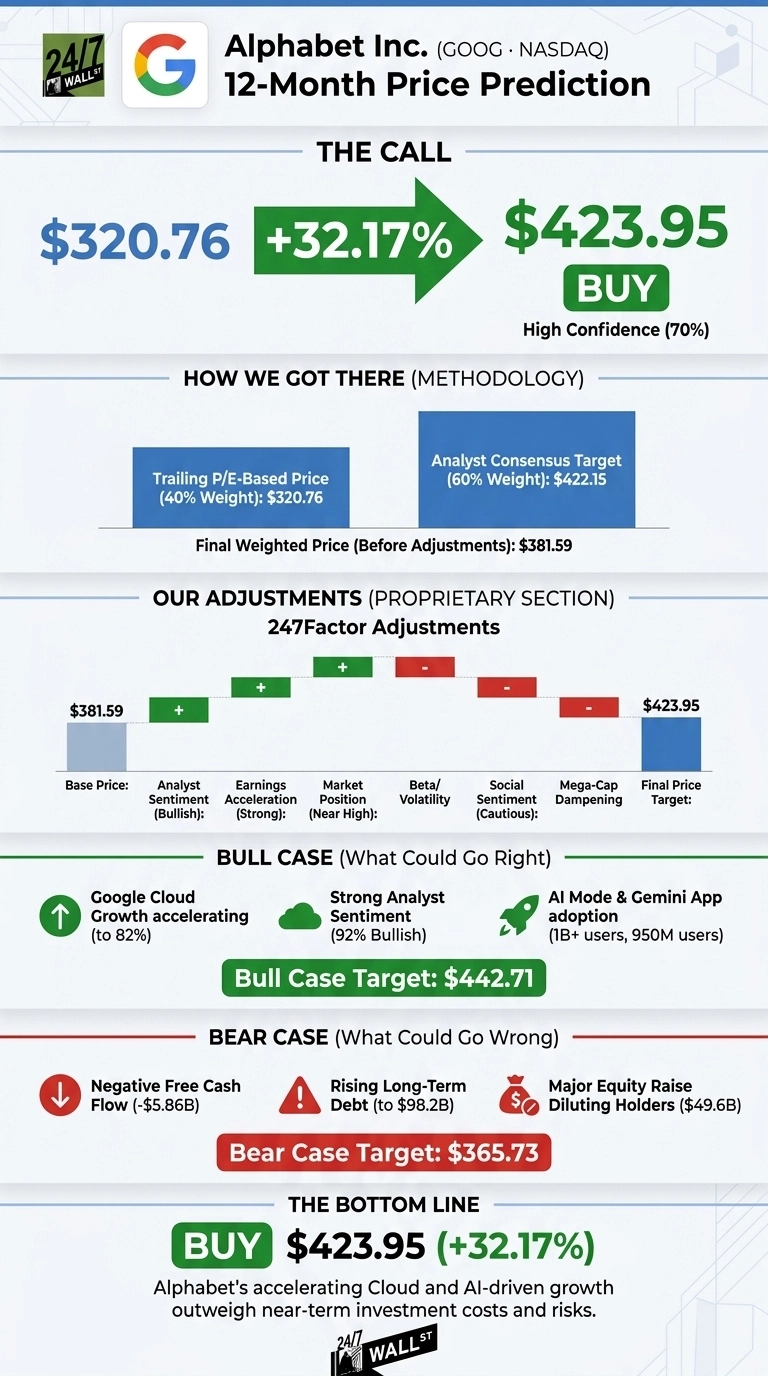
Alphabet (NASDAQ:GOOG | GOOG Price Prediction) closed at $320.76. The 24/7 Wall St. price target stands at $423.95, meaning 32.17% upside over the next 12 months. The stock gets a buy rating from our model, with fairly high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $320.76 |
| Price Target from 24/7 Wall St. | $423.95 |
| Upside/Downside | 32.17% |
| Recommendation | BUY |
| Confidence Level | 70% |
The market is focused on the cost of Alphabet’s AI buildout. More weight goes to what that spending is already producing: a Cloud business that grew 82% last quarter and a backlog of $514 billion.
A Sharp October Pullback Follows a Record Quarter
GOOG fell 7% over the past week and 7.67% over the past month, including a 3.08% drop on October 22. Shares are still up 2.42% year to date and 27.35% over 12 months. The stock trades roughly 21% below its 52-week high of $403.96 and about 26% above its low of $255.43.
In Q2, revenue reached $119.80 billion (up 24.23%), beating the $116.91 billion estimate. EPS came in at $9.11 against a $3.04 estimate.
A $99.03 billion unrealized gain on equity securities accounts for much of that EPS beat. Investors are looking for fresh reasons to own the stock: Forbes this week asked what makes Google stock a buy.

Why Bulls See $442 and Beyond
Cloud is the engine. Growth went from 34% to 48% to 63% to 82% across four quarters, and Cloud operating margin rose to 35.6% from 20.7%. AI Mode has passed 1 billion monthly active users and the Gemini app has 950 million. Management expects most TPU system sales revenue to arrive in 2027.
Sundar Pichai called it “extraordinary opportunities with extraordinary returns.” Wall Street agrees, with 13 Strong Buy, 44 Buy, and 5 Hold ratings and zero Sells. The bull case stands at $442.71.

What Could Derail the AI Payoff
Q2 capex hit $44.92 billion and drove free cash flow to -$5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion, buybacks are on hold, and a $49.6 billion equity raise dilutes existing holders. EU regulatory risk also remains.
On the other side, trailing 12-month free cash flow was still $53.3 billion and interest coverage is 175.5x. The bear case of $365.73 is still above today’s price.
Alphabet Trades at a Discount to Microsoft and Meta
| Company | P/E | P/FCF | Operating Margin |
|---|---|---|---|
| Alphabet | 13 | 55 | 32.06% |
| Microsoft (NASDAQ:MSFT) | 29 | 58 | 46.78% |
| Meta Platforms (NASDAQ:META) | 24 | 31 | 41.44% |
Microsoft competes directly with Alphabet in cloud. Azure grew 43%, well behind Google Cloud’s pace, yet Microsoft trades at more than twice Alphabet’s P/E.
Meta Platforms competes for digital ad budgets and is spending just as heavily on AI. Meta’s Q3 operating margin fell to 20% from 40%. Our target meaning about 16x trailing earnings, which still sits below both peers. That makes it look conservative, even after allowing for Alphabet’s one-time equity gains.
What Could Tip Alphabet’s Outlook From Here
The 24/7 Wall St. price target is $423.95, rated buy with 70% confidence. Cloud’s accelerating, increasingly profitable growth is what drives our model’s call.
A stronger bull case appears if the backlog keeps turning into revenue at expanding margins. Downside risk grows if free cash flow remains negative while borrowing keeps rising. For now, our model’s upside scenario outweighs its downside scenario.

Alphabet Price Prediction 2026-2030
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $423.95 |
| 2027 | $482.32 |
| 2028 | $548.72 |
| 2029 | $624.26 |
| 2030 | $710.20 |
Alphabet needs to keep executing its full-stack AI strategy for these projections to hold. Gemini 4’s competitiveness or a slowdown in Cloud demand could move results sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.