Wall Street Didn’t Expect This AI Stock to Become This Important
NVIDIA now sells something far bigger than chips, and Wall Street is still catching up to what that means for the stock price. One supply constraint is quietly doing more to support the bull case than any earnings beat.

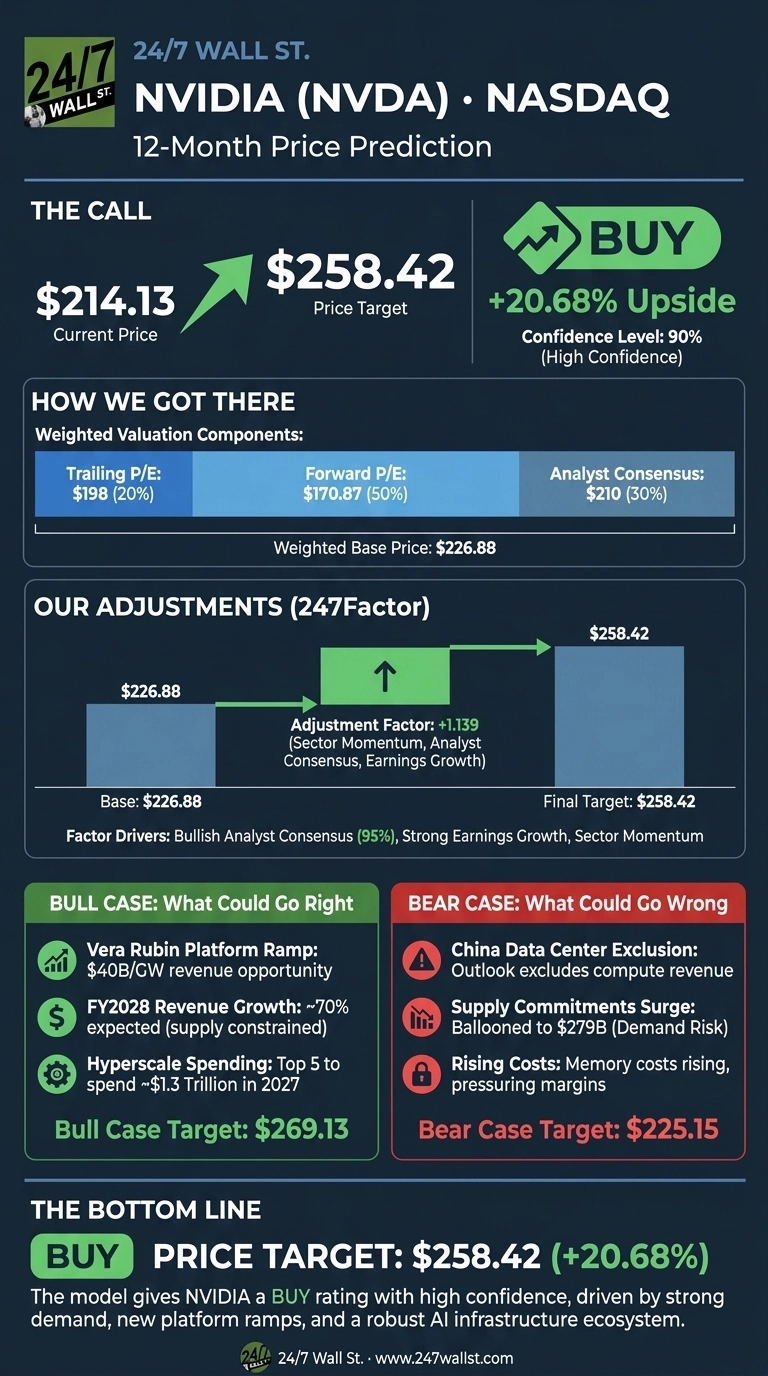
The 24/7 Wall St. price target for NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is $258.42 over the next 12 months. That sits 20.68% above the current share price.

NVIDIA Price Target at a Glance
| Metric | Value |
|---|---|
| Current Price | $214.13 |
| Price Target from 24/7 Wall St. | $258.42 |
| Upside/Downside | 20.68% |
| Recommendation | BUY |
| Confidence Level | 90% |
The model gives NVIDIA a buy rating with high confidence. NVIDIA now sells the whole AI factory: chips, networking, CPUs, software, and even financing.
Management says the business can only supply roughly 70% of demand. That kind of shortage supports both pricing power and visibility into future sales.
A Sharp Weekly Pullback Hides a Record Earnings Run
Shares fell 6.61% over the past week. They were up 0.11% over the past month, 5.46% since July 20 and 15.08% year to date. The stock trades about 12% below its 52-week high of $243.37 and roughly 30.6% above its low of $163.90.
Much of the recent drop came from a global tech selloff driven by worries over AI funding. Jensen Huang later said CoreWeave (NASDAQ:CRWV) is improving and needs no support (Bloomberg).
Fundamentals remained strong. Fiscal Q2 2027 revenue came in at $96.22 billion, ahead of the $92.07 billion consensus and up 105.85% year over year. EPS of $2.22 beat the $2.0887 estimate, making this the sixth straight quarter of beats on both lines. Q3 guidance calls for $108 billion.

Why Bulls See $269 and Beyond
The bull case starts with Vera Rubin. NVIDIA makes about $40 billion per gigawatt from Vera Rubin, compared with $18 billion for Hopper. Management expects fiscal 2028 revenue to grow about 70%, and supply is the only thing holding that number back.
The top five hyperscalers are expected to spend $1.3 trillion on capital projects in 2027 (all of that has to be powered, cooled, and networked by somebody, which is the whole subject of our free report on seven non-chipmaker AI suppliers).
AWS is adding 2 million GPUs. Of the 62 analysts with ratings, 59 rate the stock a buy or strong buy, and the consensus target is $328.72. Our bull scenario reaches $269.13.

Balance Sheet Commitments That Deserve Scrutiny
Supply commitments rose to $279B from $119B in Q1. Days sales outstanding extended to 60 days. The outlook also leaves out any China data center computing revenue. Gross margin should bottom at 71% to 72% in Q4 as memory costs rise.
Bulls point out that margins are expected to recover to 72% to 73% in fiscal 2028 as price increases take effect. The bear case of $225.15 also sits above today’s price.
How NVIDIA Compares to AMD and Broadcom
Advanced Micro Devices (NASDAQ:AMD) is the closest merchant GPU rival. Its data center sales grew 107%, yet AMD trades at a trailing P/E of 199. NVIDIA’s trailing P/E is 43.
Broadcom (NASDAQ:AVGO) is the main custom-silicon alternative to NVIDIA. Its AI semiconductor revenue rose 221% to $16.70 billion. NVIDIA, however, posts faster total growth at higher margins. Against these peers, our target looks reasonable.
| Company | Latest Quarter Revenue Growth | Gross Margin |
|---|---|---|
| NVIDIA | 105.85% | 71.07% |
| AMD | 50.1% | 49.5% |
| Broadcom | 85.5% | 69.1% |
Supply Shortage Tips the Scale Toward Upside
The 24/7 Wall St. price target of $258.42 comes with a buy rating at 90% confidence. What tips the scale is demand running ahead of supply.
The upside case improves if Vera Rubin ramps on schedule. The case weakens if supply commitments exceed orders. For now, NVIDIA’s growth more than supports its multiple.
Looking further ahead, here is where the price target model from 24/7 Wall St. projects NVIDIA could trade, assuming current conditions hold.
| Year-End | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $219.16 |
| 2027 | $275.33 |
| 2028 | $309.60 |
| 2029 | $325.96 |
| 2030 | $368.42 |
These estimates assume NVIDIA keeps delivering on its current plan. Actual results could differ significantly depending on China export policy and how long hyperscalers sustain their AI spending.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.