Nvidia Stock Set For 40% Surge: 3 Catalysts That Could Drive the Next Big Move
Nvidia just posted triple-digit revenue growth and Jensen Huang says the company can only fulfill 70% of demand, yet the stock still trades well below where the math points. Three converging forces suggest the gap between current price and fair…

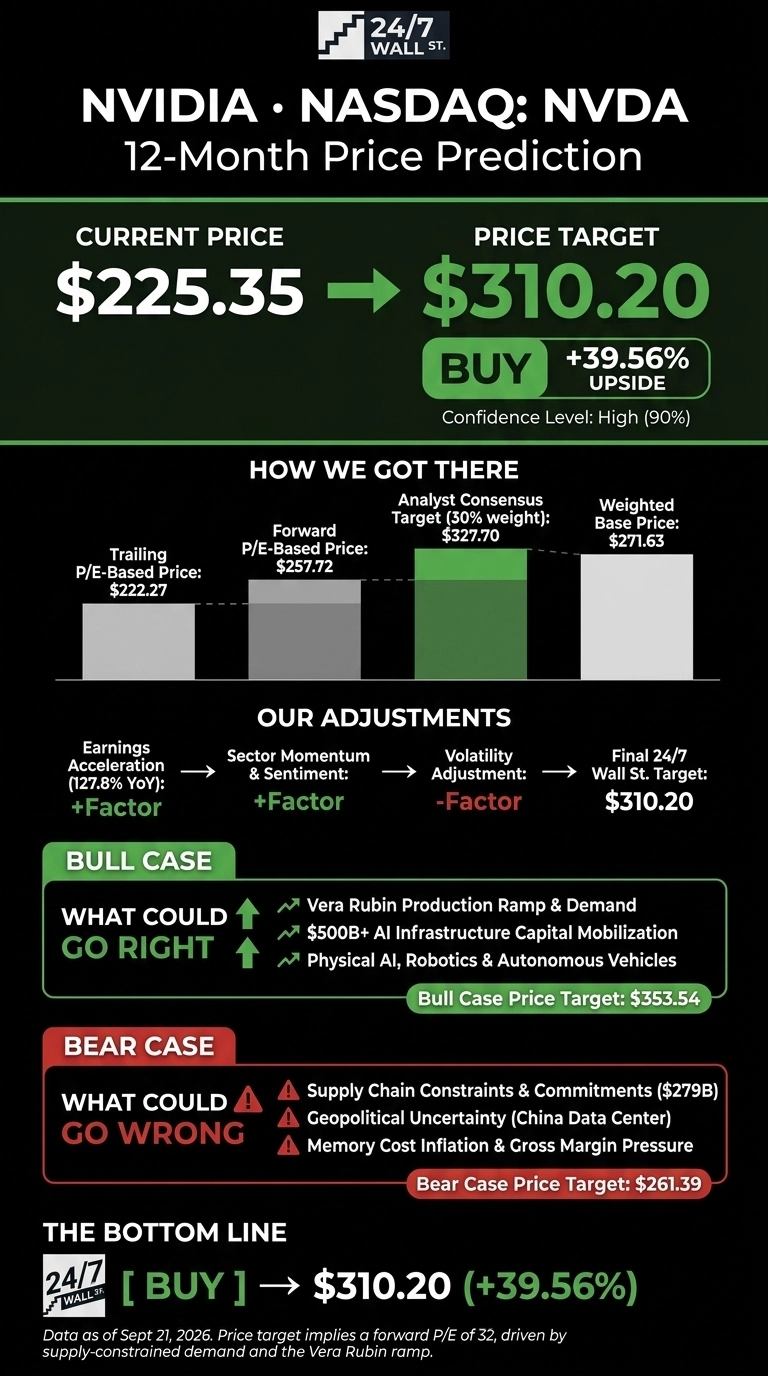
My 24/7 Wall St. price target for NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is $310.20, which implies 39.56% upside from the current $225.35 quote. I rate NVDA a buy with high conviction.
Three catalysts drive the call: the Vera Rubin production ramp, more than $500 billion in third-party AI infrastructure capital being mobilized through NVIDIA partners, and the opening chapter of physical AI across robotics and autonomous vehicles.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $225.35 |
| 24/7 Wall St. Price Target | $310.20 |
| Upside | 39.56% |
| Recommendation | BUY |
| Confidence Level | 90% |

Where NVDA Sits After a Blowout Quarter
NVDA is up 21.11% year to date and 28.17% over the trailing year. Q2 fiscal 2027 delivered revenue of $96.22 billion, up 105.85% year over year, with non-GAAP EPS of $2.22 beating consensus by 6.29%. Data Center revenue hit $89.023 billion. Management guided Q3 to $108 billion.

Why Bulls See $353 or Higher
The bull-case one-year target is $353.54. Jensen Huang told investors NVIDIA can supply only 70% of demand, with fiscal 2028 growth pegged at approximately 70%. Vera Rubin ramps platform value per gigawatt from Blackwell’s $25 billion to $40 billion.
Hyperscaler capex is expected to reach nearly 800 billion in 2026 and 1.3 trillion in 2027, a wave that also pulls in the power, cooling, and networking suppliers we profiled in a free report on seven AI infrastructure names that aren’t chipmakers. Analyst sentiment shows 57 Buy or Strong Buy ratings against 2 Holds and 1 Sell.

Risks Worth Watching
The bear scenario bottoms at $261.39, still above current price. Real risks include supply commitments of $279 billion, guarantee obligations capped at $108.5 billion, and DSO extending to 60 days.
Q3 guidance excludes China Data Center compute revenue citing geopolitical uncertainty. Gross margins are expected to bottom in the 71% to 72% range in Q4 on memory cost inflation, recovering to 72% to 73% in fiscal 2028 as volumes scale.

How NVDA Compares to AMD and Broadcom
Advanced Micro Devices (NASDAQ:AMD) posted Q2 fiscal 2026 revenue of $11.536 billion, up 50.11%, with Data Center up 107%. AMD trades at a trailing P/E of 211 versus NVDA’s 45, making NVDA the cheaper name on growth per valuation dollar.
Broadcom (NASDAQ:AVGO) competes in custom AI ASICs and networking. Q3 fiscal 2026 revenue reached $29.591 billion, up 85.5%, with AI semiconductor revenue of $16.70 billion growing 221% year over year. Its acceleration validates NVDA’s guided $108.0 billion quarter sits inside a real industry wave. The peer set makes $310.20 look reasonable.
I’d Buy NVDA Here
I’d own NVDA at $225.35 with a 24/7 Wall St. price target of $310.20 and a buy rating at 90% confidence. Supply-constrained demand into a Vera Rubin ramp management calls the fastest in company history drives the call.
I’d stay a buyer if hyperscaler capex tracks toward 1.3 trillion in 2027. I’d step aside if memory pricing pushes gross margin below 71% or if China restrictions widen beyond the Data Center compute carve-out.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $237.60 |
| 2027 | $312.33 |
| 2028 | $380.37 |
| 2029 | $447.65 |
| 2030 | $535.98 |
These projections assume NVIDIA executes on the Vera Rubin ramp and hyperscaler AI spending holds. Significant upside or downside could result from broader China market access, a major AI capex reset, or accelerated adoption of physical AI and robotics platforms.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.